


EN
IDACORP (IDA) Raised Guidance And Revenue Grew, Is It Still Below Fair Value?
IDACORP (IDA) has moved into focus after it raised its full year 2026 earnings guidance and reported higher third quarter and nine month revenue and net income compared with the prior year.
The share price reaction has been firm rather than euphoric, with IDACORP’s stock up 8.22% on a 1 month share price return and 4.57% on a 3 month share price return. Longer run total shareholder returns of 69.35% over three years and 62.23% over five years point to momentum that has been building over time rather than fading.
Compare IDACORP’s momentum and guidance upgrade with other regulated utilities by scanning our hand picked 42 power grid technology and infrastructure stocks that are also tied to grid build outs and energy infrastructure.
After a sharp run on upgraded guidance, IDACORP now asks a simple question of investors. Is it worth paying up today, or does patience for a cheaper entry make more sense as the valuation section shows?
Most Popular Narrative: 3.2% Undervalued
IDACORP’s last close at $146.55 sits below the analyst consensus Narrative fair value of $151.44, which the analyst consensus Narrative on Simply Wall St derives from detailed forecasts for revenue, earnings and profit margins using a 7.24% discount rate.
Massive planned capital investments, with IDACORP expecting to spend between US$1.3b and US$1.5b on CapEx in 2026 and around US$7b from 2026 to 2030 on generation, storage and transmission projects such as B2H and SWIP North, are forecast to drive rate base from about US$5.3b in 2025 to around US$11b by 2030 and increase regulated earnings.
See why 4 investors see IDACORP as 3% undervalued.
Result: Fair Value of $151.44 (UNDERVALUED)
Still, IDACORP’s heavy reliance on hydropower conditions and its large, debt- and equity-funded CapEx plan could quickly test that undervalued narrative.
Find out about the key risks to this IDACORP narrative.
Another View: IDACORP Looks Pricey On Earnings
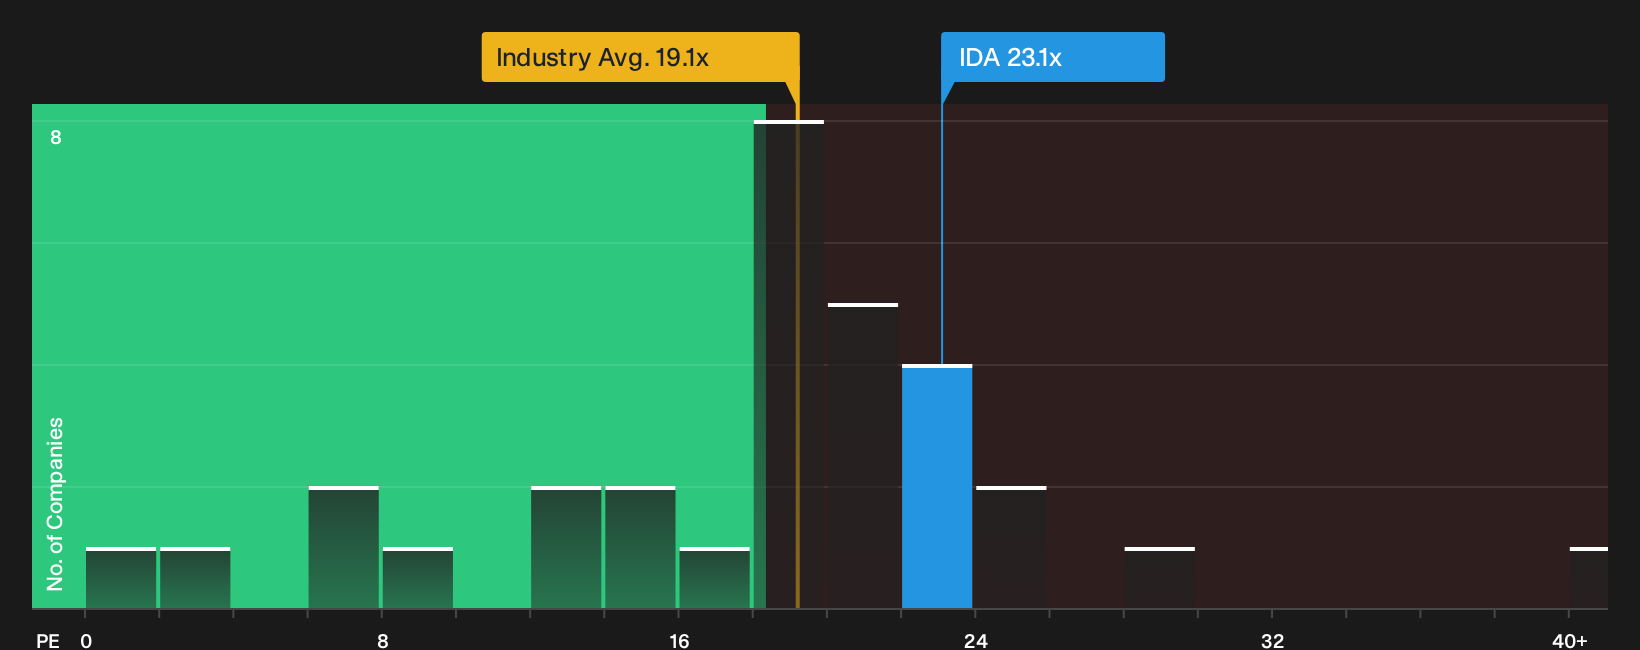
Look past the narrative of fair value and the picture shifts. On a P/E of 23.1x versus a fair ratio of 20.7x, IDACORP trades richer than both the US Electric Utilities sector at 19.1x and its peer average of 21.5x. If the share price moved toward that fair ratio, current buyers could be paying up rather than locking in a cushion.
This leaves an open question: Is the higher multiple a reasonable price for IDACORP’s growth story, or a valuation risk if sentiment cools and earnings expectations reset?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or early opportunity? Weigh the upgraded guidance against the valuation premium, then move quickly enough to build your own judgment using the 2 key rewards and 2 important warning signs.
Looking for more IDACORP style investment ideas?
Do not stop with IDACORP. Use the same disciplined lens across sectors and let a structured screener surface fresh ideas before the market pays attention.
- Target income potential by reviewing a curated set of high yield payers in the 7 dividend fortresses.
- Hunt for mispriced quality through the 40 high quality undervalued stocks that filters for strong balance sheets and solid fundamentals.
- Reduce portfolio stress by focusing on sturdier tickers highlighted in the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com