


EN
Spotify Technology (SPOT) Brings United Flyers Onboard As Valuation Debate Heats Up
Spotify Technology (NYSE:SPOT) just pushed deeper into the skies, as United Airlines passengers can now log directly into personal Spotify accounts from seatback screens, linking AI driven playlists to a captive in flight audience.
Against that product backdrop, Spotify Technology has seen a 30 day share price return of 13.96% and a 90 day gain of 20.36%, while the 1 year total shareholder return has slipped 3.2%. Short term momentum has picked up even as the longer track record remains mixed.
Scan the skies for the next Spotify style opportunity and compare this deal-driven streamer with a hand picked set of 40 AI small caps riding personalized content and AI powered engagement.After a sharp run on the back of this United Airlines partnership and fresh AI storylines, Spotify Technology now poses a harder question: Does the current price still leave enough upside for the risk being taken?
Most Popular Narrative: 15.6% Undervalued
On the Simply Wall St Community view, Spotify Technology carries a fair value of $714.13 against a last close of $603.01, implying meaningful upside if that estimate proves accurate. That gap is anchored in how one investor frames user scale, margins, and new formats.
Spotify continues to compound user scale while improving unit economics. Premium subscribers and overall engagement are still growing, gross margins have expanded meaningfully, and the company is generating solid operating profit and free cash flow. The core tension remains the balance between growth investments, content costs, and competitive intensity in a crowded audio market.
See why 1 investors see Spotify Technology as 16% undervalued.
Result: Fair Value of $714.13 (UNDERVALUED)
Still, rising royalty costs and heavy spending on AI and new formats could squeeze Spotify Technology margins if user engagement or monetization disappoints.
Find out about the key risks to this Spotify Technology narrative.
Another View: Spotify Technology Looks Expensive On Earnings
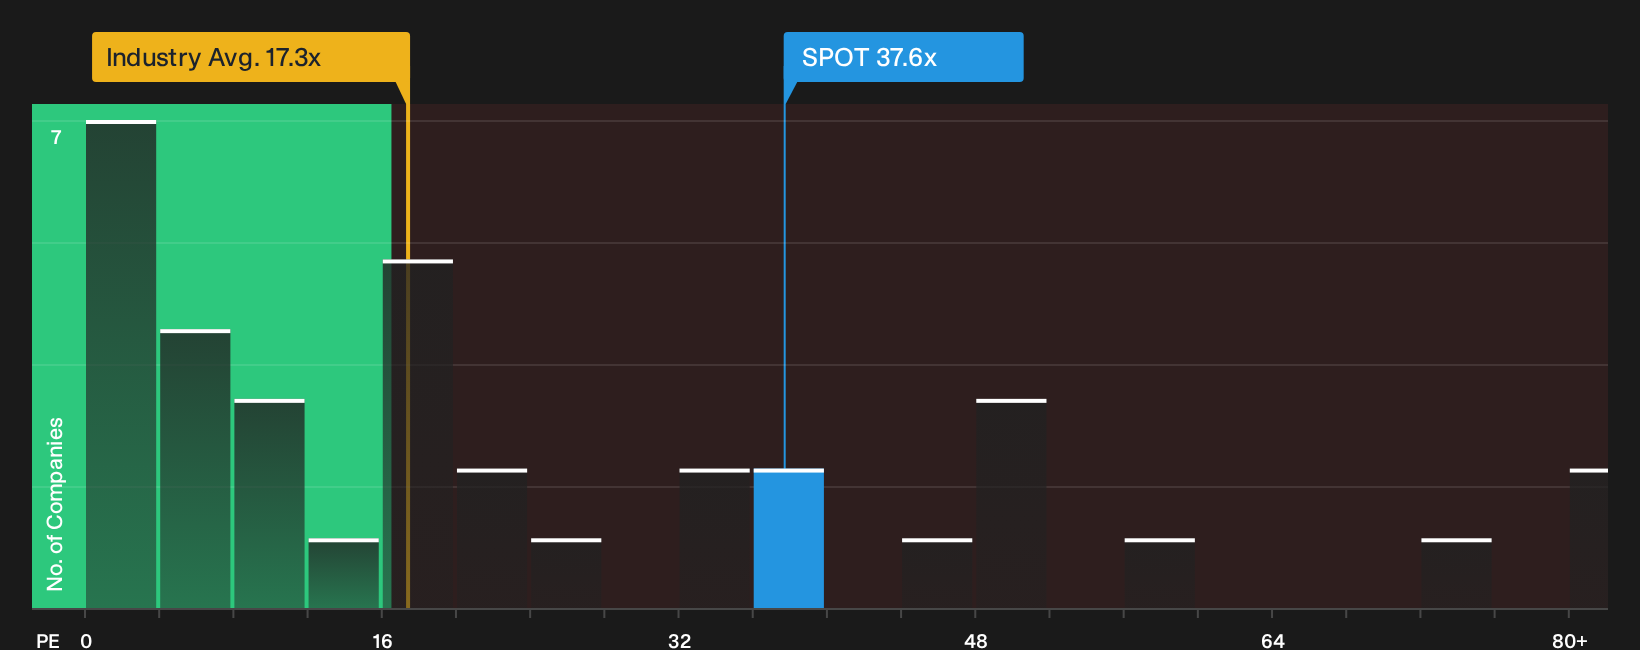
The share price story changes when you stop at the P/E multiple. Spotify Technology trades at 37.6x earnings, which is higher than the US Entertainment sector on 17.3x and above the fair ratio of 28.2x that the market could move toward over time.
Peers as a group sit on 41.1x, so SPOT is cheaper than similar stocks but still rich versus the wider industry and that fair ratio. For anyone weighing fresh capital after the recent rally, the question becomes whether those extra turns of earnings justify the valuation risk if sentiment cools.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Spotify Technology so far. If you want to move early and build your own view from the ground up, start with the headline metrics and then weigh the 3 key rewards and 1 important warning sign.
Looking for more Spotify Technology style ideas?
If Spotify Technology has sharpened your appetite for opportunity, do not stop here. Plenty of other stocks quietly line up strong fundamentals and misunderstood potential.
- Target resilient growth potential by scanning a 19 high quality undiscovered gems that pairs solid financials with underfollowed stories before attention fully catches up.
- Strengthen capital preservation by reviewing a 31 resilient stocks with low risk scores that filters for sturdier balance sheets and lower overall risk profiles when markets turn choppy.
- Build a sturdier core portfolio by focusing on a list of solid balance sheet and fundamentals (25 results) that highlights financially sound businesses designed to endure tougher conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com