


EN
3 Australian Dividend Stocks To Own In November 2026
Asian share markets recently bounced as AI related stocks recovered in the United States, reminding investors how quickly sentiment can swing. Income seekers in Australian dividend stocks often want the opposite: they look for companies that keep paying shareholders even when headlines turn rough. This article breaks down three higher yield royalty style payers and explains why each might appeal to long term dividend collectors.
The three stocks below are a starting sample of high yield dividend payers, and the full Dividend Aristocrats screen on Simply Wall St surfaced 2 more companies with equally compelling income stories that are not covered here.
If you want to go straight to the full list, analyze payout strength and identify your own highest conviction ideas, head into the Dividend Aristocrats screener.
CTI Logistics (ASX:CLX)
CTI Logistics runs a broad transport and logistics operation across Australia, with most revenue coming from transport at about A$259 million and logistics at roughly A$135 million, supported by a smaller A$10 million property arm, and is valued at around A$225 million. Contracted logistics and warehousing provide the clearest tie to the Dividend Aristocrats theme through long term, cash flow friendly contracts.
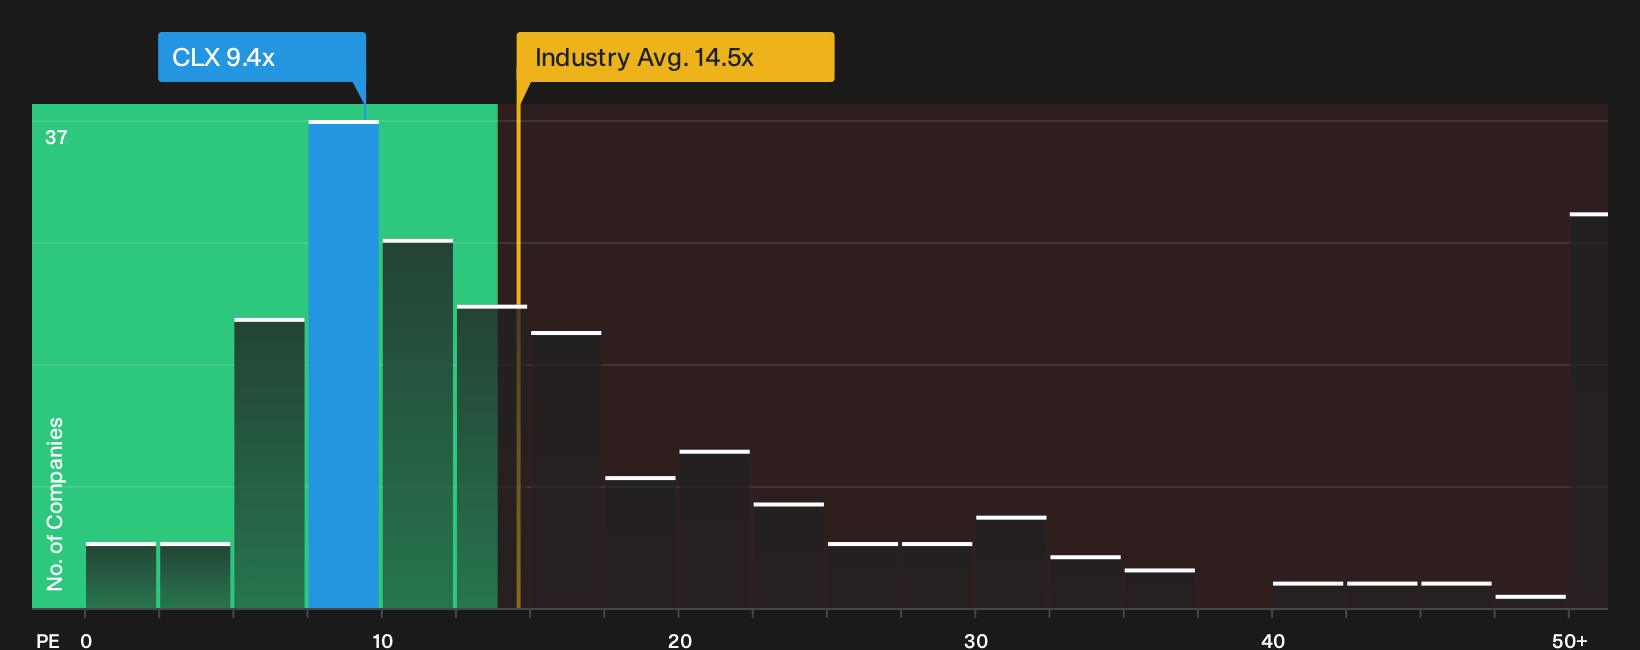
CTI Logistics connects to the Dividend Aristocrats idea through its contracted logistics and warehousing arm, where long term distribution center and temperature controlled storage deals helped support A$357.13 million in revenue and A$24 million in net profit in 2025/26 plus an A$0.08 fully franked dividend. Earnings growth, a P/E of 9.4x against higher sector multiples and improving margins all point to solid income potential, depending on how one unresolved pressure around dividend consistency plays out.
That uncertainty around how consistently CTI Logistics can share those earnings with investors is exactly why the 4 key rewards and 2 important warning signs could reshape your view of this dividend stream.
Peet (ASX:PPC)
Peet develops and sells residential land across Australia and also runs a Funds Management arm that earns recurring fees from residential development funds, a key link to the Dividend Aristocrats income theme. Most revenue comes from Development at about A$305 million, with A$95 million from Funds Management, and the business is valued at roughly A$702 million.
Peet gives income investors a mix of high yield, a visible A$862 million contracted pipeline backing earnings guidance into FY2027, and a funds management fee stream that can support dividends. The main watchpoint is how dividend policy evolves under changing funding conditions and potential ownership shifts, depending on how one unseen pressure plays out.
That unseen pressure is exactly why income hunters usually start with the 2 key rewards and 1 important warning sign, then weigh how secure Peet’s payout really looks.

Sandfire Resources (ASX:SFR)
Sandfire Resources is a copper focused miner whose Motheo and MATSA hubs underpin the high yield story that puts it on this Dividend Aristocrats list. Most revenue comes from Motheo at about $745 million and MATSA at roughly $910 million, with a market value near A$8.9b.
The analyst consensus Narrative on Simply Wall St frames Sandfire Resources as a high yielding copper producer that leans on stable hub production and cost control to keep dividends flowing rather than chasing aggressive volume growth.
"Sandfire Resources is progressing the multi hub copper model around MATSA in Spain and Motheo in Botswana, with management targeting broadly flat copper equivalent production through FY29 and at least 15 years of reserves at each complex. This directly feeds into long term revenue visibility and supports earnings stability."
The real test for dividend collectors will be how one unresolved pressure around cash flow coverage and future capital spend shapes that earnings stability story.
That cash flow question is where the full narrative for Sandfire Resources pulls everything together and reveals how Sandfire Resources could balance capital spend, risk and a potentially accelerating payout profile.

Seeking Alternatives Before The Crowd Moves
Fresh ideas move first. By the time every headline chases the same winners, early momentum is already flying. Scan these curated shortlists while it matters and get in early.
- Spot potential breakout stories early and track 14 high quality undiscovered gems that are still under the radar for now, before wider attention starts bidding up valuations.
- Lock onto resilient income payers by scanning the 5 dividend fortresses that aim to keep yields steady even when sentiment drops or volatility spikes.
- Ride long term demand for critical materials with the 16 top copper producer stocks that may benefit if infrastructure and electrification themes keep building momentum.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com