


EN
Why Parsons Fell Even As Sales Rose
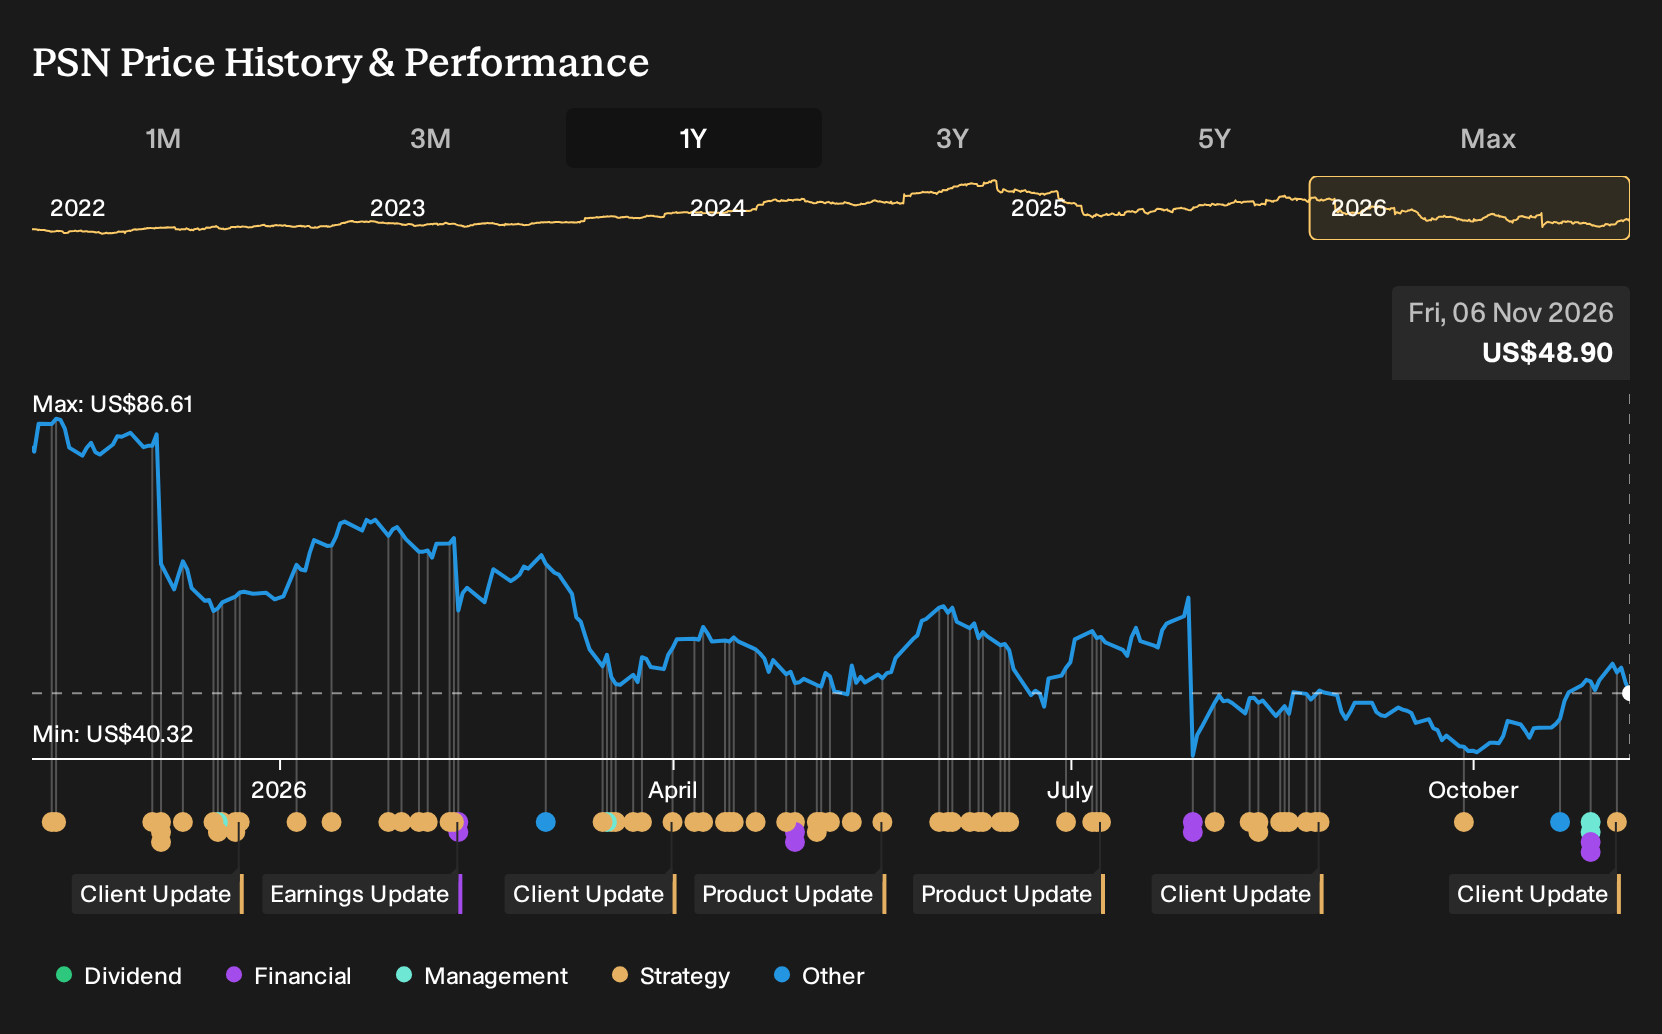
Parsons spent 2026 collecting fresh work from the U.S. Air Force and Navy, plus high profile roles on bridge, tunnel, and energy resilience projects, yet the share price told a very different story. For Parsons shareholders, the loss over the past year was 43.1%, including dividends. If you had bought after upbeat 2025 guidance and backlogs on record, how should you now weigh that severe drawdown against the contract wins that keep arriving?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
If the move has made Parsons harder to judge, start where the gap is still open and scan 40 high quality undervalued stocks.
The Two Stories Parsons Investors Were Pricing In
The shares cost US$82.08 at the start of the period, and Parsons investors were effectively choosing between two competing stories about what that price implied.
On the upbeat side, one narrative saw a fair value of US$86.67, roughly 6% above the start price. This view was built on assumptions that revenue would grow 3.7% a year and profit margins would reach 4.7% within three years.
The more cautious storyline pointed to fair value of US$65, about 21% below the start price, and emphasized the risk that reliance on large government contracts and acquisition integration could keep earnings volatile.
What The Parsons Evidence Actually Tested
Parsons kept landing large defense and infrastructure work, including a US$245 million Navy satellite ground systems deal and a role in a US$2b Army energy resilience program, which backed the optimism about contract flow. At the same time, Q3 2026 revenue of US$1,650.5 million sat alongside lower net income and a thinner 3.3% margin, which challenged the stronger profitability story. The evidence cut both ways.
The hinge assumption here was that healthier contracts would quickly translate into fatter margins. When you assess another contractor, track whether backlog wins show up in net income and margin percentage within a few reporting periods, not just in press releases.
What Parsons' Lower Price Now Asks You To Believe
Parsons trades at US$48.9 today, with the bullish analyst Narrative on Simply Wall St arguing that its Fair Value figure still sits above that level.
The Narrative leans heavily on Parsons turning contract work into higher margin AI enabled and product revenue, so a buyer now would be testing that business mix shift actually plays out.
"The main thing that has to go right is Parsons successfully executing its shift toward higher-margin, lower-risk federal and critical infrastructure work, while delivering on AI-led and product-based contracts without repeating large one-time charges."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Go Straight To The Source
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 19% below our estimate - builds custom security hardware that ties users to one operating system.
- Company 2 - 41% below our estimate - shortens subsea project timelines via unified engineering, equipment and services contracts.
- Company 3 - 31% below our estimate - runs higher-cost gold mines trading reserve duration against geopolitical and balance-sheet risk.
That is three of the list. See all 25 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com