


EN
Is Hilltop Holdings (HTH) Undervalued Following Higher Loan Growth Guidance?
Investor attention on Hilltop Holdings (HTH) has picked up after management raised loan growth guidance for its PlainsCapital Bank unit, pointing to sustained lending activity while leaning on diversified fee income to help offset funding cost pressures.
For context, Hilltop Holdings shares last closed at US$36.40, with the 1-day share price return down 1.11% and the 90-day share price return lower by 7%. However, the year-to-date share price return of 7.37% and 1-year total shareholder return of 10.45% suggest that momentum has cooled recently after a stronger run over the past few years, including a 3-year total shareholder return of 35.60%.
Scan for other banks built for higher-for-longer rates by reviewing our curated list of list of solid balance sheet and fundamentals (25 results) that echo parts of the Hilltop Holdings playbook.
Hilltop Holdings has cooled off after solid multi year gains, yet fresh loan guidance and fee income support have renewed interest in the stock. Is the bigger opportunity already used up, or still ahead based on the numbers?
Most Popular Narrative: 13% Undervalued
On the analyst consensus Narrative on Simply Wall St, Hilltop Holdings screens as undervalued, with a fair value of $41.67 against the last close at $36.40. That gap frames how management guidance on loans, fees, and capital returns feeds into the current investment debate.
The main thing that has to go right is that PlainsCapital Bank sustains its targeted 5 to 7% held for investment loan growth and stable net interest income while PrimeLending’s cost cuts and restructuring narrow its pretax losses in a still pressured mortgage market.
The current valuation implies that Hilltop Holdings’ share price already reflects a fair outcome where solid bank and broker dealer profitability and active capital returns are offset by mortgage losses, slow net interest income growth, and the risk of weaker efficiency and earnings.
See why 1 investors see Hilltop Holdings as 13% undervalued.
Result: Fair Value of $41.67 (UNDERVALUED)
Still, the Hilltop Holdings narrative can unravel if mortgage losses linger at PrimeLending or if fresh credit issues force heavier provisioning and weaker returns.
Find out about the key risks to this Hilltop Holdings narrative.
Another View on Hilltop Holdings Valuation
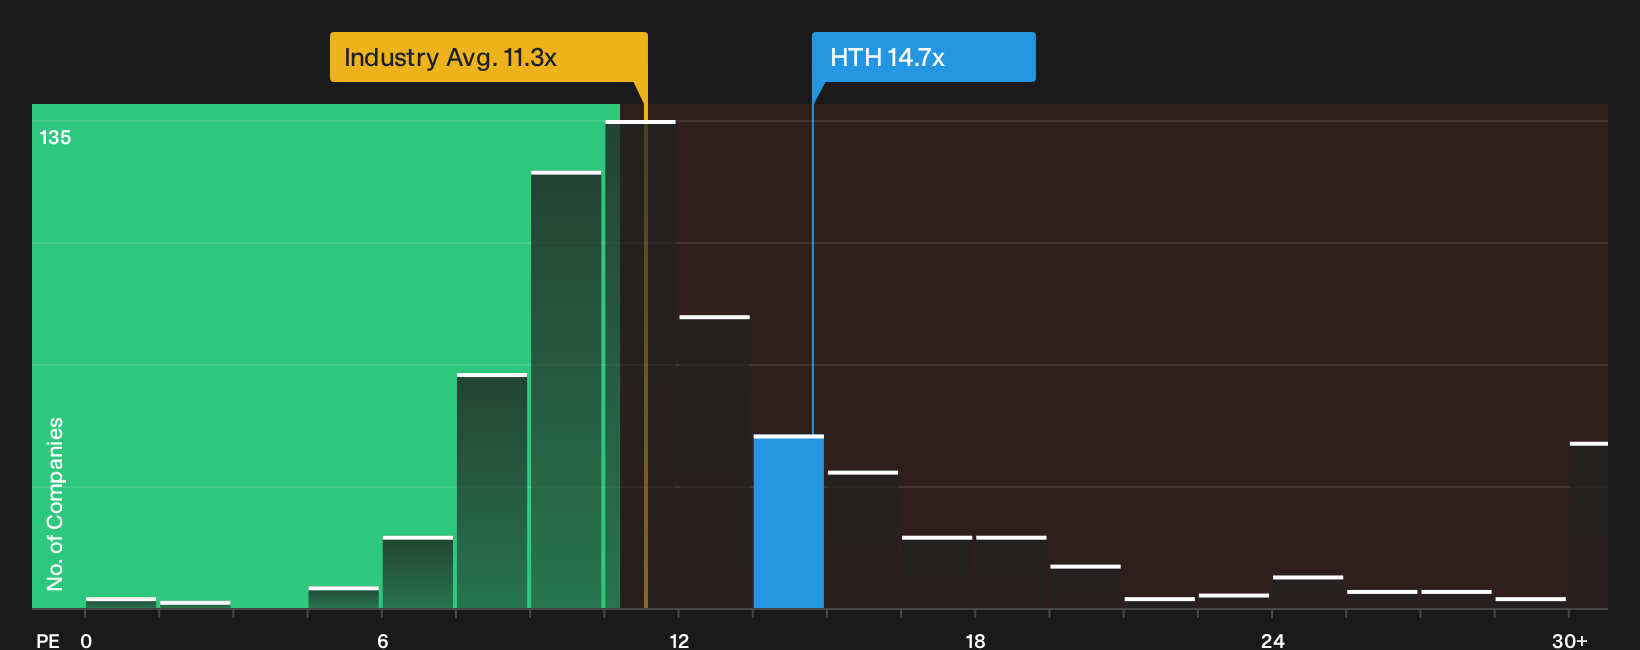
The Simply Wall St fair value model points to Hilltop Holdings trading below an estimated value of $41.67, yet the P/E ratio of 14.7x tells a different story. That multiple sits above the US Banks industry at 11.3x, peers at 11.4x, and even a fair ratio of 10.2x. This suggests the share price could drift toward that lower benchmark or hold its current premium. Which signal do you treat as more important, the discount to fair value or the richer earnings multiple?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The Hilltop Holdings story has presented mixed messages so far. If you want to move quickly and form your own view, consider reviewing the 2 key rewards and 2 important warning signs.
Looking for more Hilltop Holdings style ideas?
If Hilltop Holdings has you thinking harder about where to put fresh capital, do not stop at a single ticker when there are targeted tools built to surface more candidates.
- Target resilient performers that aim to protect capital first by scanning a curated group of 31 resilient stocks with low risk scores with measured risk profiles and steadier fundamentals.
- Hunt for quality at a discount by reviewing a focused lineup of 40 high quality undervalued stocks that pair solid financials with prices below their estimated worth.
- Zero in on potential future leaders before the crowd by searching through a hand picked pool of 19 high quality undiscovered gems that many investors may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com