


EN
Should Q3 Earnings Results Require Action From Evonik Industries Stock Investors?
- Evonik Industries reported third quarter 2026 sales of €3,825 million and a net loss of €53 million, with nine month 2026 sales of €11,144 million and net income of €156 million.
- The mix of higher sales alongside a quarterly loss and lower nine month earnings per share highlights pressure on profitability, even as activity levels remain solid.
- Next, the focus shifts to how Evonik Industries' higher sales but weaker nine month earnings shape the broader investment narrative from this point forward.
Scan how Evonik Industries' mixed earnings pattern compares with peers by reviewing our curated 223 high quality undervalued stocks, which pairs resilient cash generation with balance sheets built to handle profit pressure.
Evonik Industries Investment Narrative Recap
To own Evonik Industries, you need to believe the shift toward higher margin specialty chemicals and cost programs can offset earnings volatility. The latest quarter shows this tension clearly. Sales for both the quarter and nine month period sit higher year on year, yet the nine month net income of €156 million is below the prior period.
For the near term, the key catalyst is still execution on workforce reductions and portfolio reshaping outlined in the analyst consensus Narrative on Simply Wall St. The biggest risk is that restructuring, one off items and a reported quarterly loss of €53 million keep profit margins and free cash flow under pressure longer than expected.
The most relevant piece of news for this story remains the third quarter and nine month 2026 earnings release itself. Sales of €3,825 million for the quarter and €11,144 million year to date show activity across segments is holding up, yet earnings quality looks mixed, with a quarterly loss and lower earnings per share.
For you as a shareholder, this puts execution front and center. The results arrive while Evonik Industries is running sizeable cost programs and portfolio changes that analysts already factor into expectations. Delivery against those plans, while managing debt and a dividend that is not well covered by earnings, is likely to shape how quickly profitability metrics can recover.
Evonik Industries' current earnings are €121.0 million, with analysts forecasting revenue growth of 1.9% per year and expecting earnings to reach €550.5 million by 2029. This would require an earnings increase of about €429.5 million to meet the 2029 consensus.
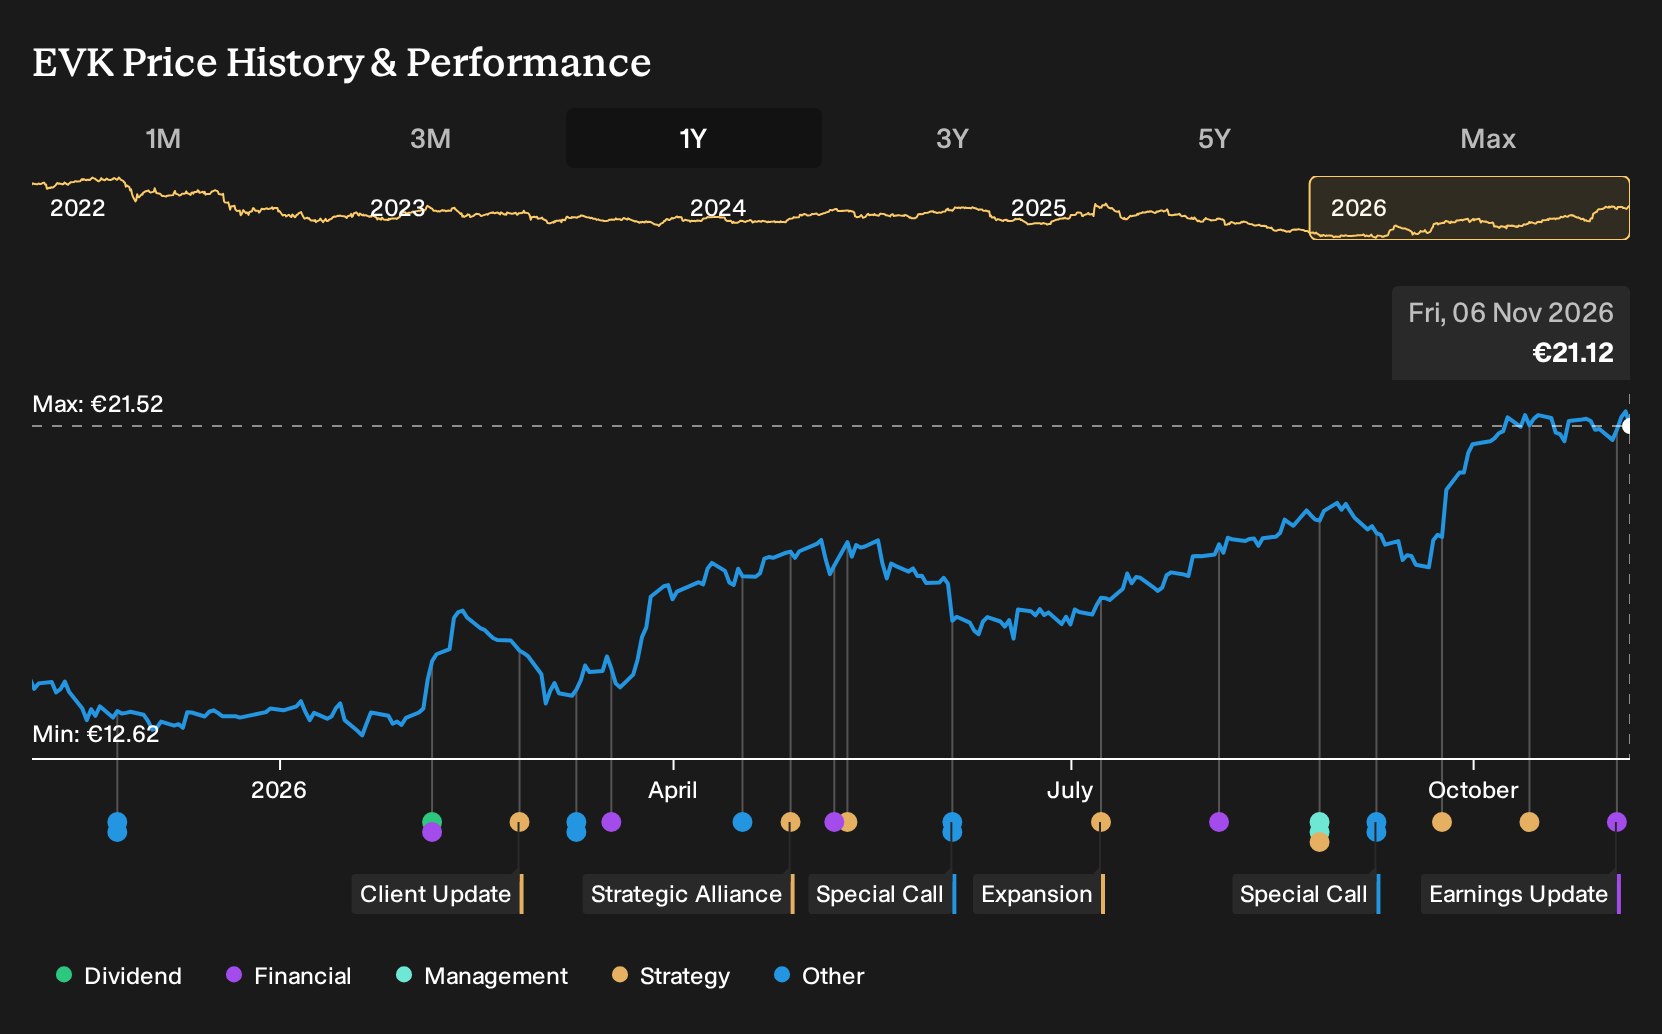
Uncover why Evonik Industries' fair value indicates a 13% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Some of the most optimistic analysts frame the real catalyst as new profit streams, not just cost cuts. They were pencilling in revenue of about €15.6b and earnings of roughly €714.9 million by 2029 for Evonik Industries, which is far above consensus. This earnings release may prompt you to reassess which camp you lean toward.
Explore 3 other Evonik Industries fair value estimates, including one that suggests as much as 248% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Evonik Industries research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Evonik Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Evonik Industries' overall financial health at a glance.
Looking for more investment ideas beyond Evonik Industries?
Once you have a handle on Evonik Industries, it often helps to broaden your watchlist with a few targeted screens that match your risk profile and income goals.
- For investors who want income resilience, focus on payout strength with our curated set of 225 dividend fortresses that aim to pair yield with durability.
- If capital protection is front of mind, start with a basket of 207 resilient stocks with low risk scores that score well on stability and financial robustness.
- To widen the opportunity set beyond well known large caps, scan a 572 high quality undiscovered gems that combine solid fundamentals with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com