


EN
US stock outlook | Futures of the three major stock indexes rose sharply, Nvidia dived and fell below $95 before the market. The latest US inflation data and financial reports for the three major technology stocks are coming this week
Pre-market market trends
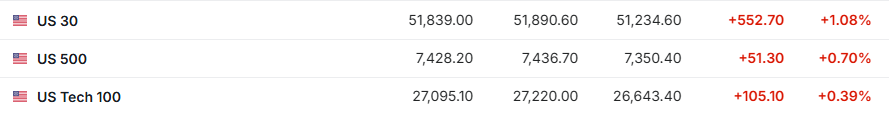
1. On November 9 (Monday), the futures of the three major US stock indexes rose sharply before the US stock market. As of press release, Dow futures were up 1.08%, S&P 500 futures were up 0.70%, and NASDAQ futures were up 0.39%.
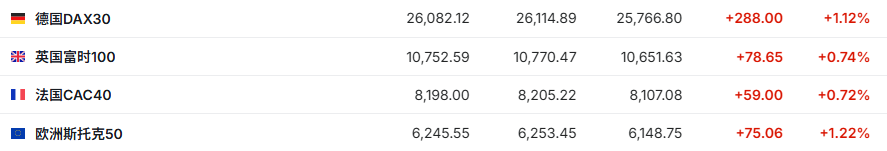
2. As of press release, the German DAX index rose 1.12%, the UK FTSE 100 index rose 0.74%, the French CAC40 index rose 0.72%, and the European Stoxx 50 index rose 1.22%.
3. As of press release, WTI crude oil fell 2.97% to $88.13 per barrel. Brent crude oil fell 3.46% to $94.92 per barrel.

Market news
This week's outlook for US stocks: CPI debuted on Tuesday, and the financial reports of the three major technology stocks picked up. Can AI trading stop the sell-off? Investors faced an unstable US stock market this week: core AI transactions were deeply sold off. Technology stocks suffered a severe setback last week, and the market feared that the Democratic Party's “blue wave” would slow down the progress of AI data center construction. This added unease to the market before inflation data and earnings reports from various tech companies were released. The most important events of the week are the US October CPI data to be released on Tuesday and the October PPI data to be released on Friday. At a time when the Federal Reserve's monetary policy expectations are clearly shifting, the two inflation data will be an important basis for judging future interest rate trends. The latest October non-farm payroll data was strong, further weakening the market's expectations for the Federal Reserve to shift to easing in the short term. After the employment report was released, the interest rate futures market's bet on the Federal Reserve's interest rate hike of 25 basis points in December clearly heated up. Furthermore, several Federal Reserve officials will deliver speeches this week, and investors will seek clues about the Federal Reserve's monetary policy path. In terms of corporate earnings, CoreWeave (CRWV.US), Applied Materials (AMAT.US), and Cisco Systems (CSCO.US) will be released one after another this week. Among them, the new cloud vendor Coreweave is at the center of market concerns about AI construction financing. Its stock price has been hit hard in recent weeks, and its earnings report may have an impact on this stock and broader AI transactions.
Trump: We will not escalate the war with Iran; we are close to reaching an agreement with Iran. US President Trump said in an interview program broadcast on the 8th that the war in Iran will not escalate. Trump said, “I didn't plan to do this. I don't see any reason to do that.” He believes they are close to reaching an agreement with Iran, and “they want to reach an agreement... if it weren't for the election, they could have reached an agreement a long time ago or in a few days.”
The midterm elections revealed the fragility of the market! AI trading has been severely tortured, and US stock profit expectations may face major adjustments. Midterm elections usually make investors stop worrying about political factors and refocus on fundamentals. But this time, political factors directly collided with the investment cycle, to a large extent, to reveal these vulnerabilities. After the US midterm election results and subsequent market collapse, investors may need to readjust their expectations for return on investment. Currently, the surge in volatile futures shows that short-term risk is still the main concern of the market, and the market is quickly turning its attention back to the fundamentals of economic and monetary policy. Compared to short-term macroeconomic and monetary policy changes, the uncertainty of the AI investment cycle itself may be a deeper concern for the market. The uncertainty of AI infrastructure investment prospects may eventually be further transmitted to corporate profit expectations. In the future, the market may need to re-examine previously overly optimistic profit forecasts.
Capital is flocking to US debt to help the “anchor of global asset pricing” accelerate the decline, and AI computing power and semiconductor repair markets add further momentum? At the same time, the US bond market is receiving bullish support from the global AI computing power theme, strong safe-haven demand for capital under the sharp decline in semiconductors and a wide range of technology stocks, and the influx of global capital in the face of cooling expectations of fiscal expansion and easing pressure on energy inflation. If this 10-year US Treasury yield curve, which has the title of “the anchor of global asset pricing,” continues to move downward, it is expected to significantly reduce the risk-free interest rate/risk-free yield pressure on the stock market valuation side. In particular, it is expected to drastically reduce the valuation pressure on AI computing power and semiconductors, which have recently plummeted, and may even drive AI financing costs into a continuous downward trajectory. If corporate profits also continue to grow resilient, the allocation appeal of bonds may increase at the same time as AI computing power, semiconductors, and the recovery opportunities of global technology stocks in a broad sense.
Gold has experienced a sharp short-term shock, and the long-term bullish logic is still strong? Citi looks at 5,000 US dollars, and the central bank buys to support the “belief in gold.” Citi's recently proposed gold price path is more dependent on energy and policy transitions: a gold target of 4,500 US dollars for the next 0 to 3 months and a target of 5,000 US dollars for 6 to 12 months. The key premise is that the Strait of Hormuz will be reopened, the conflict between Yemen and Saudi Arabia will ease before the end of the year, push oil prices down markedly, and create room for the Federal Reserve to move towards easing. Citi's investment logic for gold is that global central bank purchases continue to underpin gold, and as US bond yields continue to decline due to safe-haven purchases and the Democratic Party regains a majority in Congress, the energy shock caused by the Middle East, Russia-Ukraine conflict may reduce real interest rates and pressure on the US dollar, and re-attract ETFs and trend capital to buy gold. It is worth noting that $5,000 is the price target for a specific time window. Citi also lowered its average gold price forecast for the full year 2027 to 4,700 US dollars, showing that the same expected repair process had twists and turns.
Individual stock news
Hwang In-hoon's personal scandal was compounded by internal investigations, and Nvidia (NVDA.US) stock prices dived ahead of the market. Affected by CEO Wong In-hoon's personal scandal and the company's initiation of an independent investigation, Nvidia's US stocks fell nearly 5% before the market on Monday as of press release. According to reports, Huang Renxun sent an internal letter to all employees on November 8 admitting being unfaithful to his wife and apologizing to his family, employees, board of directors, partners, and shareholders. There are reports that the woman involved in Hwang In-hoon's affair is an asset of a foreign intelligence agency. Nvidia's board of directors announced on the same day that a special committee composed of independent directors has been set up to launch an independent investigation with the assistance of external independent legal advisers to find out whether Hwang In-hoon has become the target of foreign intelligence agencies' actions. The board of directors said that there is currently no reason to believe that national security interests or Nvidia's core trade secrets have been compromised, but the special investigation will still check all available information one by one. Some analysts pointed out that at present, Wall Street's overall judgment on Nvidia has not changed, the company's fundamentals have not changed, and the third quarter earnings report will still be released as scheduled. However, there are also quite a few securities analysts who believe that Nvidia's stock price is bound to be affected in the short term due to the personal scandals of key figures compounded by the uncertainty of independent investigations.
Rumor has it that Alphabet (GOOGL.US) plans to issue Hong Kong dollar and Singapore dollar bonds for the first time. As concerns about AI financing intensify, investor confidence may be tested. According to people familiar with the matter, Alphabet has recently discussed the possibility of issuing Hong Kong dollar and Singapore dollar bonds for the first time. Alphabet probably communicated with banks and investors about bond issuance as early as this month. According to people familiar with the matter, the company plans to issue HKD bonds worth 1 billion to 1.5 billion US dollars, and Singapore dollar bonds worth about 1.5 billion US dollars. The above sources added that the funds raised will be used for general corporate purposes. As the construction of data centers, AI chips and cloud computing infrastructure continues to accelerate, technology giants' demand for capital continues to increase, and the bond market has become an important channel for them to raise long-term capital. However, at a time when the global market is fluctuating due to the sell-off of AI-related sectors, this deal will test the willingness of Asian investors to subscribe.
Berkshire Hathaway (BRK.A.US)'s Q3 operating profit was US$12.71 billion. The scale of repurchases in a single quarter was the highest in the year, and cash reserves rose to an all-time peak. Berkshire Hathaway's third-quarter revenue was US$105.647 billion, or US$94.972 billion in the same period last year; operating profit was US$12.71 billion, down 5.8% year on year; net profit attributable to shareholders was US$22.112 billion, compared to US$30.796 billion in the same period last year; net income per Class A equivalent common share was US$15,502; and net investment income for the third quarter was US$9.407 billion, compared to US$17.311 billion for the same period last year. The repurchase of its own shares in the third quarter was about 9.6 billion US dollars, the highest in a single quarter of the year. The cumulative number of repurchases in the first nine months reached 14.4 billion US dollars. As of September 30, the company's cash and equivalents rose to US$377.4 billion, a further increase from the previous quarter, once again setting a new historical record.
Barrick Mining (B.US) had mixed results in Q3, with gold price dividends coexisting with cost pressures. Financial reports show that Barrick Mining's Q3 revenue was US$5,073 billion, up 22% year on year and down 4% month on month; net profit attributable to shareholders was US$1,317 million, up 1% year on year, with earnings per share of 0.80 US dollars; adjusted earnings per share of $0.82, up 41% year on year. The market had previously anticipated adjusted earnings of $0.79 per share and revenue of US$5.13 billion. The increase in the price of gold was the main reason for the increase in revenue: the price of gold reached 4,243 US dollars/ounce during the quarter, an increase of 23% over the previous year. However, the cost increased at the same time. The total cost of gold maintenance (AISC) rose to 1,911 US dollars/ounce, up 24% year over year; total cash cost was 1,386 US dollars/ounce, up 22%. The company claims that the cost pressure comes from a decline in selected grades, an increase in equity due to a rise in gold prices, a rise in the price of diesel and consumables, and the appreciation of some local currencies.
Key economic data and event forecasts
23:00 Beijing time 2027 FOMC voting committee and Chicago Federal Reserve Chairman Goulsby delivered a speech
At 00:00 Beijing time the next day, the US New York Federal Reserve's 1-year/3-year inflation forecast for October
Beijing time at 01:15 the next day, 2027 FOMC voting committee and Richmond Federal Reserve Chairman Barkin delivered a speech
Performance Forecast
Tuesday morning: Occidental Petroleum (OXY.US), Take-Two (TTWO.US), Skydance (SKYD.US), Roket Lab (RKLB.US), AST SpaceMobile (ASTS.US), MARA Holdings (MARA.US)
Tuesday pre-market: Honda (HMC.US), Vodafone (VOD.US), Sea (SE.US), Onrun (ONON.US)