


EN
Is EVERTEC (EVTC) Undervalued On Raised Guidance And Cheaper Credit Lines?
EVERTEC (EVTC) has given investors fresh information to work with after raising its full year 2026 guidance, securing cheaper and larger credit lines, and reaffirming its regular dividend.
The raised guidance, cheaper credit facilities and confirmed dividend have arrived alongside a clear rebound in EVERTEC’s share price, with a 30 day share price return of 13.19% and a year to date share price gain of 16.98% indicating momentum has picked up recently. The 1 year total shareholder return of 24.76% contrasts with a weaker 5 year total shareholder return of 21.22% and a modest 3 year outcome of 2.74%, suggesting the market has only relatively recently started to reassess the company’s prospects.
Scan how other hand picked payment and fintech processors with strong balance sheets compare to EVERTEC by reviewing the list of solid balance sheet and fundamentals (25 results) in the same session.
EVERTEC now trades at a modest discount to both analyst targets and one intrinsic value estimate after this sharp move. Is that a genuine margin of safety, or a warning the market still doubts the recent guidance update?
Most Popular Narrative: 5.8% Undervalued
EVERTEC’s analyst consensus Narrative on Simply Wall St pegs fair value at $35.60, a touch above the last close at $33.55. This frames the recent rally as only partly closing the gap implied by those long term forecasts and a discount rate of 8.63%.
The current valuation, along with external estimates that place EVERTEC shares above recent market pricing, indicates that some investors appear to be treating the stock as undervalued in the context of the recent revenue and EPS guidance updates.
The view now emphasizes AI and digital asset projects that are expected to feed into guidance from 2027 and link directly to revenue and net margin outcomes.
See why 2 investors see EVERTEC as 6% undervalued.
Result: Fair Value of $35.60 (UNDERVALUED)
Still, EVERTEC’s reliance on large clients and the recent cybersecurity incident could quickly undermine that undervalued story if either issue escalates from this point.
Find out about the key risks to this EVERTEC narrative.
Another View: EVERTEC Through The P/E Lens
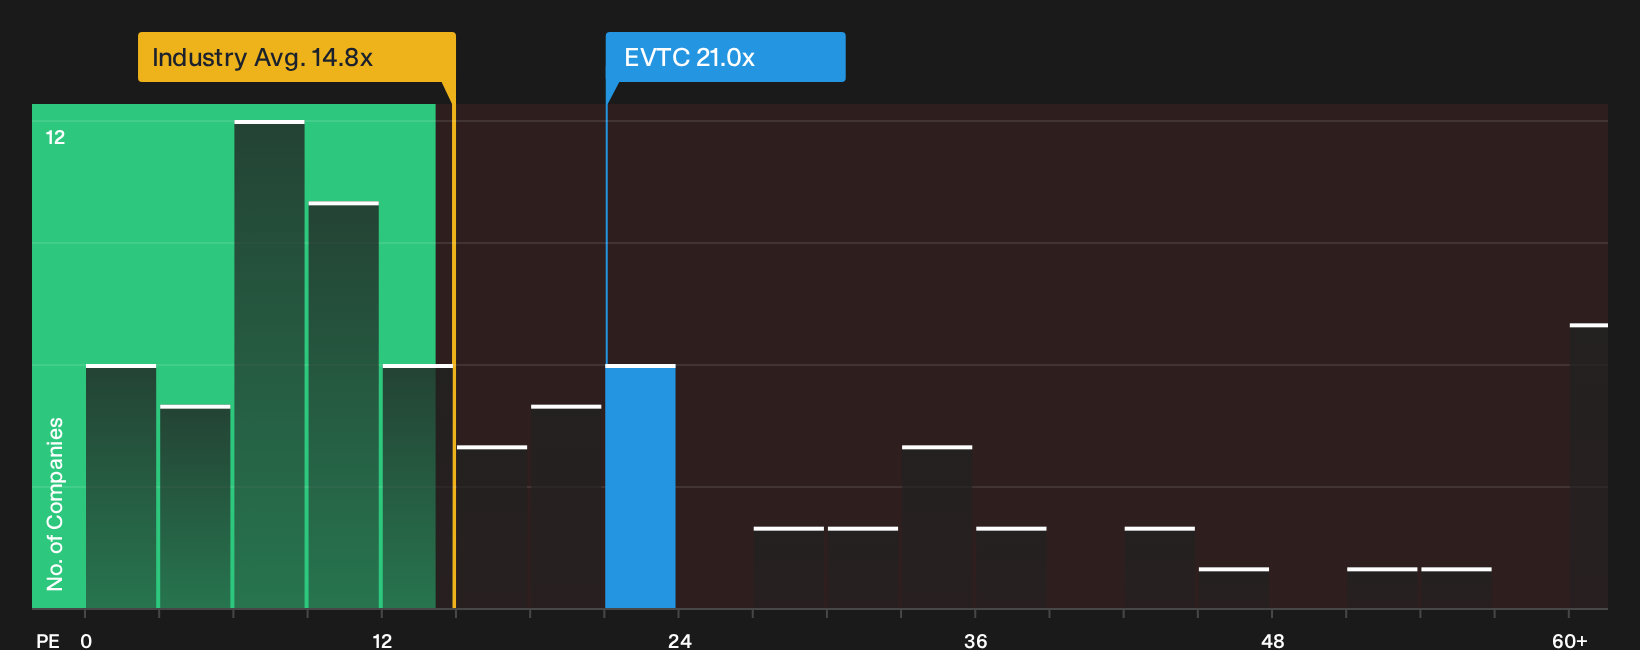
The SWS DCF model points to EVERTEC shares trading about 10.1% below an estimated future cash flow value of $37.32, which supports the undervalued narrative. The P/E picture tells a different story. At 21x earnings, EVTC trades richer than the US Diversified Financial industry at 14.8x, peers at 17.7x, and even its own fair ratio of 16.9x. This suggests there may be less room for error if earnings or guidance stumble from here.
That spread raises a blunt question for anyone looking at EVTC today. Are you more comfortable trusting the cash flow model, or does the premium P/E and gap to the fair ratio make you treat this as a higher risk entry point, even with the recent upgrade to guidance?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around EVERTEC’s valuation and guidance do not have to dictate your view. Act while the information is fresh and evaluate both the bullish and cautious cases in relation to the 2 key rewards and 3 important warning signs.
Looking for more EVERTEC sized investment ideas?
If you want a stronger watchlist, do not stop at EVERTEC. Use the Simply Wall St Screener to surface fresh ideas while this update is still front of mind.
- Spot potential value trades early by scanning the 40 high quality undervalued stocks that pair quality fundamentals with pricing that may still lag underlying business strength.
- Prioritize capital protection by reviewing the 31 resilient stocks with low risk scores that combine resilient balance sheets with more measured volatility profiles.
- Hunt for under-the-radar opportunities by checking the 19 high quality undiscovered gems that show solid fundamentals before wider attention arrives.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com