


EN
Mirion Technologies (MIR) Could Be 24% Undervalued After Q3 Earnings And Guidance Lift
Mirion Technologies (MIR) is back in focus after its third quarter earnings release, with revenue of US$277.8 million and net income of US$7.4 million drawing attention to the stock.
Mirion Technologies has seen a sharp 17.68% 90 day share price return and an 8.12% 1 month share price gain. However, the stock is still down 24.59% year to date on a share price basis, with the 1 year total shareholder return declining 33.79% but the 3 year total shareholder return rising 119.15%. This suggests recent momentum has picked up as investors react to the stronger third quarter results and raised full year revenue guidance.
Surf 17 nuclear energy infrastructure stocks to see other radiation and nuclear infrastructure plays that could be reacting to earnings momentum and upgraded guidance in a similar way to Mirion Technologies.Mirion Technologies has already bounced hard off the lows, yet the share price is still behind its three year return profile. The key issue now is whether valuation leaves meaningful upside on the table or if most of the easy gains are already gone.
Most Popular Narrative: 24% Undervalued
Mirion Technologies closed at $17.97, while the analyst consensus Narrative on Simply Wall St places fair value at about $23.55, implying a sizable valuation gap that hinges on how far its end markets and margins can stretch over time.
The accelerating global shift toward expanded nuclear power generation, coupled with rising capital budgets for modernization, life extensions, and increased capacity of the existing reactor fleet, is likely to drive sustained double-digit organic revenue growth and expand Mirion's higher-margin installed base business in coming years.
Strong momentum in advanced nuclear projects, including utility-scale new builds and rapid activity in the small modular reactor (SMR) market, has materially broadened Mirion's pipeline of large, multi-year opportunities, creating potential for significant step-changes in future order intake, backlog, and top-line revenue.
See why 8 investors see Mirion Technologies as 24% undervalued.
Result: Fair Value of $23.55 (UNDERVALUED)
Still, dependence on nuclear projects and acquisition-led expansion means that policy shifts, decommissioning trends, or weak integrations could quickly challenge the Mirion Technologies upside story.
Find out about the key risks to this Mirion Technologies narrative.
Another View on Mirion Technologies Valuation
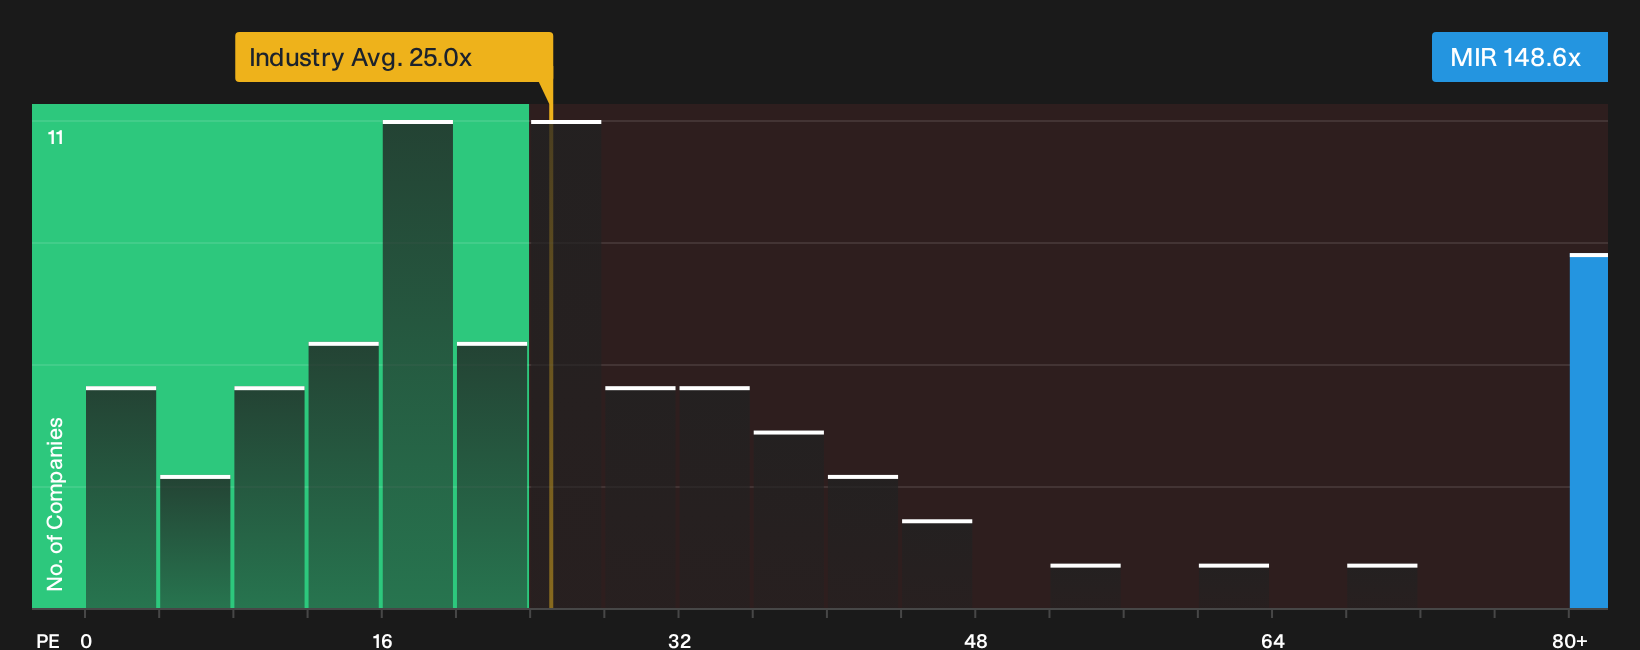
The analyst fair value for Mirion Technologies suggests upside, yet the current P/E ratio of 148.6x tells a different story. That multiple is far above the US Electronic industry at 25x and the 39.9x peer average, and it also exceeds the 43.9x fair ratio that our models indicate the market could move toward. If sentiment cools, how much room is there for the valuation to compress before fundamentals catch up?
For a closer look at how this pricing gap stacks up against sector and peer benchmarks, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Mirion Technologies so far, and you can see why opinions split. Act while sentiment is live and weigh those 4 key rewards and 2 important warning signs
Looking for more Mirion Technologies style investment ideas?
Do not stop at Mirion Technologies. Fresh ideas often appear where strong balance sheets, resilient cash flows, and overlooked quality quietly line up before the crowd notices.
- Target resilient potential by filtering for stocks that combine healthier finances with lower risk scores through the 31 resilient stocks with low risk scores.
- Zero in on companies the market may be mispricing right now by scanning the 40 high quality undervalued stocks.
- Hunt for quality stories that receive less attention but have solid fundamentals using the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com