


EN
Mastercard (MA) Could Be 13% Undervalued On Strong Q3 Results And Payments Expansion
Mastercard (MA) just posted third quarter results with US$9,807 million in sales and US$4,628 million in net income, while also backing Samsung Pay in Morocco and expanding B2B payment capabilities with Tech Mahindra.
Recent headlines around Mastercard, from the Samsung Pay launch in Morocco to the Tech Mahindra B2B payments tie up and ongoing share buybacks, sit against a share price of US$652.70 that has climbed with a 30 day share price return of 10.79% and a 90 day gain of 16.25%.
That short term momentum builds on longer term gains, with total shareholder return of 18.80% over one year and 86.09% across five years. This suggests recent earnings and product moves are being read as supportive for both growth potential and risk profile.
Scan beyond Mastercard and evaluate other payment and fintech players that are showing strong earnings momentum and digital adoption with the hand picked 19 high quality undiscovered gems.
Mastercard now trades at US$652.70, with analyst targets and intrinsic estimates indicating a higher value. Is that recent surge already pricing in the story, or is the fair value line still out in front?
Most Popular Narrative: 13% Undervalued
On the Simply Wall St Community fair value line, Mastercard is tagged at $750 against a last close of $652.70, which points to a meaningful valuation gap according to that framework and sets up a very clear thesis to test.
According to Investingwilly, an investor in the Simply Wall St Community who wrote the narrative, the appeal rests less on a single quarter and more on how the underlying engine works and why sentiment has not kept pace with it.
Mastercard runs the rails connecting banks, merchants, and the billions of cards carrying its brand. It never lends money and never holds credit risk on its books; it just takes a small cut every time a transaction crosses its network. That is the whole business model. It is a high-margin, low-capital-intensity structure, with performance linked to the gradual global shift away from cash.
See why 153 investors see Mastercard as 13% undervalued.
Result: Fair Value of $750 (UNDERVALUED)
Still, Mastercard faces real swing factors, including regulatory pressure on fees and the faster adoption of competing payment rails that could compress pricing power.
Find out about the key risks to this Mastercard narrative.
Another Take On Mastercard's Valuation
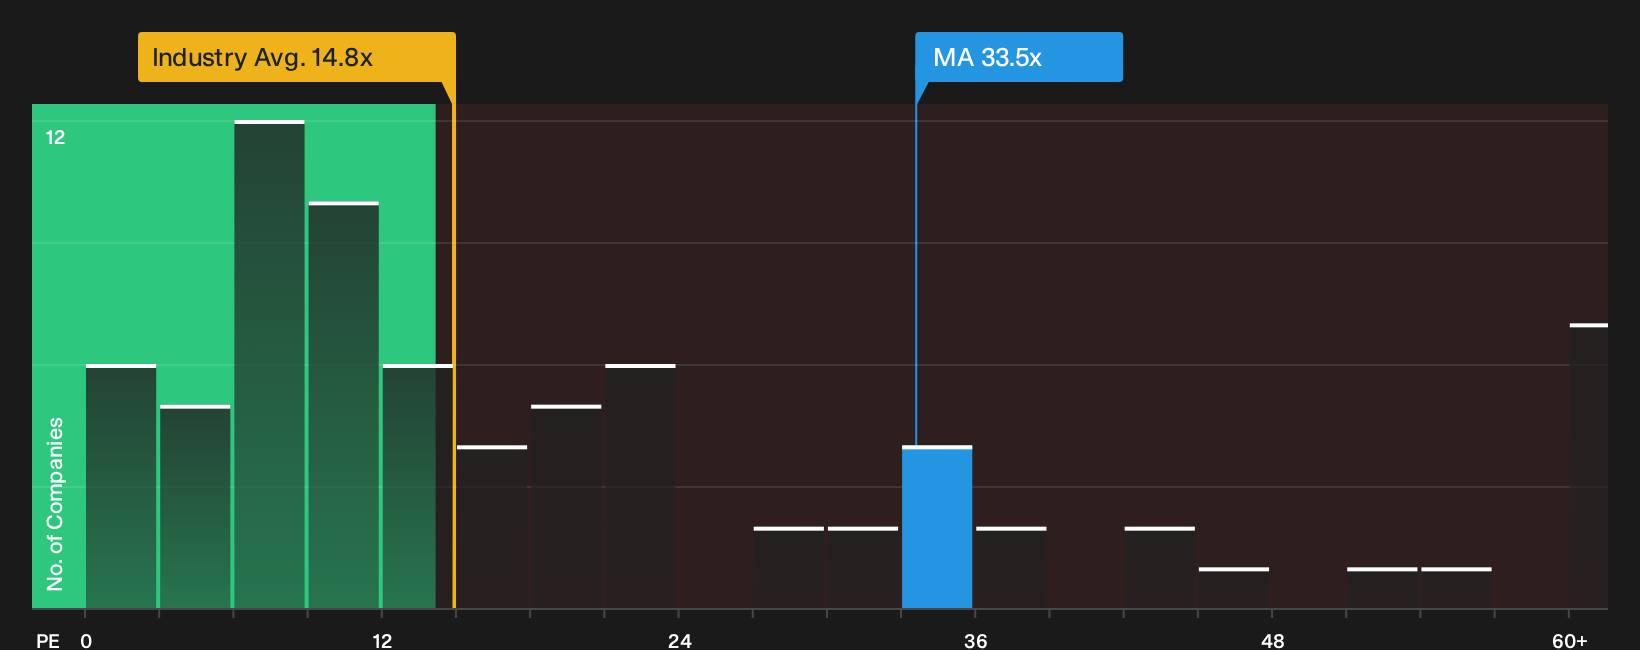
The SWS fair ratio based on P/E paints a less generous picture for Mastercard. The stock trades at 33.5x earnings, against a US Diversified Financial industry average of 14.8x and a fair ratio estimate of 21.5x. That gap signals a valuation premium. The real question is whether investors feel the quality justifies paying up.
For a closer look at how this earnings multiple stacks up against peers and that fair ratio, check the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around Mastercard leaves you uncertain, use the numbers to guide you and act quickly to test your own thesis using the full breakdown of 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Mastercard?
Do not stop at one opportunity when the market is full of potential matches for your style, time horizon and appetite for risk.
- Target higher income potential by focusing on dependable cash returns through the 7 dividend fortresses.
- Zero in on sturdier balance sheets and cleaner fundamentals with the list of solid balance sheet and fundamentals (25 results).
- Spot early stage potential before it hits the mainstream using the 10 elite penny stocks with strong financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com