


EN
Did Health Benefits Checkout Just Shift Costco's (COST) Investment Narrative?
- In late October 2026, NationsBenefits announced a nationwide retail integration that links its Flex Card to Costco Wholesale, allowing health plan members to redeem eligible over the counter, healthy food, and wellness benefits in real time at checkout across more than 600 U.S. warehouses.
- This integration plugs Costco directly into health plan benefit flows, potentially deepening pharmacy and wellness spending inside the warehouse and reinforcing the retailer’s role as a recurring destination for everyday healthcare needs rather than only for bulk shopping trips.
- The focus now shifts to how Costco Wholesale’s investment narrative could be shaped by this NationsBenefits health benefits integration.
Costco Wholesale Investment Narrative Recap
To own Costco Wholesale, you need to be comfortable with a high P/E multiple backed by steady warehouse economics, strong membership income and disciplined cost control. According to LunaRodas, an investor in the Simply Wall St Community, the key near term swing factor is how membership trends and warehouse traffic hold up as growth in paid members has been normalising. The recent NationsBenefits integration and the latest sales call do not appear to materially change that near term focus.
The biggest operating risk right now is paying a rich valuation multiple if earnings growth, forecast at 8.52% per year, slows or execution on new services disappoints. Execution around digital, delivery and healthcare adjacent services matters, although the Vallejo relocation and broader warehouse openings show Costco Wholesale is still leaning into physical clubs. In the short term, the path of same store sales and membership renewals remains the main catalyst to watch.
The NationsBenefits Flex Card rollout is the announcement that ties closest to Costco Wholesale’s current story. It plugs healthcare related spend directly into checkout across more than 600 U.S. warehouses, which sits neatly alongside pharmacy, optical and hearing services already inside the box. For investors tracking catalysts, the real question is how much extra frequency and basket size this channel can support over time.
LunaRodas argues that management’s pricing moves and tariff refund reinvestments are already aimed at reinforcing the value proposition. The NationsBenefits link sits beside those efforts as another operational lever, but it introduces execution risk around technology integration and partner relationships. If it runs smoothly and members actually use it, this healthcare bridge could quietly support Costco Wholesale’s membership stickiness without changing the core warehouse model.
On LunaRodas’ math, Costco Wholesale reaches a fair value of $861.94 mainly because the tariff refund program is already translating into concrete price investment, volume response and margin support, while membership growth, AI search efforts and the NationsBenefits tie-in provide the operating story with enough clarity to underwrite that figure.
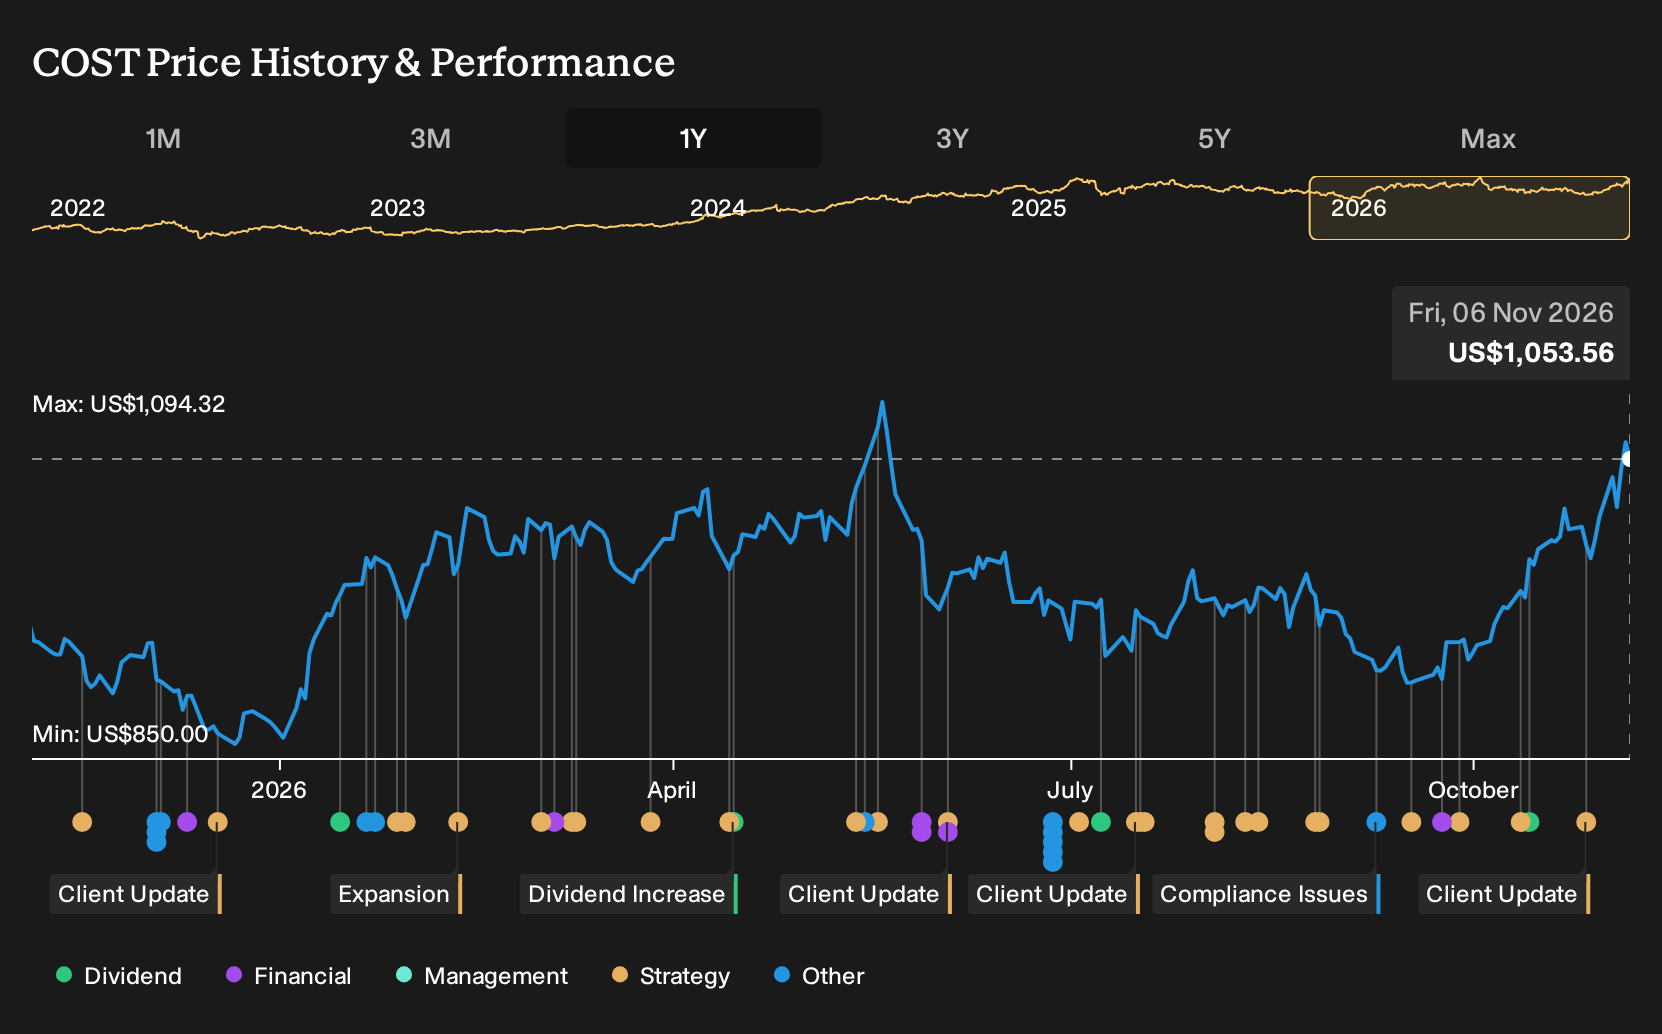
Uncover how Costco Wholesale's fair value indicates an 18% potential downside to its current price, suggesting a valuation premium that leaves little room for error.
Exploring Other Perspectives
Some of the most optimistic analysts frame Costco Wholesale very differently, arguing that the key catalyst is earnings power rather than membership “normalisation.” Before this NationsBenefits news, the bullish camp was already modeling revenue climbing to about US$392b and earnings of US$12.8b by 2029. You can treat those pre news assumptions as one possible storyline and compare them with more cautious views before deciding which version of Costco’s future feels more convincing to you.
Explore 12 other Costco Wholesale fair value estimates, including one that suggests potential upside of up to 21% from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Costco Wholesale research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Costco Wholesale. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Costco Wholesale's overall financial health at a glance.
Looking for more Costco Wholesale style ideas?
If the Costco Wholesale story resonates but you want a wider set of options, it can help to scan for other businesses with the kind of balance sheets, income profiles, or potential mispricings that fit your own playbook.
- If you care most about a margin of safety, start by reviewing a 40 high quality undervalued stocks that filters for companies where quality fundamentals and current pricing appear out of sync.
- For readers who put resilience first, consider a 31 resilient stocks with low risk scores that surfaces businesses with stronger financial health and lower overall risk scores.
- When the focus is on sturdier finances and cleaner balance sheets, scan a list of solid balance sheet and fundamentals (25 results) to see which stocks might complement a Costco Wholesale style holding.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com