


EN
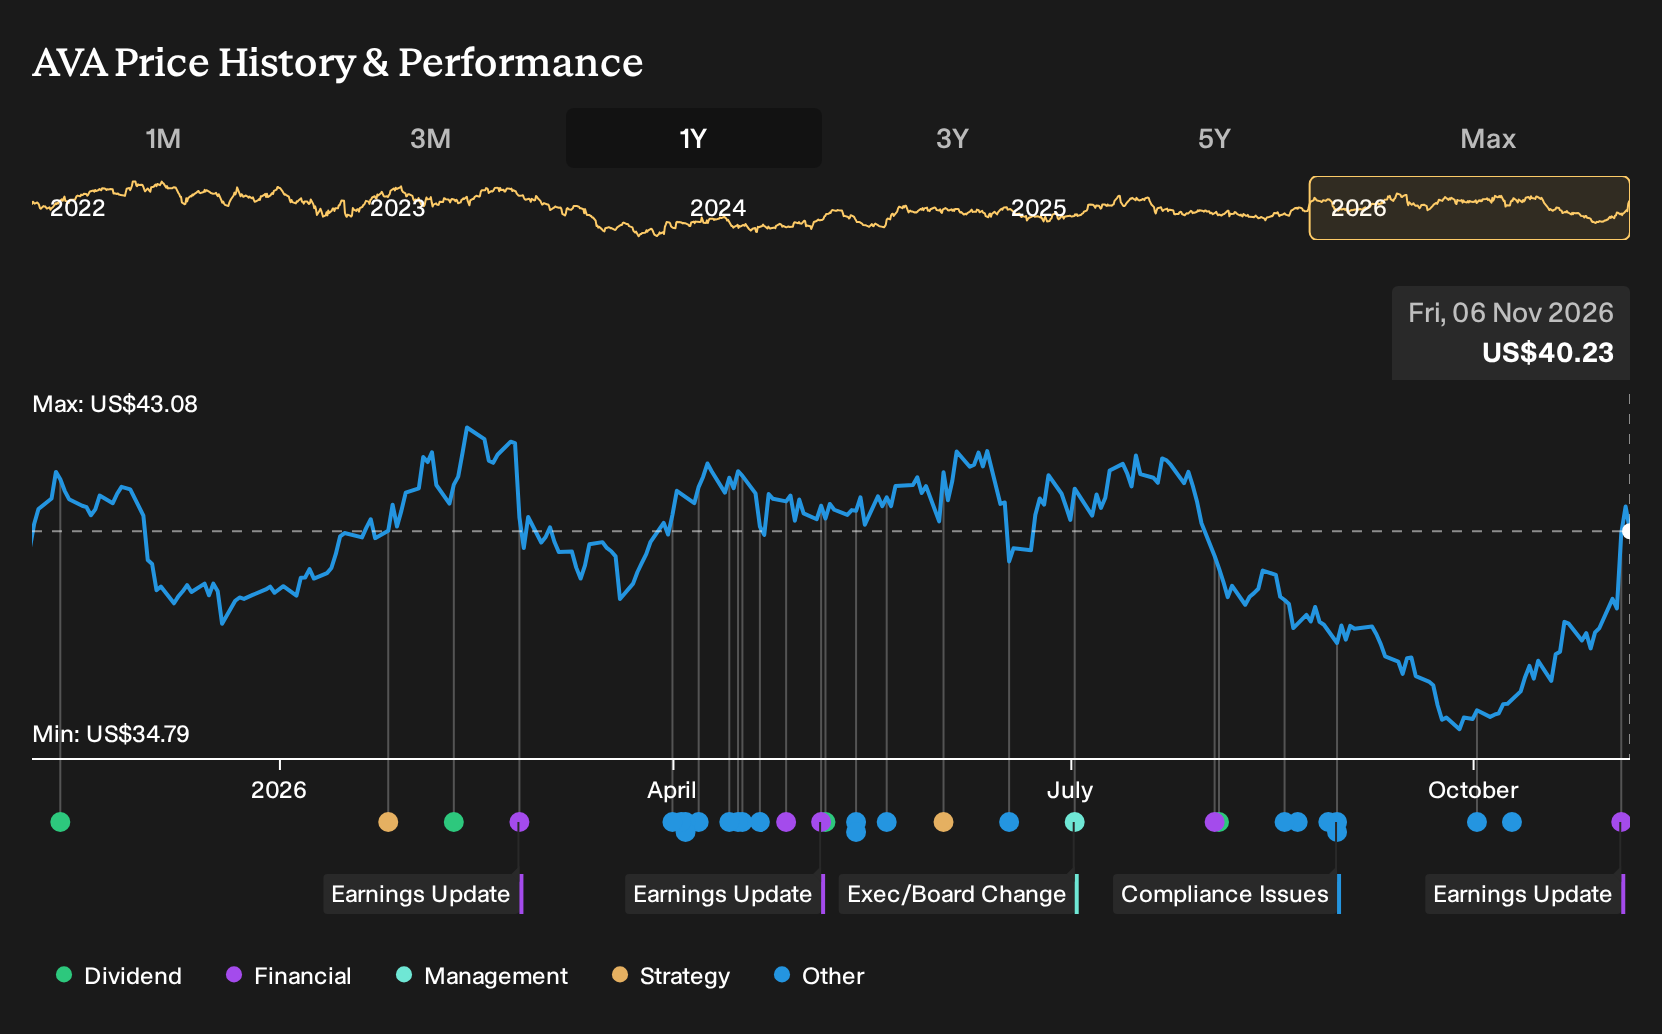
Earnings Beat Could Be A Key Moment For Avista Stock (AVA)
- Avista reported third quarter 2026 revenue of US$421 million and net income of US$49 million, with higher basic and diluted earnings per share from continuing operations than in the same period a year earlier. The company also reported stronger nine‑month figures compared with the prior year.
- The utility reaffirmed its 2026 non‑GAAP earnings guidance, outlined a US$3.6 billion capital plan for 2027 to 2031, and moved to take a 10% stake in the North Plains Connector transmission project, highlighting management’s focus on long‑duration grid investment and participation in large projects.
- Next, the focus will be on how Avista's earnings profile interacts with its existing long‑term, capital‑intensive investment narrative.
Scan beyond Avista and line up other regulated utilities committing serious capital to long term grid upgrades with the hand picked 42 power grid technology and infrastructure stocks.
Avista Investment Narrative Recap
For Avista, the investment case hinges on a regulated utility that is trying to match a heavy capital plan with a stable earnings profile. The analyst consensus narrative on Simply Wall St focuses on constructive regulation, wildfire mitigation frameworks and large load opportunities. The latest quarter showed higher earnings than a year earlier, which supports that story but does not change it.
The near-term swing factor now sits with regulation and power costs rather than quarterly revenue volatility. Progress on the Washington general rate case and the energy recovery mechanism will likely matter most for how earnings track guidance. The key risk remains wildfire exposure and any additional grid hardening spend that follows.
The reaffirmed 2026 non-GAAP utility earnings guidance is most closely linked to this update. Management essentially told investors that, despite power cost volatility and wildfire spending needs, the current year profit framework still holds. That message aligns with the recent earnings numbers, which showed higher net income and earnings per share than in the comparable periods.
For potential catalysts, the planned US$3.6 billion capital program for 2027 to 2031 and the prospective 10% interest in the North Plains Connector transmission project provide Avista with a long runway of regulated investment. Execution, cost control and future rate decisions around these projects will influence how much of that spending turns into allowed returns and how much pressure falls on funding and customer bills.
Avista Forecasts and Implied Earnings Path
Avista's narrative projects US$2.2 billion revenue and US$261.9 million earnings by 2029. This is based on analysts assuming 4.4% yearly revenue growth and implies an earnings increase of about US$34.9 million from current earnings of US$227.0 million.
Uncover why Avista's fair value indicates a 3% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One bearish twist to watch comes from that large data center delay. The most pessimistic analysts assumed only 1.4% annual revenue growth and about US$2.0b revenue with US$255.3m earnings by 2029, versus the baseline US$2.2b and US$261.9m view. Their cautious stance predates this Avista earnings beat, so expectations could shift from here.
Explore another Avista fair value estimate, including one that suggests as much as 11% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Avista research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Avista. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Avista's overall financial health at a glance.
Looking for more Avista style investment ideas?
If the Avista story has you thinking about how to balance earnings resilience with balance sheet strength and risk, the Simply Wall St Screener can help you line up other listed utilities and peers that fit your checklist in minutes.
- If capital preservation comes first for you, focus on businesses with resilient financial profiles by scanning a 31 resilient stocks with low risk scores that already clear strict risk filters.
- For those chasing value, concentrate on companies where quality metrics and pricing still leave some room by reviewing a carefully curated 40 high quality undervalued stocks that match that mindset.
- Income focused investors can zero in on cash return potential by starting with a 7 dividend fortresses that screen for higher yields supported by fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com