


EN
Diodes (DIOD) Stock May Still Sit Below Fair Value Following Record Q3 Revenue
Diodes Incorporated has delivered a sharp move over the past year, and the question now is whether its current share price lines up with what its earnings can reasonably support. After a stretch of strong results, investors are weighing how much of that profit story is already built into the stock.
- Over the past 12 months the stock is up 66.0%, which puts real pressure on the earnings profile to keep justifying a higher valuation bar.
- Recent record revenue and stronger profitability, helped by exposure to automotive, industrial and AI related demand, may support a case for higher earnings power than in previous years.
- There is a second opinion on Diodes worth weighing. See what analysts think Diodes's shares could be worth.
The issue now is whether Diodes' current price fairly reflects the earnings it is generating today and what those earnings suggest about value over time.
If you are weighing whether Diodes' recent earnings justify its run, it can help to cross check your thinking against a focused list of 40 high quality undervalued stocks.
Is Diodes Still Cheap on Earnings?
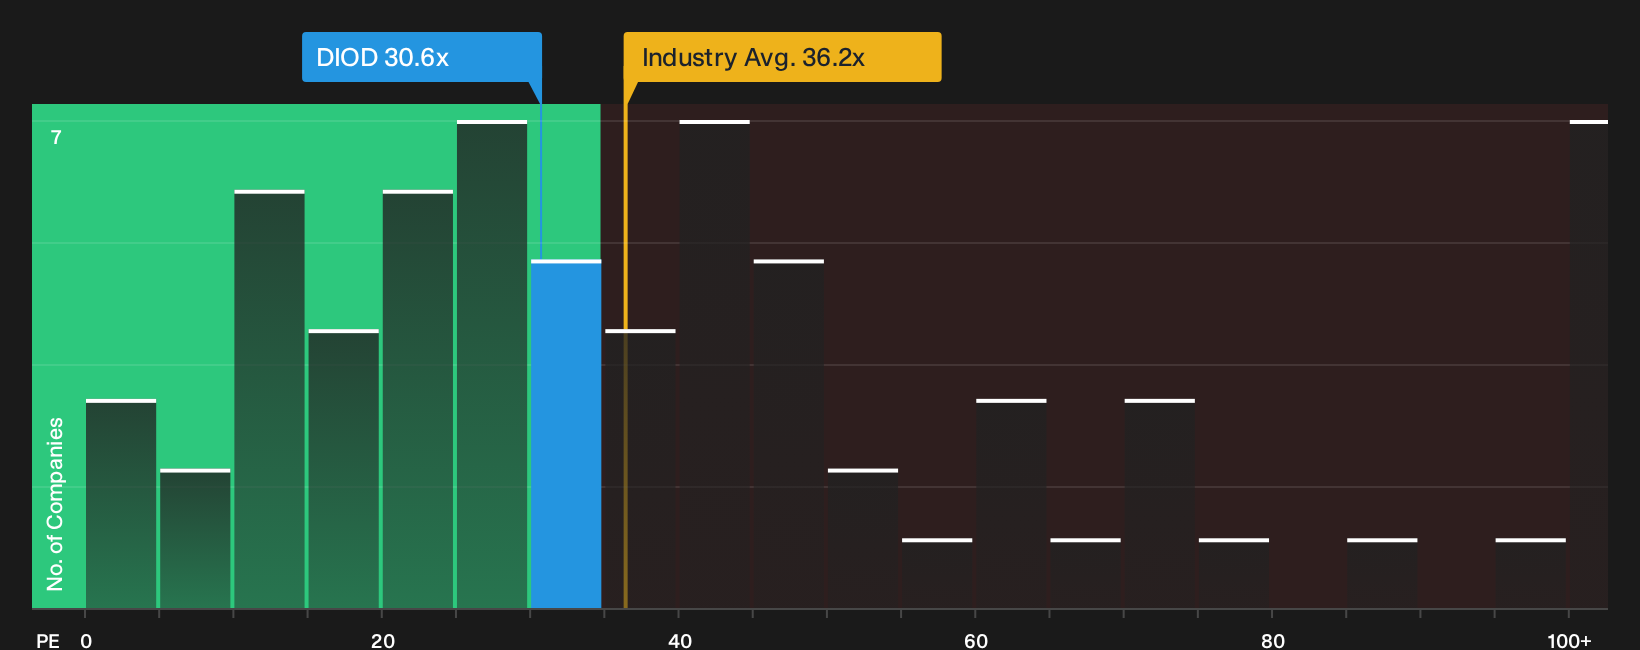
The P/E ratio suits Diodes because earnings now drive most of the story investors focus on. On this lens, the stock trades on roughly 30.6x earnings, which is below both the Semiconductor sector average of about 36.2x and a peer group closer to 63.5x. That puts Diodes on a lower earnings multiple than many comparable chip makers, even after a strong share price move.
Because the current P/E sits below what a tailored model suggests would be typical for Diodes given its profile, the shares screen as undervalued on this metric. Record Q3 2026 results and stronger profitability, helped by automotive, industrial and AI linked demand, have not fully closed that gap. As a result, the market is still pricing the business at a discount to where this earnings based framework would place it. Explore the numbers behind Diodes's P/E valuation.
The Diodes Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where this P/E puzzle leaves off and explain which future paths for Diodes' growth, margins and earnings would need to occur for the stock to appear meaningfully undervalued or overvalued compared with today's price. Each narrative links its figures to a clear view on how Diodes' expansion potential, profitability and risk profile might change, providing a reference point you can revisit as new information becomes available.
One of the top narratives on Diodes: 30% undervalued
This Narrative is the bearish analyst Narrative on Simply Wall St, built on the most pessimistic analyst price target and forecasts, not one person's view.
"Geopolitical tensions, regulatory shifts, and reliance on key customers heighten risks to supply chain stability, revenue growth, and earnings consistency…"
Discover why this Narrative puts Diodes at 30% undervalued.
The share price is only one piece of the Diodes puzzle
Before making a call on Diodes, it is worth checking who is actually running the business, how their incentives are set up, and whether that lines up with shareholder outcomes. See who runs Diodes and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com