


EN
WEX (WEX), What Is Behind The Fresh Attention Around It?
Why WEX’s latest earnings matter for shareholders
WEX (WEX) just turned in third quarter 2026 results that showed higher revenue and net income than a year earlier, raised its full year sales outlook, and confirmed fresh guidance for the coming quarter.
The latest earnings beat, the raised 2026 revenue outlook and the Euclid AI partnership arrive after a mixed trading stretch, with WEX’s share price up 22.8% year to date, down 3.6% over three months, and still delivering a 24.2% one-year total shareholder return.
Scan how WEX stacks up against other payment and fintech operators by sifting through a curated set of 19 high quality undiscovered gems that share strong fundamentals but still fly under most radars.
After a strong year to date, fresh guidance, and a completed buyback, the question now is whether WEX still offers enough upside to justify the risks at around $182 a share.
Most Popular Narrative: 10% Undervalued
At a last close of $182.22 against a fair value of $202.09 from the analyst consensus Narrative on Simply Wall St, WEX is framed as undervalued on a discounted cash flow style view that blends earnings, margin and revenue forecasts with an 8.8% discount rate.
The main thing that has to go right is that WEX continues to execute on AI led efficiency programs, pricing initiatives in Mobility and mid teens direct AP volume growth, while maintaining the funding benefits of WEX Bank.
The shift in capital allocation toward share repurchases is supported by leverage at 2.9x within the 2.5 to 3x target range, roughly US$696m to 700m of adjusted free cash flow over the last 12 months and a US$1b authorization.
See why 8 investors see WEX as 10% undervalued.
Result: Fair Value of $202.09 (UNDERVALUED)
Still, the WEX narrative can break if electric vehicle adoption undercuts fuel card activity, or if rising competition in corporate payments squeezes transaction economics.
Find out about the key risks to this WEX narrative.
Another way to look at WEX’s valuation
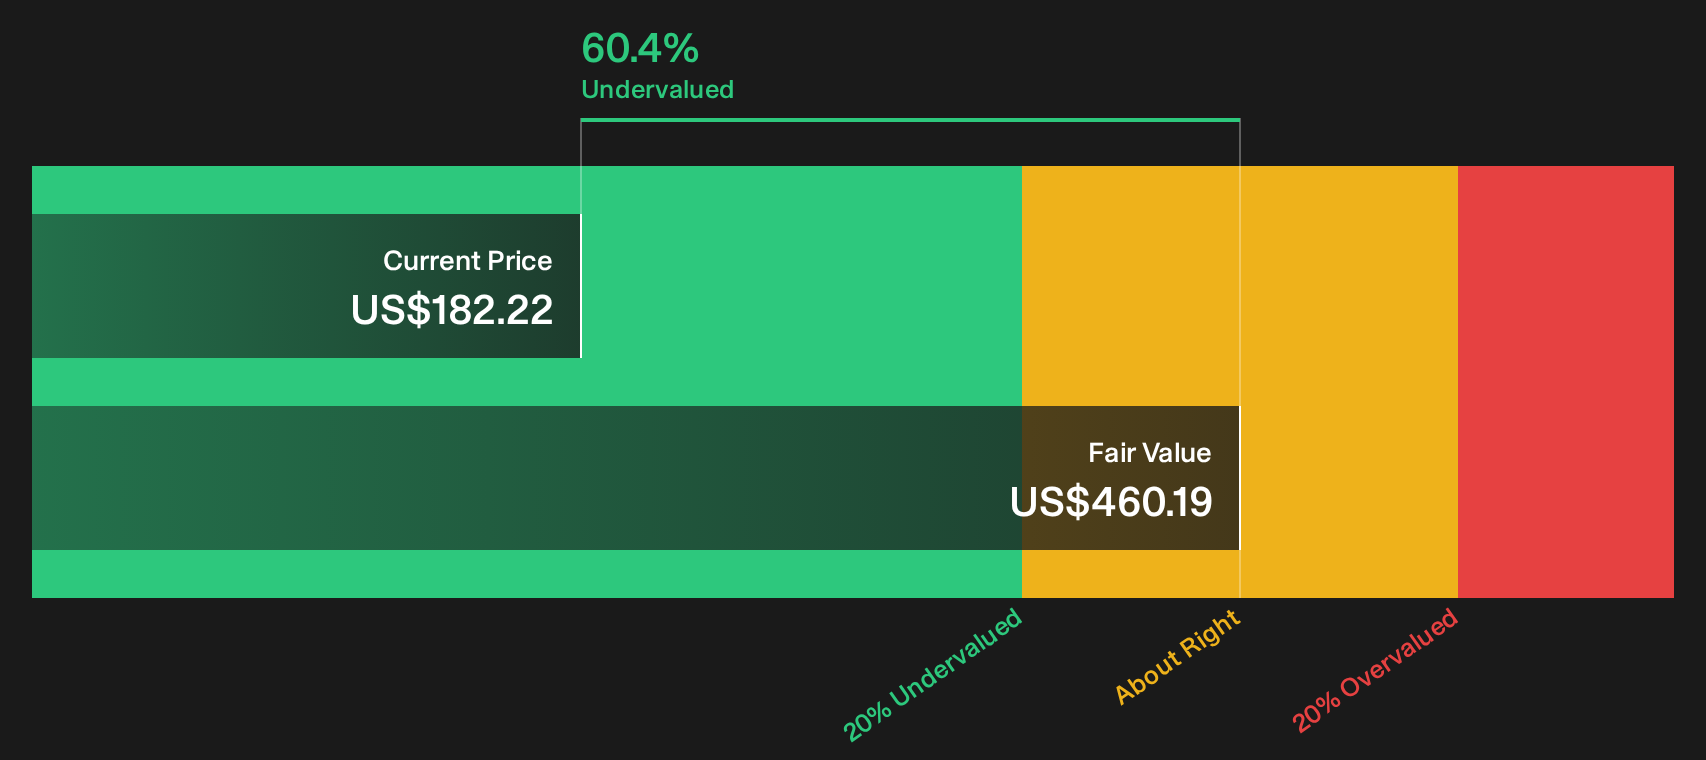
The Simply Wall St DCF model presents a very different picture for WEX. In that view, the shares at $182.22 sit around 60% below an estimated future cash flow value of $460.19. This points to a much larger cushion than the analyst fair value of $202.09 suggests. Which lens do you give more weight to when the gap is this wide?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If this mix of upside and concern around WEX leaves you on the fence, move quickly, test the numbers yourself and pressure test the story from both angles. To balance the potential opportunities against the issues investors are watching, start with 3 key rewards and 2 important warning signs.
Looking for more ideas beyond WEX?
If WEX has your attention but you want a stronger bench of possibilities, use the Simply Wall St screener to surface fresh, data backed ideas before others do.
- Target reliable compounding potential by focusing on companies that combine quality and value through the 40 high quality undervalued stocks.
- Prioritize sleep at night holdings by zeroing in on companies with healthier finances using the list of solid balance sheet and fundamentals (25 results).
- Hunt for resilient performers that aim to limit downside by concentrating on the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com