


EN
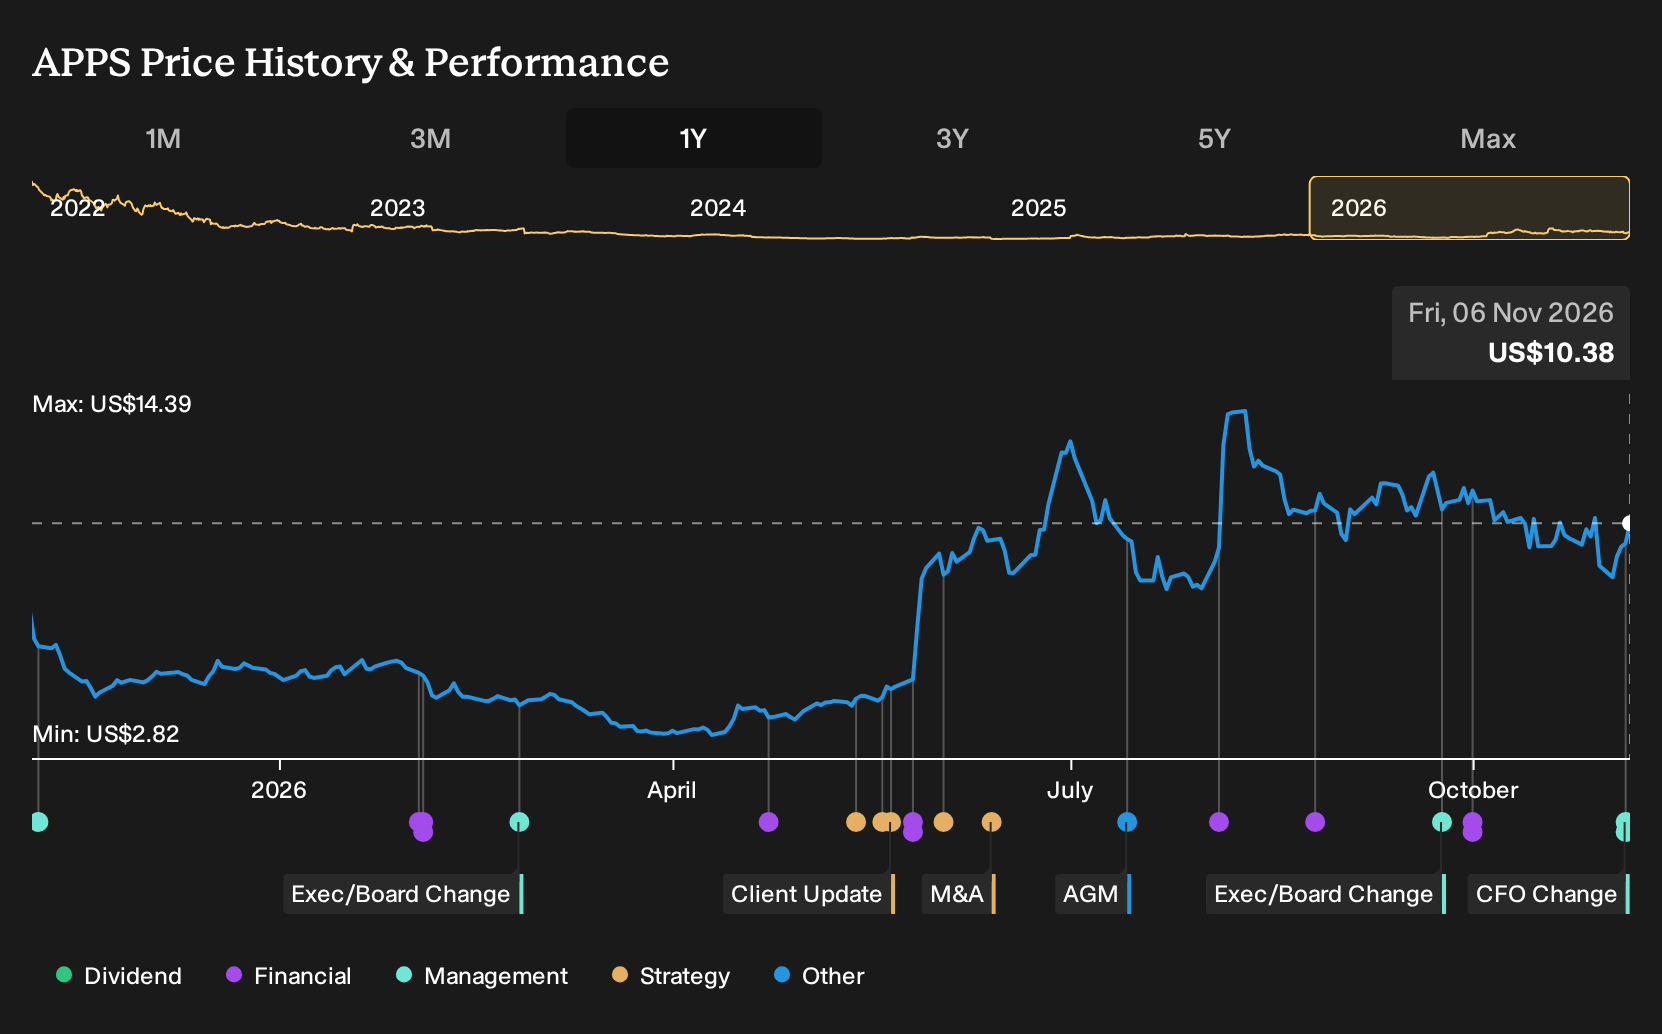
Digital Turbine Holders Are Up 75% And Here Is What They Saw
If you had backed Digital Turbine when analysts were split between upside from open app markets and threats from privacy rules and debt, the outcome would have looked very different to those early debates. Holding Digital Turbine over the past year would have returned 75.3%, including dividends. With revenue and margins now moving in a more positive direction, what exactly in the original thesis was visible, and what only became clear later?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The easy part of this move is behind Digital Turbine. Zero in on 40 high quality undervalued stocks for companies trading below our estimates.
The Argument You Would Have Been Weighing Up On Digital Turbine
The shares cost US$6.26 at the start of the period, and anyone looking at Digital Turbine then had two live stories to compare.
The bullish narrative saw a fair value of US$6.75, built on revenue growing 9.0% a year and margins eventually reaching 13.1% as open app markets broadened.
The bearish view put fair value at US$5.50, assuming 10.0% yearly revenue growth but warning that strict privacy rules and a heavy debt load above US$400 million could still hamper progress.
What The Results Changed For Digital Turbine
The launch of Launchpad and the Orange distribution deal backed the bullish view that open app markets could widen Digital Turbine’s reach. Reported figures showed revenue at US$165.983 million in Q1 2027 versus US$130.926 million a year earlier, while the firm still reported a loss and net margin stayed negative at -6.8%. The evidence cut both ways.
The hinge assumption here was that broader distribution and AI tools would translate into healthier economics. For a different stock, you would track segment revenue, contracts with large partners, and whether net margin is actually moving towards the thesis margin target.
What Digital Turbine’s Price Suggests After The Run
Digital Turbine now trades at US$10.38. The analyst consensus Narrative on Simply Wall St argues that its Fair Value sits above that level, anchored in a view that AI tools, alternative app distribution, and international reach can support stronger economics over time.
On that reading, today’s buyer is effectively judging whether current pricing fully reflects sustained execution on DTiQ, IgniteGraph, SingleTap, and international On-Device Solutions.
"Analysts expect Digital Turbine to continue focusing on AI-driven monetization, international device reach, and alternative app distribution, with the goal of keeping its revenue growth and margin profile ahead of many digital ad peers. A key requirement for this thesis is continued execution on the DTiQ and IgniteGraph data platforms and SingleTap adoption, so that higher ad rates, sustained AGP growth, and international On-Device Solutions momentum can be supported while the company seeks to maintain cost discipline and balance sheet strength."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Before The Next Story Makes Headlines
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 39% below our estimate - helps clients untangle complex technical failures, user risks, and tightening regulatory or litigation questions.
- Company 2 - 18% below our estimate - supplies memory and storage hardware that has become a key bottleneck in AI infrastructure buildouts.
- Company 3 - 40% below our estimate - manages time sensitive freight where AI related cargo and compliance workloads demand specialist handling.
That is three of the list. See the full list of 25 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com