


EN
Frontier Group Holders Are Up 95% And Here Is What They Saw
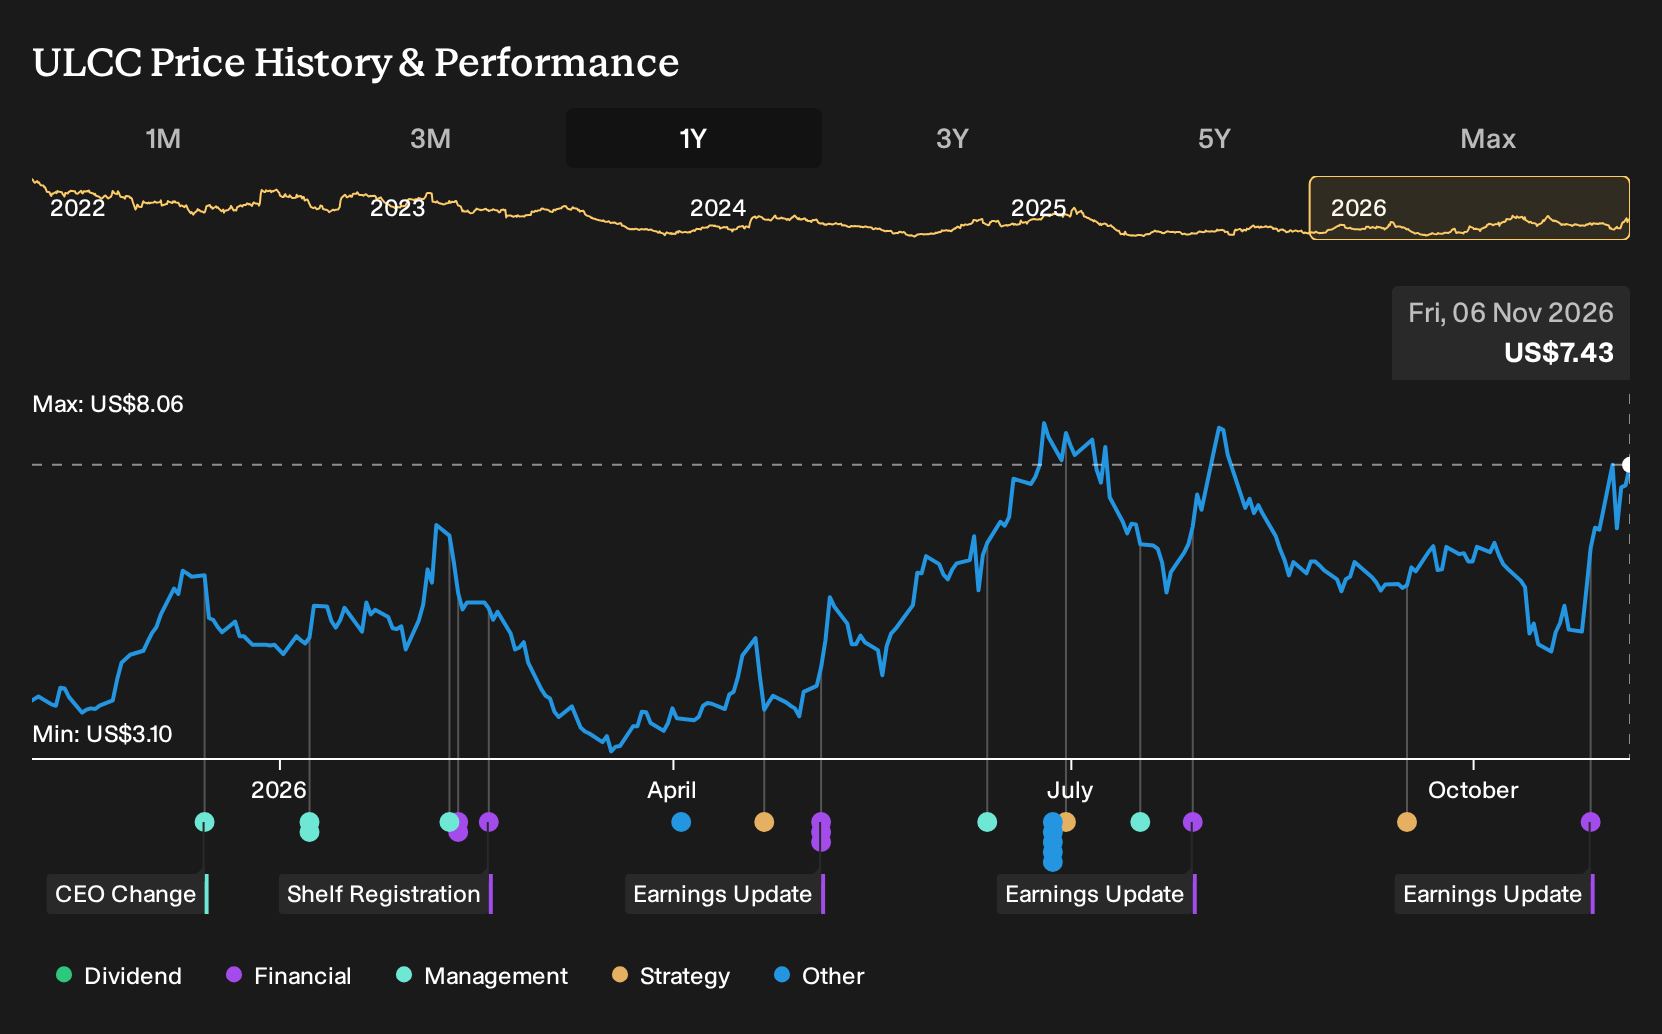
Frontier Group’s latest Q3 update put a spotlight on one concrete move: swapping out 13 A320neos while bringing in 10 larger A321neos to reshape its fleet, even as higher fuel costs kept the airline in the red. Holding Frontier Group over the past year would have returned 95.0%, including dividends. If you were deciding back on 6 November 2025, what had to look credible in those earlier forecasts for that outcome to feel worth the risk?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Frontier Group. Zero in on 40 high quality undervalued stocks for companies trading below our estimates.
The Two Frontier Group Stories Investors Had To Weigh
The shares cost US$3.89 at the start of the period, and anyone looking at Frontier Group then had to choose between two very different stories about the same airline.
On the optimistic side, one narrative saw Fair Value at US$5.39, which is 39% above the start price, assuming revenue growth of 9.2% a year and profit margins lifting to 5.2% with help from fleet modernization and digital upgrades.
The bearish narrative put Fair Value at US$3, which is 23% below the start price, and focused on rising regulatory costs and weaker US leisure demand, even while still assuming 9.0% annual revenue growth and a 4.0% margin.
What The Frontier Group Results Actually Tested
Frontier Group’s Q3 2026 report showed revenue of US$1.36b to US$1.40b versus US$886m a year earlier, and net margin improving from -8.7% to -7.7%. That supported the optimistic case on demand and scale. The story on profits was harsher, with a larger GAAP net loss of US$104m versus US$77m. Overall, the evidence cut both ways.
The whole episode turned on the profitability assumption. For any airline, test that claim directly against reported net margin and absolute earnings, not just revenue or guidance. Then see how many quarters it stays in the red.
What Frontier Group’s 95% Run Already Assumes
Frontier Group trades at US$7.43 after rising 95.0% over the past year, and the bearish analyst Narrative on Simply Wall St places its Fair Value below that level based on its own assumptions.
The Narrative centers on thin earnings, debt and dilution risk. Anyone paying today’s price is effectively betting those balance sheet and margin concerns ease faster than the Narrative fears.
"The numbers imply the share price already reflects a recovery path for Frontier Group Holdings despite continued losses, dilution risk, and analyst ratings clustered in the low single digits. The main condition for improvement is Frontier Group Holdings turning its cost savings program, fleet actions, and loyalty and premium revenue plans into sustainable profitability without eroding its ultra low cost positioning."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
How Could You Get There Earlier?
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 33% below our estimate - uses a shared cloud and AI backbone to combine subscriptions and metered services.
- Company 2 - 40% below our estimate - targets AI-driven freight workflows and complex customs tasks across its brokerage network.
- Company 3 - 19% below our estimate - sells security hardware with custom chips that tie users into one software platform.
Three companies from the same screener. Open all 25 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com