


EN
Is Charles River Laboratories International (CRL) Fully Valued After Raised EPS Guidance?
Charles River Laboratories International (CRL) has become a talking point after third quarter earnings and full year 2026 guidance updates, where stronger GAAP EPS expectations now lean heavily on a one time tax reserve reversal.
The guidance revision and strong reported earnings arrived alongside a sharp move in Charles River Laboratories International’s share price, which closed at US$337.52 after a 1-day share price return of 7.83%. That jump sits on top of a 30-day share price return of 11.84% and a 90-day gain of 19.69%, pointing to momentum building over recent months as the market responds to the tax reserve reversal and improved GAAP EPS guidance. Over a longer horizon, the picture is mixed. The year-to-date share price return of 66.74% translates into a 1-year total shareholder return of 99.75%, while the 5-year total shareholder return is down 12.23%. This underlines that the recent optimism follows a tougher multi year journey for long term holders.
See how Charles River Laboratories International compares to other contract research and biotech service players that are showing strong momentum and fundamentals, alongside the hand picked 19 high quality undiscovered gems in this space.
Charles River Laboratories International now looks like a stronger earnings engine on paper after the tax reserve reversal and price jump. The harder question is whether that quality is already fully reflected in the valuation.
Most Popular Narrative: 2% Overvalued
On Simply Wall St’s analyst consensus Narrative, Charles River Laboratories International carries a fair value estimate of $332.20 against the last close at $337.52. This frames the recent tax driven EPS jump against a valuation that already prices in a lot of execution.
The current narrative that Charles River Laboratories International is fairly valued and bullish implies that the share price already reflects management’s 2030 ambitions for 5 to 7% organic revenue growth, stronger margins and the planned $300 million of incremental savings, with limited room for additional re rating unless the company exceeds these goals.
See why 5 investors see Charles River Laboratories International as 2% overvalued.
Result: Fair Value of $332.20 (OVERVALUED)
Still, the current Charles River Laboratories International narrative could be challenged if the shift to non animal testing accelerates or if biopharma funding softens again, pressuring key segments.
Find out about the key risks to this Charles River Laboratories International narrative.
Another View: Charles River Laboratories’ Pricing Signal
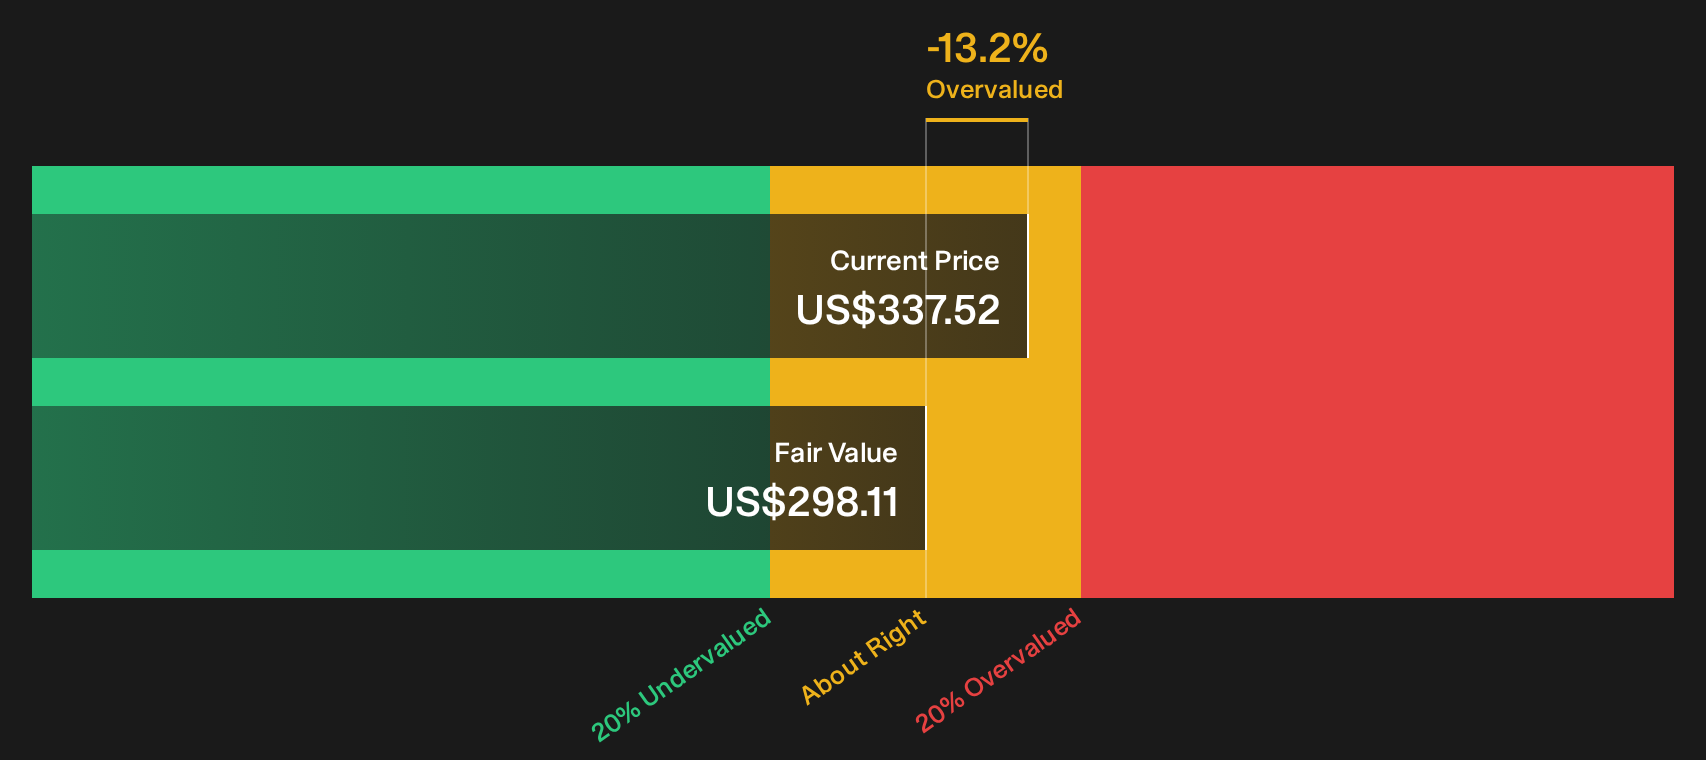
The DCF output points in a different direction. Our DCF model indicates a future cash flow value of $298.11 per share, while Charles River Laboratories International trades at $337.52. That gap presents the stock as overvalued through this lens and raises a simple question for you: Which story feels more realistic?
Before leaning on either view, it can help to understand how this cash flow based approach works in practice. Look into how the SWS DCF model arrives at its fair value.
Next Steps
If this mix of optimism and caution around Charles River Laboratories International feels familiar, consider acting while the details are fresh and weigh the trade offs yourself by checking the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Charles River Laboratories International?
Charles River Laboratories International might be front of mind today, but your next strong opportunity could sit somewhere completely different. Cast the net wider and let data rich filters surface ideas you might otherwise miss.
- Target resilient income by scanning for steady payers and higher yields through the 7 dividend fortresses.
- Surface potential value opportunities quickly by running the 40 high quality undervalued stocks and focusing on companies where quality and pricing line up more closely.
- Lean into financial strength by narrowing your search to businesses with sturdier balance sheets using the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com