


EN
Are Wall Street Analysts Predicting Duke Energy Stock Will Climb or Sink?
Headquartered in Charlotte, North Carolina, Duke Energy Corporation (DUK) generates, transmits, distributes, and sells electricity and natural gas to 8.4 million customers. Valued at $99.6 billion by market cap, the company also invests in pipeline transmission, renewable natural gas initiatives and storage infrastructure.
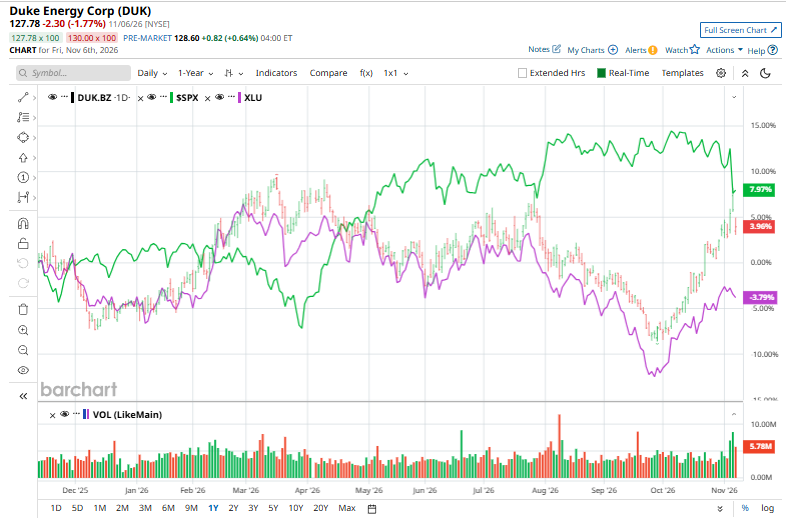
Shares of this leading energy company have underperformed the broader market over the past year. DUK has gained 3.1% over this time frame, while the broader S&P 500 Index ($SPX) has rallied 9.8%. In 2026, DUK stock is up 9%, compared to the SPX’s 7.8% rise on a YTD basis.
Narrowing the focus, DUK has surpassed the State Street Utilities Select Sector SPDR Fund’s (XLU) 2.5% fall over the past 52 weeks.
On Nov. 5, Duke Energy delivered a solid third-quarter performance, with operating revenue increasing 6.6% to $9.10 billion and EPS rising 9.9% to $1.99. Growth was primarily driven by its Electric Utilities and Infrastructure segment, which recorded a 9.6% increase in segment income, supported by favorable weather and recovery of infrastructure investments.
Additionally, management's decision to narrow full-year adjusted EPS guidance toward the higher end of its previous range and reaffirm its 5%–7% long-term earnings growth target signals confidence in the company's outlook.
For the current fiscal year, ending in December, analysts expect DUK’s EPS to grow 6.5% to $6.72 on a diluted basis. The company’s earnings surprise history is mixed. It beat the consensus estimate in three of the last four quarters while missing the forecast on another occasion.
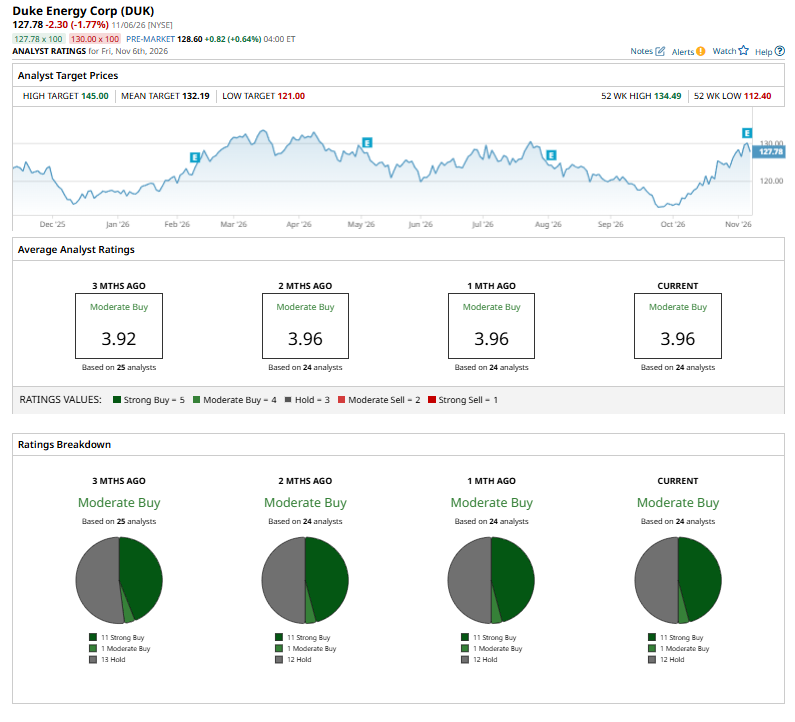
Among the 24 analysts covering DUK stock, the consensus is a “Moderate Buy.” That’s based on 11 “Strong Buy” ratings, one “Moderate Buy,” and 12 “Holds.”
On Nov. 5, Jefferies lowered its price target on Duke Energy to $138 from $143 while maintaining a “Hold” rating. The firm noted that the company's first-quarter 2026 results reaffirmed its financial targets and provided greater clarity on regulatory and growth prospects.
The mean price target of $132.19 represents an 3.5% premium to DUK’s current price levels. The Street-high price target of $145 suggests an upside potential of 178.5%.
On the date of publication, Kritika Sarmah did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.