


EN
What HD Korea Holders Got Wrong Before The Slide
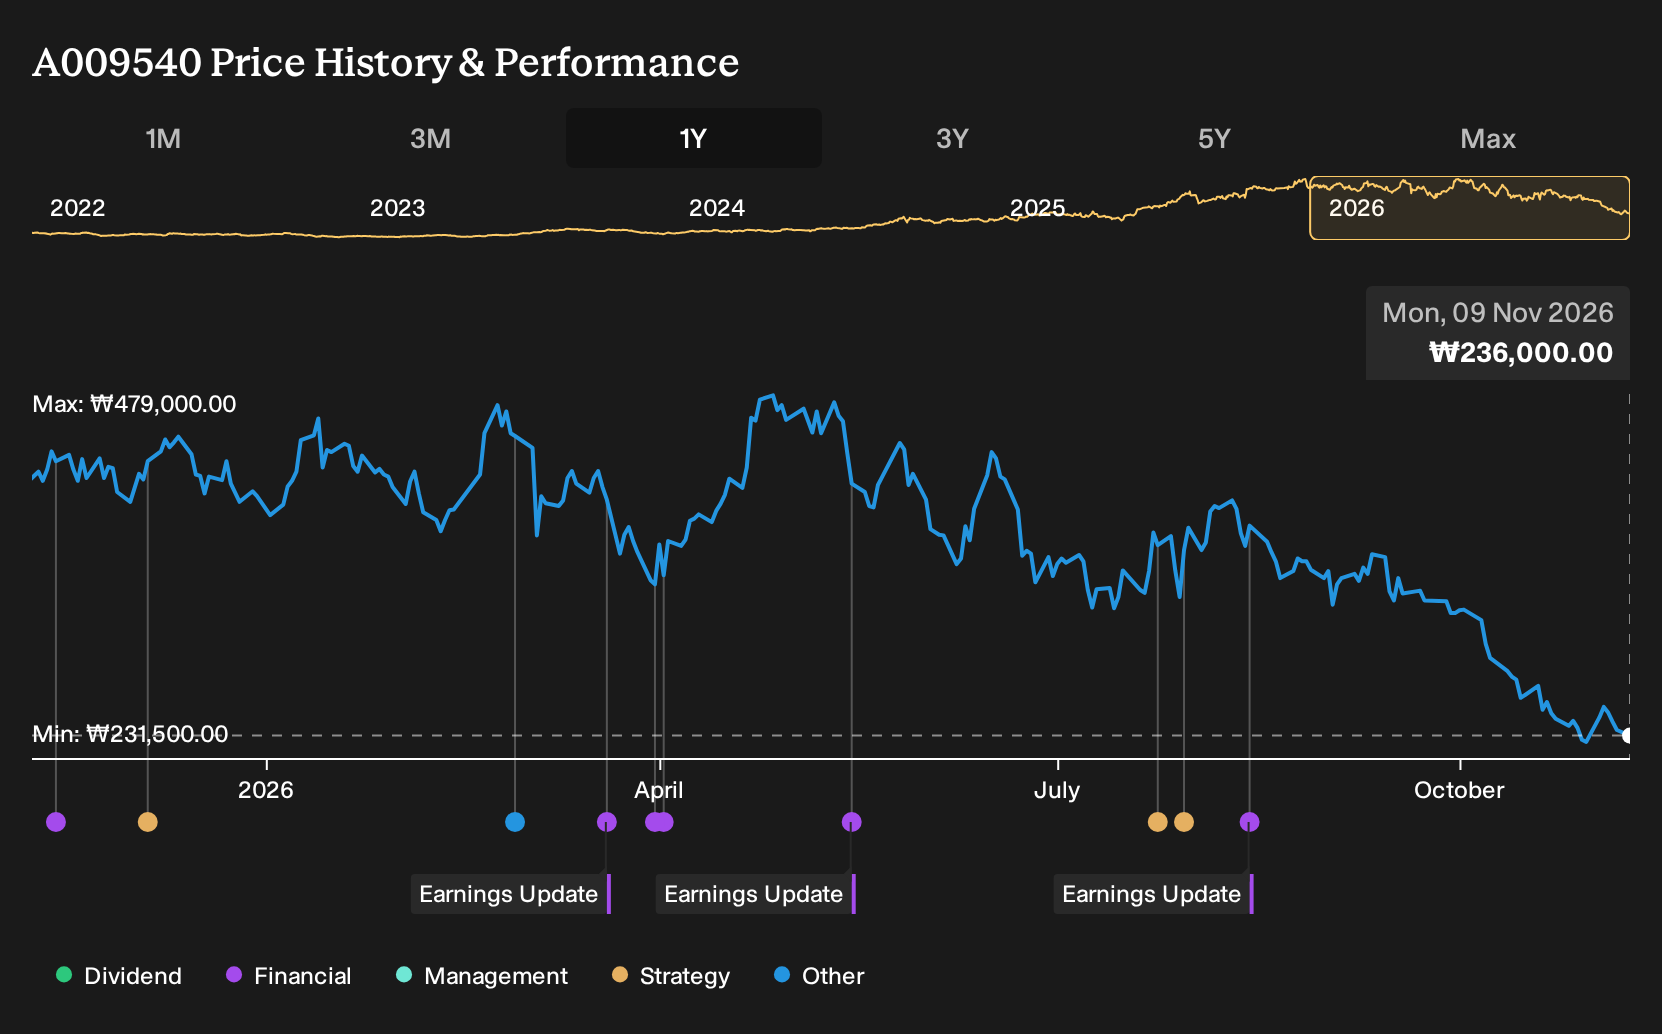
If you had seen HD Korea Shipbuilding & Offshore Engineering pitched as a beneficiary of decarbonization and offshore growth and decided to wait, the past year has not punished that hesitation. Investors who held HD Korea Shipbuilding & Offshore Engineering over the past year are down 40.1%, including dividends. With Q2 2026 revenue above Q2 2025 and net margin rising from 4.8% to 14.4%, which early assumption or risk flag could you have scrutinized to question that upbeat story?
HD Korea Shipbuilding & Offshore Engineering has already moved. See which of 224 high quality undervalued stocks still trade below our estimates.
The Argument You Would Have Been Weighing Up On HD Korea Shipbuilding & Offshore Engineering
The shares cost ₩419,000 at the start of the period, and investors were debating two very different futures for HD Korea Shipbuilding & Offshore Engineering.
The bullish story pointed to a Fair Value of ₩494,000, a rough guide to what that optimistic script implied the stock could be worth if it played out. That view leaned on decarbonization, expecting eco-ship and offshore orders to support 12.3% annual revenue growth and a profit margin rising toward 15.5%.
The bearish camp worked off a Fair Value of ₩283,000, treating that as the outcome if tougher conditions took hold. This side focused on overcapacity, fossil fuel exposure and cost pressures, assuming only 6.2% yearly revenue growth and a margin closer to 10.8%.
What The Results Changed For HD Korea Shipbuilding & Offshore Engineering
The clearest new data point was Q2 2026, when HD Korea Shipbuilding & Offshore Engineering reported revenue of ₩8,927,046.477m and net income of ₩1,287,492.189m. Net margin moved from 4.8% in Q2 2025 to 14.4%. This result leaned toward the bullish profitability script, although one set of results does not settle the long run.
The key lesson is about which claim to test. When a thesis leans on margin expansion, track net margin in each report and compare it directly with the original forecast path, rather than just watching revenue or the share price.
What HD Korea Shipbuilding & Offshore Engineering's Lower Price Asks You To Believe
HD Korea Shipbuilding & Offshore Engineering now trades at ₩240,000. The bullish analyst Narrative on Simply Wall St views its Fair Value as higher than that current price, based on a richer mix of high margin vessels, engines and offshore projects.
This view depends on HD Korea Shipbuilding & Offshore Engineering continuing to execute on productivity gains and sustaining a higher margin mix across LNG and LPG carriers, engines and offshore and defense work.
"Bullish analysts expect HD Korea Shipbuilding & Offshore Engineering to convert its long-duration backlog in high value-added vessels, engines and offshore projects into structurally higher earnings power over the coming years. The main factor that has to go right is continued execution on productivity gains and a high margin mix, including LNG and LPG carriers, dual fuel and HiMSEN engines, and profitable offshore and defense projects, despite cyclical swings in ordering and regional project delays."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Looking Beyond HD Korea Shipbuilding
HD Korea Shipbuilding & Offshore Engineering operates in a world reshaped by decarbonization and offshore spending. Yet some customers think even higher.
They still need dependable access to space, along with rockets and satellites that keep data and communications flowing.
Another company is working across both needs, launching payloads while also building the hardware that goes up.
If it holds flight costs down and reliability up, its services could feel like routine infrastructure.
That possibility might shift how you view exposure to the broader space economy.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 84% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com