


EN
Here's What We Like About Cintas' (NASDAQ:CTAS) Upcoming Dividend
Regular readers will know that we love our dividends at Simply Wall St, which is why it's exciting to see Cintas Corporation (NASDAQ:CTAS) is about to trade ex-dividend in the next three days. The ex-dividend date occurs one day before the record date, which is the day on which shareholders need to be on the company's books in order to receive a dividend. The ex-dividend date is important as the process of settlement involves a full business day. So if you miss that date, you would not show up on the company's books on the record date. Meaning, you will need to purchase Cintas' shares before the 13th of November to receive the dividend, which will be paid on the 15th of December.
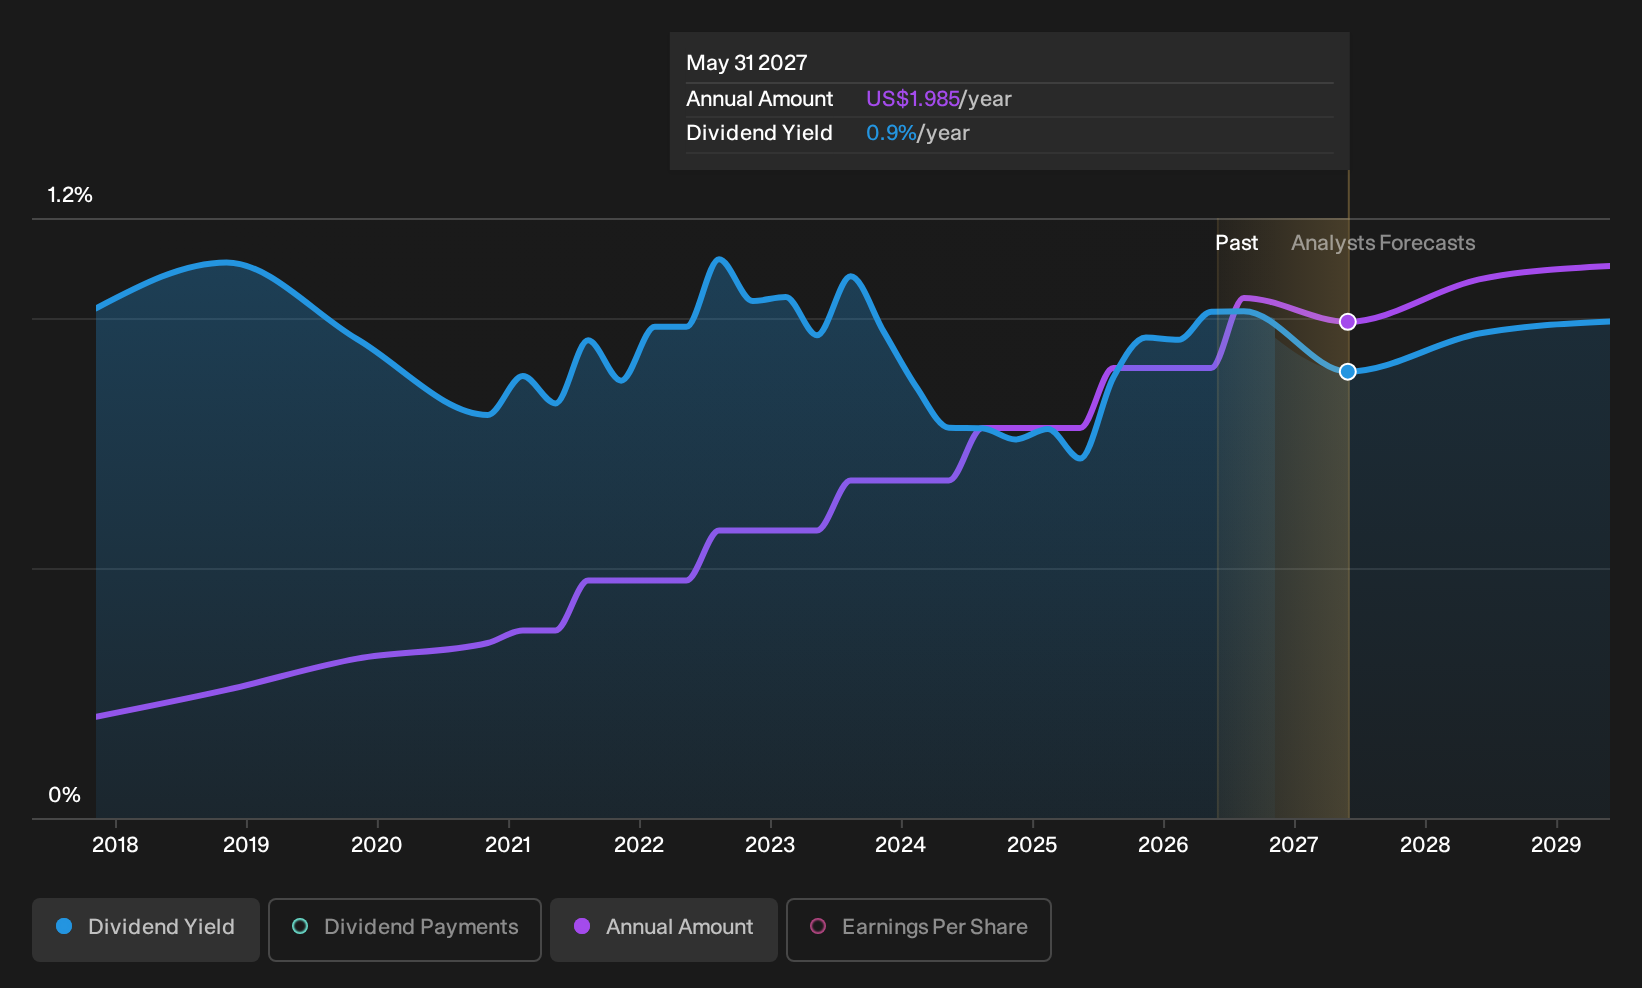
The company's next dividend payment will be US$0.52 per share, and in the last 12 months, the company paid a total of US$2.08 per share. Based on the last year's worth of payments, Cintas has a trailing yield of 0.9% on the current stock price of US$222.36. If you buy this business for its dividend, you should have an idea of whether Cintas's dividend is reliable and sustainable. That's why we should always check whether the dividend payments appear sustainable, and if the company is growing.
If a company pays out more in dividends than it earned, then the dividend might become unsustainable - hardly an ideal situation. That's why it's good to see Cintas paying out a modest 36% of its earnings. Yet cash flow is typically more important than profit for assessing dividend sustainability, so we should always check if the company generated enough cash to afford its dividend. It distributed 36% of its free cash flow as dividends, a comfortable payout level for most companies.
It's positive to see that Cintas's dividend is covered by both profits and cash flow, since this is generally a sign that the dividend is sustainable, and a lower payout ratio usually suggests a greater margin of safety before the dividend gets cut.
See our latest analysis for Cintas
Click here to see the company's payout ratio, plus analyst estimates of its future dividends.
Have Earnings And Dividends Been Growing?
Stocks in companies that generate sustainable earnings growth often make the best dividend prospects, as it is easier to lift the dividend when earnings are rising. If earnings decline and the company is forced to cut its dividend, investors could watch the value of their investment go up in smoke. Fortunately for readers, Cintas's earnings per share have been growing at 14% a year for the past five years. The company has managed to grow earnings at a rapid rate, while reinvesting most of the profits within the business. Fast-growing businesses that are reinvesting heavily are enticing from a dividend perspective, especially since they can often increase the payout ratio later.
The main way most investors will assess a company's dividend prospects is by checking the historical rate of dividend growth. In the past 10 years, Cintas has increased its dividend at approximately 23% a year on average. Both per-share earnings and dividends have both been growing rapidly in recent times, which is great to see.
Final Takeaway
From a dividend perspective, should investors buy or avoid Cintas? We love that Cintas is growing earnings per share while simultaneously paying out a low percentage of both its earnings and cash flow. These characteristics suggest the company is reinvesting in growing its business, while the conservative payout ratio also implies a reduced risk of the dividend being cut in the future. There's a lot to like about Cintas, and we would prioritise taking a closer look at it.
Ever wonder what the future holds for Cintas? See what the 18 analysts we track are forecasting, with this visualisation of its historical and future estimated earnings and cash flow
A common investing mistake is buying the first interesting stock you see. Here you can find a full list of high-yield dividend stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.