


EN
Do Wall Street Analysts Like NRG Energy Stock?
Valued at $18.6 billion by market cap, NRG Energy, Inc. (NRG) is a leading energy and smart-home services company that generates and sells electricity and natural gas to residential, commercial, industrial, and wholesale customers across the United States and Canada. The company operates a diversified portfolio of power generation assets, including natural gas-fired and dual-fuel facilities, and serves approximately 8 million residential customers through brands such as NRG, Reliant, Direct Energy, Green Mountain Energy, and Vivint.
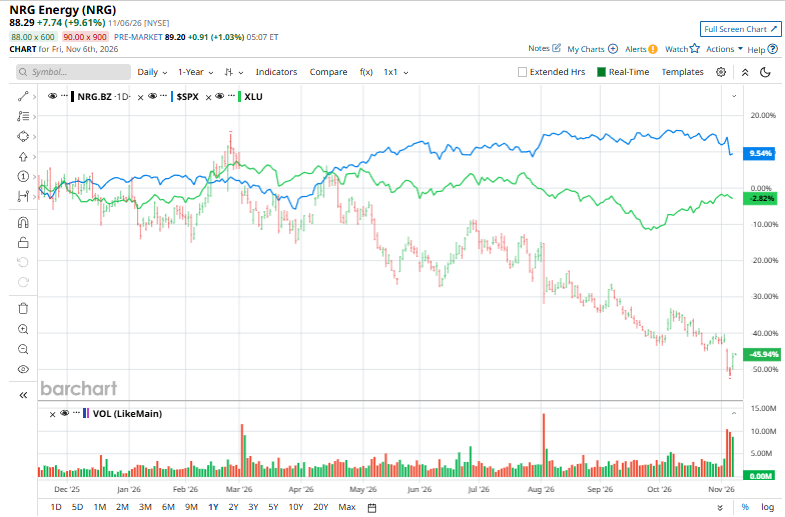
Shares of NRG have underperformed the broader market over the past year. NRG has declined 48.1% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 9.8%. Moreover, in 2026, NRG stock is down 44.6%, compared to the SPX’s 7.8% rise on a YTD basis.
Zooming in further, NRG has outperformed the sector-focused State Street Utilities Select Sector SPDR Fund’s (XLU) 2.5% fall over the past 52 weeks.
NRG Energy heads into its third-quarter 2026 earnings on Nov. 9 with a major growth story to prove. Following its $12 billion LS Power acquisition, which doubled its generation capacity to approximately 25 GW, the company is betting on its expanded power fleet and surging AI-driven electricity demand to fuel future growth. Its landmark 1.2 GW power agreement with a hyperscaler further strengthens that opportunity. However, the growth ambitions face near-term hurdles, including mild weather, weaker Texas retail margins, rising interest expenses, and acquisition integration risks.
For the current fiscal year, ending in December 2026, analysts expect NRG’s EPS to grow 6.8% to $8.62 on a diluted basis. The company’s earnings surprise history is mixed. It beat the consensus estimate in two of the last four quarters, while missing on two other occasions.
Among the 15 analysts covering NRG stock, the consensus is a “Strong Buy.” That’s based on 12 “Strong Buy” ratings and three “Hold.”
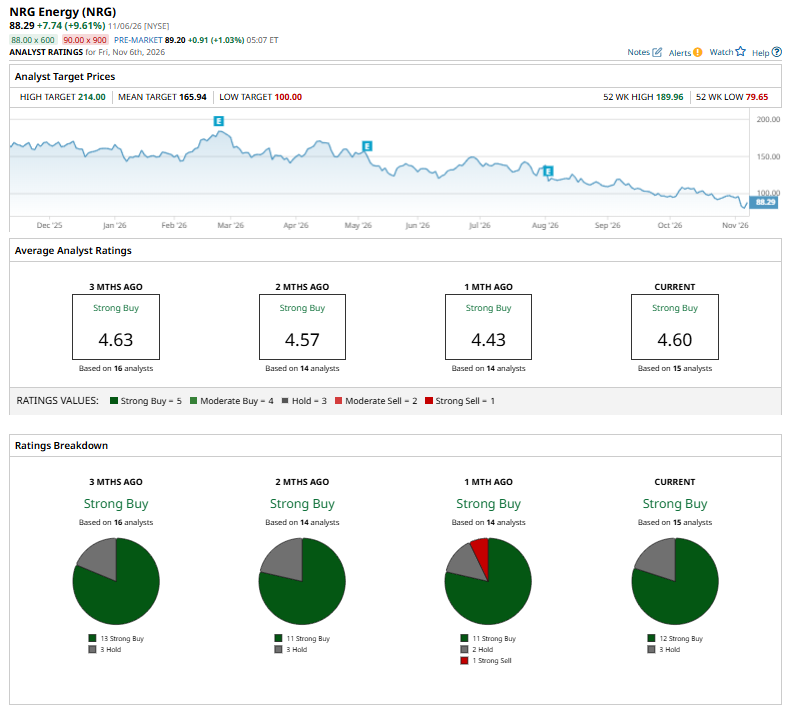
This configuration is more bullish than one month ago, with 11 analysts suggesting a “Strong Buy.”
On Oct. 21, Morgan Stanley analyst David Arcaro lowered his price target on NRG Energy to $144 from $159 while maintaining an “Equal-Weight” rating.
The mean price target of $165.94 represents a 87.9% premium to NRG’s current price levels. The Street-high price target of $214 suggests an ambitious upside potential of 142.4%.
On the date of publication, Kritika Sarmah did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.