


EN
Did Earnings Recovery Just Shift Starbucks (SBUX) Investment Narrative?
- Starbucks reported fourth quarter 2026 revenue of US$9,141.2 million compared with US$9,569 million a year earlier, while net income increased to US$677.2 million and diluted EPS from continuing operations reached US$0.59 versus US$0.12.
- For the full year 2026, Starbucks recorded revenue of US$37,910.6 million and net income of US$2,526.7 million, with diluted EPS from continuing operations of US$2.21 compared with US$1.63. This points to improved profitability despite a guided 1% revenue decline for fiscal 2027 tied to the China licensing shift.
- Next, the focus will be on how Starbucks' stronger earnings and the China licensing transition reshape the investment narrative around profitability, capital allocation, and growth.
Scan beyond Starbucks and compare this earnings story against 40 high quality undervalued stocks that currently trade at a discount to their cash flow strength and balance sheet quality.
Starbucks Investment Narrative Recap
To own Starbucks, you have to be comfortable with a business that leans heavily on store-level economics, brand strength, and efficiency gains rather than rapid top line expansion. The guided 1% revenue decline for fiscal 2027, largely tied to the China licensing shift, puts more weight on execution in North America and disciplined cost control as the near term profit driver.
The main short term swing factor is how consistently Starbucks can translate its store upgrades, app engagement and delivery integration into steady earnings while absorbing higher labor and operating costs. The biggest risk sits in the balance sheet, with high debt and negative equity limiting room for error if consumer demand softens.
The clearest reference point is the fiscal 2027 earnings outlook. Management is calling for diluted EPS of US$3.07 to US$3.17 while also flagging that consolidated net revenue should decline about 1% year on year, including around US$700 million tied to the 53rd week and the China retail transition. According to LunaRodas, an investor in the Simply Wall St Community who wrote the Narrative, the recent tone from leadership has shifted toward greater confidence, which raises the bar on delivery.
For you as a shareholder, that guidance frames the tension between execution and valuation. Starbucks has been producing higher earnings, with net profit of US$2,526.7 million in 2026 and current net profit margins of 6.7% versus 5% a year ago, while the stock trades on a P/E of 47.6x compared with a lower DCF estimate and peer multiples. LunaRodas focuses on operational follow through as the key catalyst, which now has to play out against a balance sheet that carries high debt and negative equity.
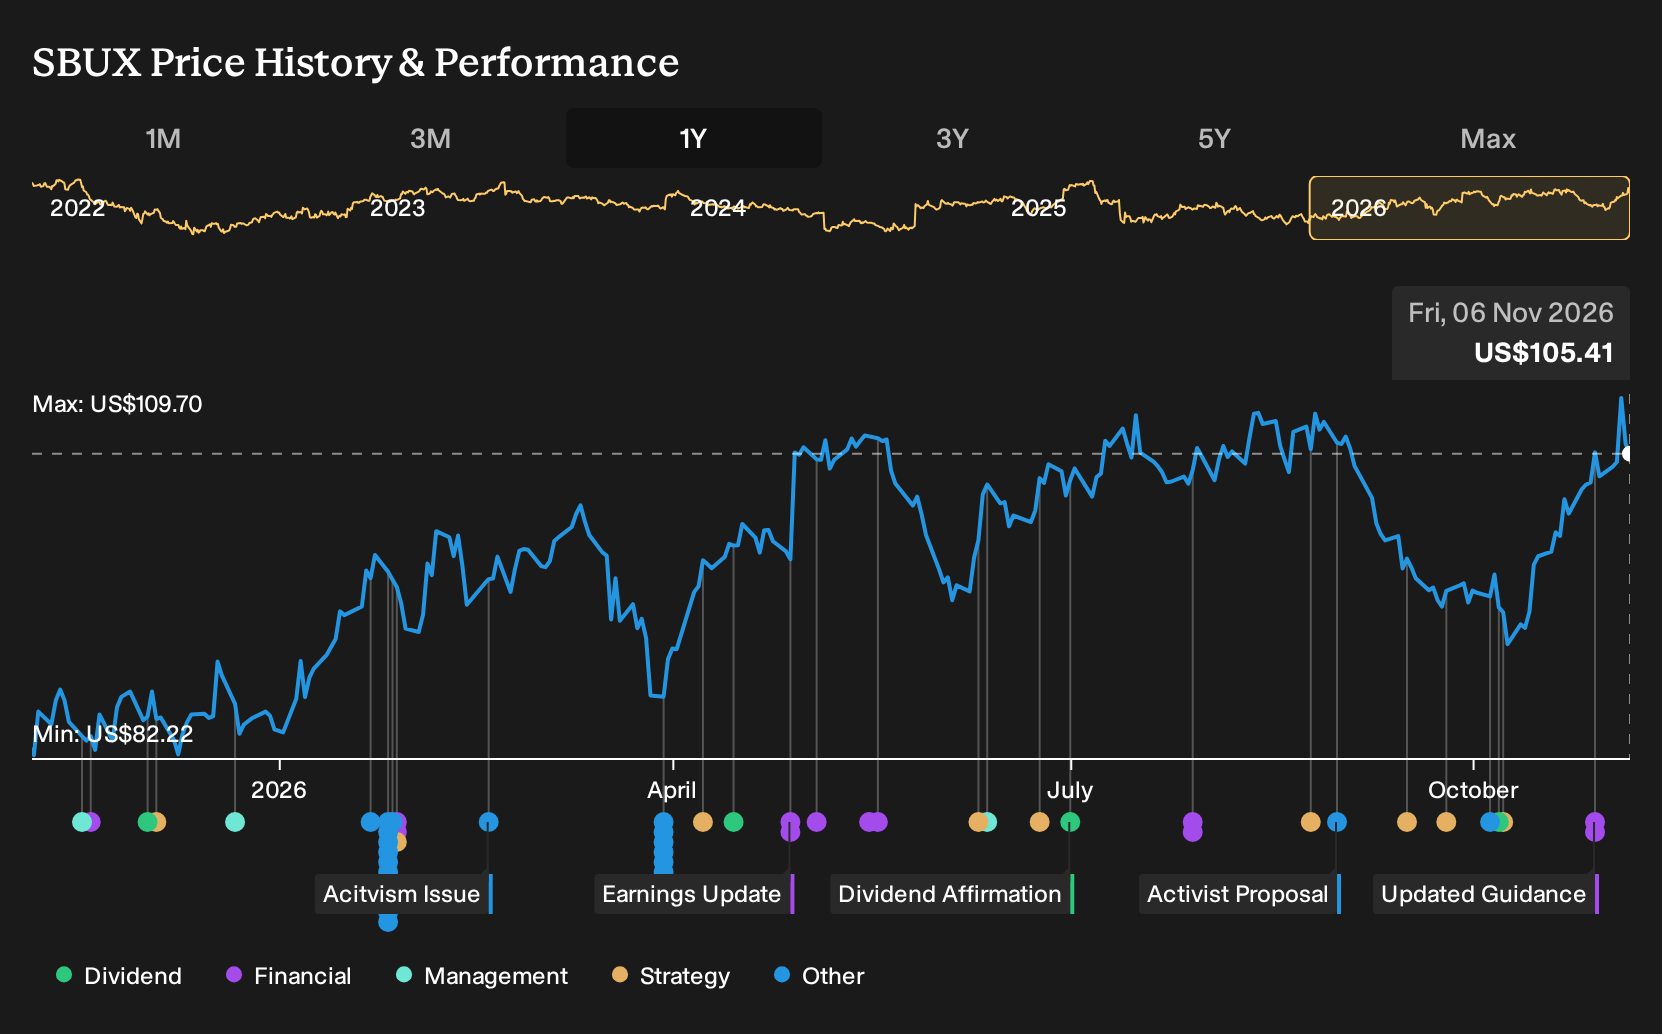
LunaRodas anchors Starbucks' fair value at US$99.95, based on management treating the Back to Starbucks program as a completed turnaround and now as a growth plan, with uplifted stores, absorbed Green Apron Service costs, and margin expansion presented as ongoing features rather than temporary aids.
Uncover why Starbucks' fair value indicates a potential 5% downside to its current price, leaving little room for error.
Exploring Other Perspectives
One alternative narrative focuses less on Starbucks hitting its EPS guidance and more on whether remodel and labor costs keep squeezing profitability. The most cautious analysts were penciling in revenue of about US$42.5b and earnings of roughly US$4.9b by 2029, yet still saw limited upside. That is a materially more pessimistic reading than the baseline, and it shows how widely opinions can differ. Use this earnings update as a prompt to compare those pre news assumptions with your own view, and explore several competing forecasts before deciding what feels reasonable.
Explore 6 other Starbucks fair value estimates, including one that suggests as much as 24% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis and judgment.
- A great starting point for your Starbucks research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Starbucks. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Starbucks' overall financial health at a glance.
Looking For More Investment Ideas Beyond Starbucks?
If this Starbucks update has sharpened your thinking about valuation, quality and risk, use that same lens to scan a broader opportunity set with the Simply Wall St Screener.
- If capital preservation ranks high for you, start with resilient companies by reviewing 31 resilient stocks with low risk scores that may better fit a defensively tilted watchlist.
- For a blend of quality and value, consider businesses on our 19 high quality undiscovered gems that pair solid fundamentals with lighter investor attention.
- If balance sheet strength is non negotiable, filter for financially sturdy companies through the list of solid balance sheet and fundamentals (25 results) and see which ones deserve a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com