


EN
AMN Healthcare Services (AMN) Reports Stronger Q3 Results, Is The Valuation Still Too Rich?
Why AMN Healthcare Services Stock Is Back in Focus
AMN Healthcare Services (AMN) landed back on investor watchlists after its early November earnings release, which paired higher third quarter sales and profit with fresh fourth quarter guidance.
That earnings update landed after a huge run, with AMN Healthcare Services posting a 139.4% year to date share price return and a 108.1% total shareholder return over 12 months, even though the stock has recently fallen 23.7% on a 1 day basis and 20.9% over the past week as investors reassessed the new fourth quarter guidance and recent acquisition news.
Capitalize on the renewed interest in AMN Healthcare Services by comparing it with a curated group of 40 high quality undervalued stocks that share strong fundamentals and may be attractively priced.Bulls point to AMN Healthcare Services' recent earnings strength and acquisitions, while bears flag the sharp pullback and softer margin outlook. Which side does the current valuation data support next?
Price-to-Earnings of 12.8x: Is it justified?
Valuation on AMN Healthcare Services hinges on earnings. At a P/E of 12.8x against a last close of $36.19, the stock screens cheaper than many peers, while some other metrics point to a richer price tag.
The P/E ratio compares what investors pay today for each dollar of profit. For a workforce solutions provider like AMN Healthcare Services, that lens matters because earnings quality, debt levels and earnings volatility can all influence how much of a premium or discount the market is willing to assign.
On the supportive side, AMN is flagged as good value on P/E both versus the broader US market and the US Healthcare sector, and its earnings are described as high quality. Against that, the SWS DCF model suggests the shares trade above an estimated future cash flow value of $22.38, and AMN is described as expensive relative to an estimated fair P/E of 4x, a level the market could move towards if expectations keep resetting lower.
That tension is clear in the peer and fair value comparisons. AMN Healthcare Services trades on 12.8x earnings versus a US Healthcare industry average of 24.9x and a broader US market at 17.4x, which is a marked discount. Yet compared with the estimated fair P/E of 4x, the current multiple is much higher, which strongly suggests the market is still paying up relative to that fair ratio framework even after the recent pullback.
Explore the SWS fair ratio for AMN Healthcare Services.
Result: Price-to-Earnings of 12.8x (OVERVALUED)
Still, AMN Healthcare Services faces risks if revenue and net income, which both declined on an annual basis, continue to trend lower and recent share price swings persist.
Find out about the key risks to this AMN Healthcare Services narrative.
Another View: What The DCF Says About AMN Healthcare Services
The P/E picture makes AMN Healthcare Services look cheap against the sector, yet the SWS DCF model points the other way. With an estimated future cash flow value of $22.38 against a share price of $36.19, that framework paints AMN as overvalued. Which lens should matter more for you?
Look into how the SWS DCF model arrives at its fair value.
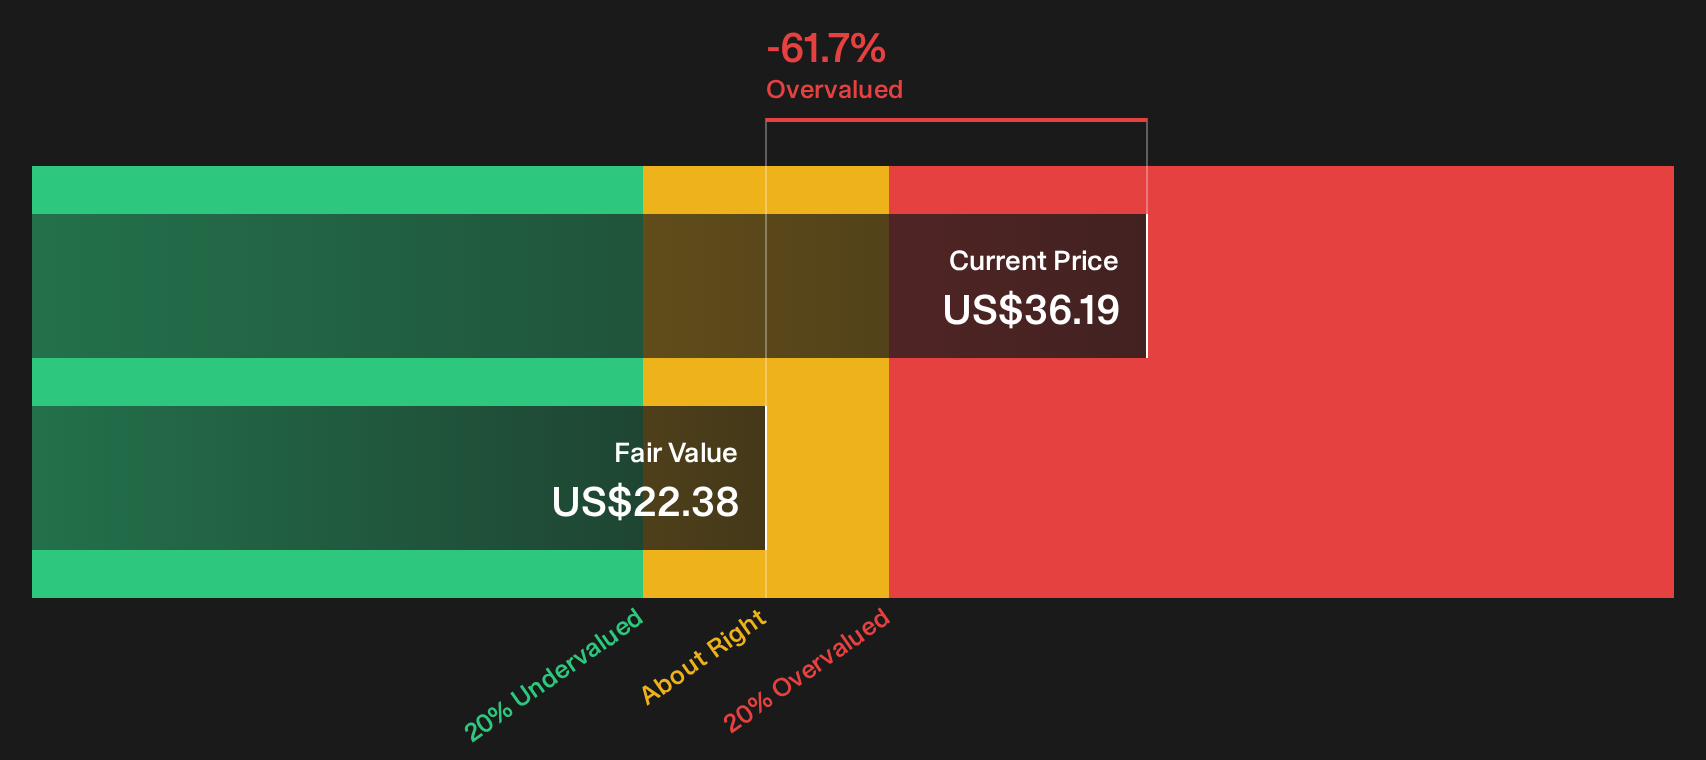
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out AMN Healthcare Services for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 40 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on AMN Healthcare Services so far. If you want to move quickly and ground your own view in the numbers, start with the 2 key rewards and 2 important warning signs.
Looking for more AMN Healthcare Services style investment ideas?
Broaden your opportunity set beyond AMN Healthcare Services and put fresh ideas on your radar with the Simply Wall St screener before the next moves take shape.
- Target potential upside where quality and price intersect by scanning a curated pool of 40 high quality undervalued stocks that already show robust underlying fundamentals.
- Reduce portfolio stress by focusing on capital preservers through a tailored lineup of 31 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
- Get ahead of the crowd by zeroing in on 19 high quality undiscovered gems that combine solid numbers with limited current market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com