


EN
What Investors Got Wrong Before MTR's Rally
If you only glanced at MTR’s latest half year figures, a jump in net margin to 62.9% on lower revenue might look like the whole story. Investors who held MTR over the past year are up 20.5%, including dividends. If you had bought at the decision date, that outcome would feel reassuring. Yet with fresh multibillion dollar rail commitments now locked in, it is worth asking what exactly that return rewarded, and what risk still sits on the tracks.
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
The easy part of this move is behind MTR. Zero in on 224 high quality undervalued stocks for companies trading below our estimates.
What Expectations Were Actually On The Table For MTR?
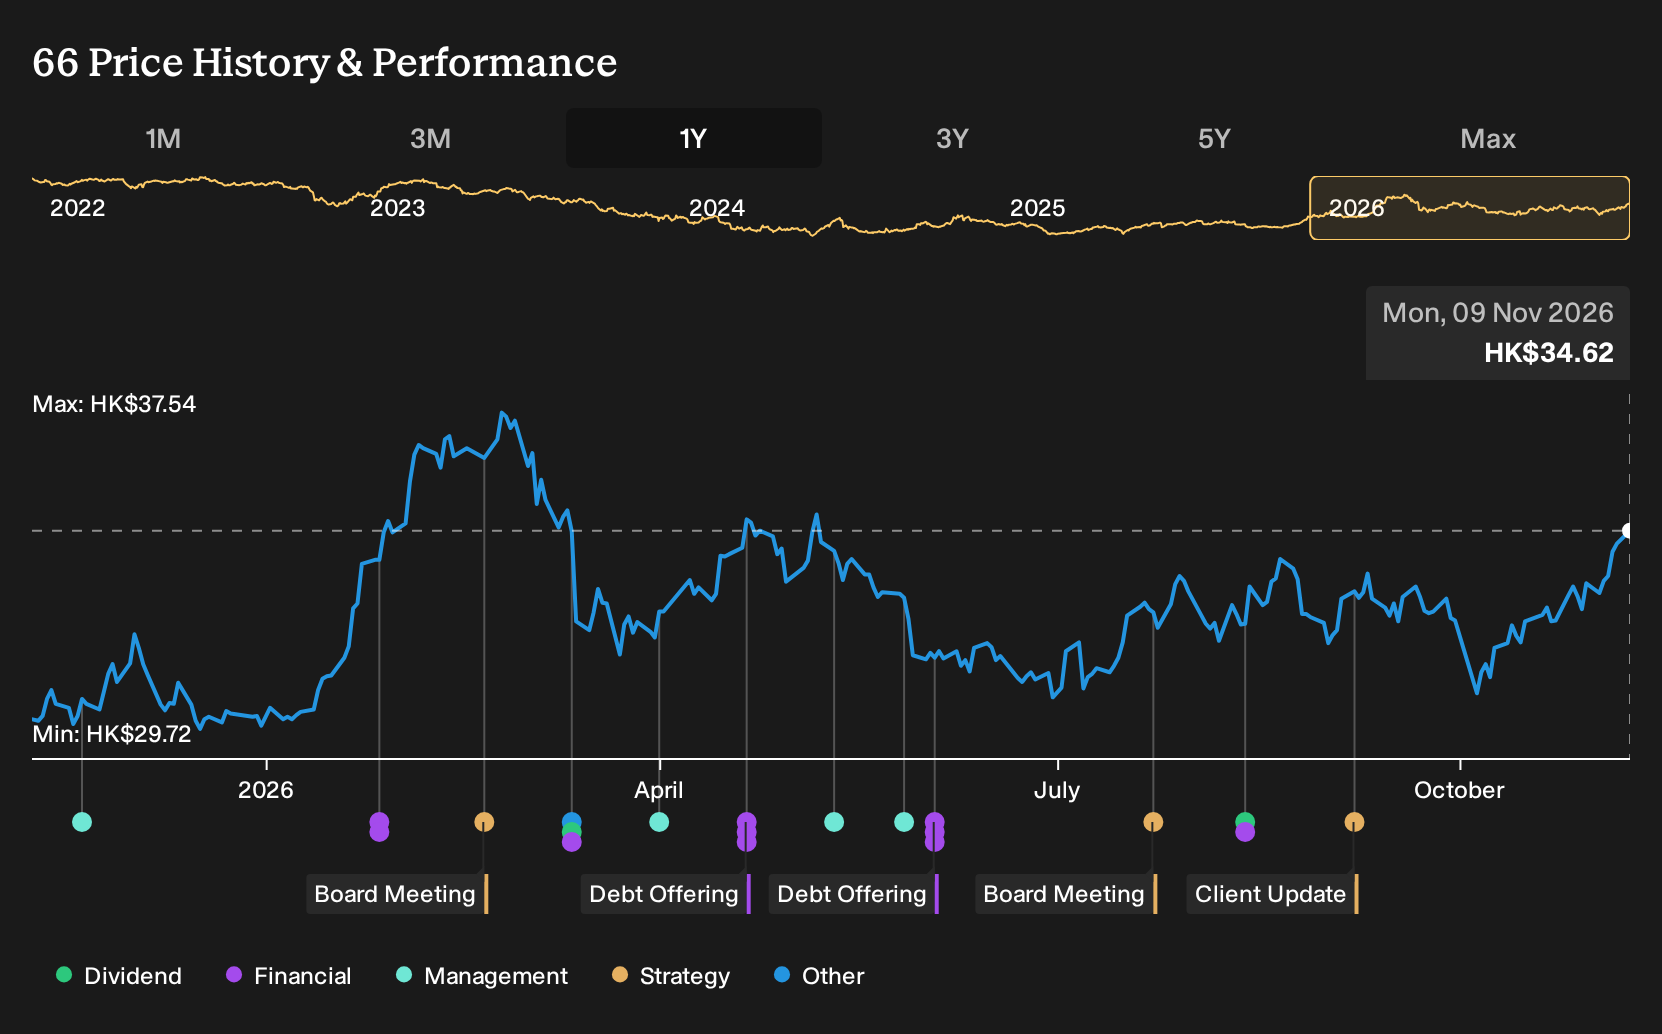
The shares cost HK$30 at the start of the period. Anyone buying MTR then was deciding whether the story of urban growth, technology and new projects justified a bullish Fair Value of HK$32 or not.
On the positive side, one Narrative argued that city expansion and major property projects could support ridership and higher margin property completions. This view also assumed the business could justify a future P/E of 20.6x on 2028 earnings.
The cautious view put Fair Value closer to HK$27.86 and focused on heavy Hong Kong rail and property spending. It also highlighted the risk that slower passenger growth and hybrid work left a 3.3% revenue growth assumption looking stretched.
What The Evidence Did To The MTR Argument
MTR’s commitment to about US$5b for the Northern Metropolis railway, plus the A$880m Parramatta Metro station contract, backed the bullish story of big rail and property projects. The reported results pulled the other way. Revenue moved from HK$27,360m in H1 2025 to HK$26,231m in H1 2026, while net income and margin rose sharply. Overall, the evidence cut both ways.
The hinge assumption here was that heavy capital spending would earn its keep. For any other rail or infrastructure stock, track whether higher capex aligns with sustained profit margins, rather than focusing only on headline project wins.
What MTR’s One Year Rally Already Prices In
MTR now trades at HK$34.62 after a 20.5% gain over the past year, while this cautious Narrative’s Fair Value sits below the current price based on its own assumptions.
That view leans on the idea that today’s buyer is effectively assuming large rail and property projects convert into durable earnings. The key question is how recurrent profit pressure and project risk might challenge that belief.
"The main thing that has to go right is that MTR turns its large rail expansion and Rail plus Property pipeline, including more than HK$100b of projects and thousands of housing units, into sustainable earnings that support both capital spending and dividends without relying on one off property profits."
One Narrative disagrees with today's price. → See where this Narrative says MTR should trade
Where MTR’s Rail Story Meets Streets
MTR focuses on fixed lines and long lived projects. Your daily trip probably starts and ends somewhere very different.
Between stations, people still need flexible transport that appears on demand. One global platform now links those short journeys across cities and suburbs.
Its software matches riders and drivers, processes payments and coordinates logistics. The same system also brings meals, groceries and other essentials to doorsteps.
As MTR pursues large rail builds, this other player is investing in driverless fleets. The unresolved issue is who will capture more of everyday travel economics.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 69% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com