


EN
Why Americold Realty Trust (COLD) Is Back In The Spotlight
Why Americold Realty Trust Stock Is Back On Investor Radars
Americold Realty Trust (COLD) is drawing fresh attention after raising its 2026 AFFO outlook, closing a sizeable joint venture with EQT, and reporting a sharp earnings turnaround alongside new technology investments.
The recent move to around US$16.01 comes after a sharp shift in sentiment, with a 9.66% 7 day share price return and a 23.72% year to date share price gain clustering around Americold Realty Trust's updated outlook, balance sheet reshaping and Q3 turnaround, even though the 3 year and 5 year total shareholder returns remain negative.
Scan beyond Americold Realty Trust's rebound into other potential turnaround stories with strong fundamentals using the hand picked 40 high quality undervalued stocks screener.
Bulls point to Americold Realty Trust's Q3 earnings swing, higher 2026 AFFO outlook and balance sheet reset, while bears focus on weak demand and past losses. Which story does the valuation actually support next?
Most Popular Narrative: 1% Undervalued
Americold Realty Trust's analyst consensus Narrative on Simply Wall St pegs fair value at about $16.24 per share, almost level with the recent $16.01 close. This puts the focus firmly on how execution and earnings quality shape the story from here.
The main consideration is that Americold successfully converts its deleveraging, cost savings, and mix shift toward higher margin services into sustainable AFFO per share while managing power costs and the earnings dilution from the joint venture.
The current valuation implies the share price already reflects a fairly valued, bearish stance. Improved operations and a stronger balance sheet are largely priced in, which leaves limited room for missteps on demand, power costs, or further impairments.
See why 10 investors see Americold Realty Trust as 1% undervalued.
Result: Fair Value of $16.24 (ABOUT RIGHT)
Still, the Americold Realty Trust story could shift quickly if soft consumer demand further drags on occupancy, or if higher power costs keep pressuring warehouse margins.
Find out about the key risks to this Americold Realty Trust narrative.
Another View: What Americold Realty Trust’s P/E Is Really Saying
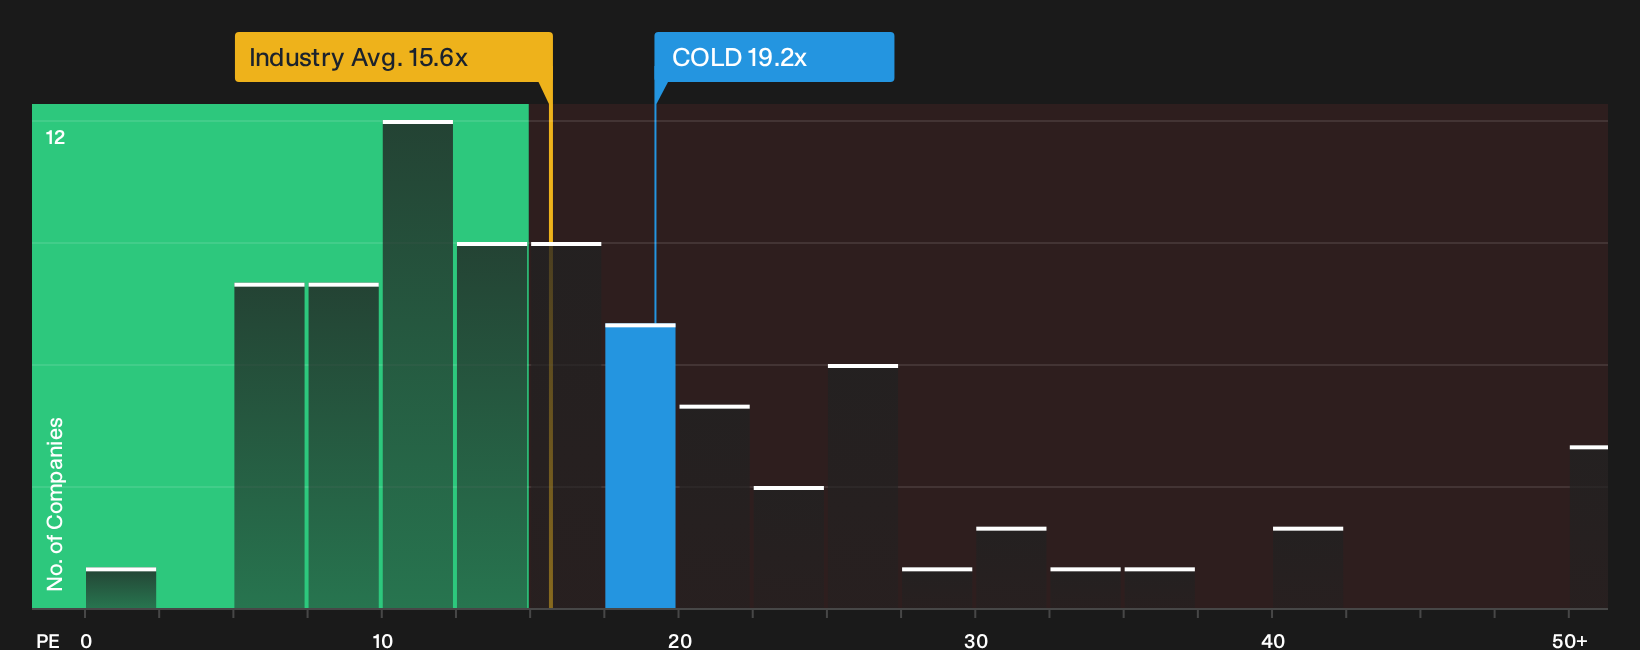
On a cash flow basis, Americold Realty Trust screens as cheap, yet its 19.2x P/E looks expensive next to the global Industrial REITs average of 15.6x and more reasonable beside 25x for peers. The fair ratio of 37.8x suggests the market could shift, but which direction matters more for you?
See what the numbers say about this price in a fuller multiple-based breakdown, then compare it with how other investors are framing the story through See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages in the Americold Realty Trust story so far. Act quickly, stress test the numbers yourself, and weigh up the 3 key rewards and 3 important warning signs.
Looking For More Investment Ideas Beyond Americold Realty Trust?
If Americold Realty Trust has you rethinking your watchlist, now is the moment to widen your lens and evaluate additional opportunities before they move.
- Identify potential mispricings by scanning a curated pool of resilient cash generators through the 40 high quality undervalued stocks.
- Strengthen your income stream by focusing on businesses that combine strong yields with staying power using the 7 dividend fortresses.
- Reduce portfolio stress and concentrate on durability by filtering candidates through the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com