


EN
Is Wall Street Bullish or Bearish on Tyson Foods Stock?
Springdale, Arkansas-based Tyson Foods, Inc. (TSN) operates worldwide as a food company. The company has a market cap of $21 billion and operates through four segments: Beef, Pork, Chicken, and Prepared Foods. TSN processes live-fed cattle and hogs, and manufactures and markets frozen and refrigerated food products, including ready-to-eat sandwiches, flame-grilled hamburgers, Philly steaks, pepperoni, bacon, breakfast sausage, turkey, lunchmeat, and more.
TSN shares have rallied the broader market over the past year, surging 15.5% compared to the S&P 500 Index’s ($SPX) 9.8% surge. However, in 2026, the stock has grown by nearly 1.8%, underperforming the SPX’s 7.8% rise.
Focusing on its industry benchmark, the State Street Consumer Staples Select Sector SPDR ETF (XLP) has risen 19.2% over the past year, outperforming the stock. In 2026, XLP has grown 16% and has also rallied the stock.
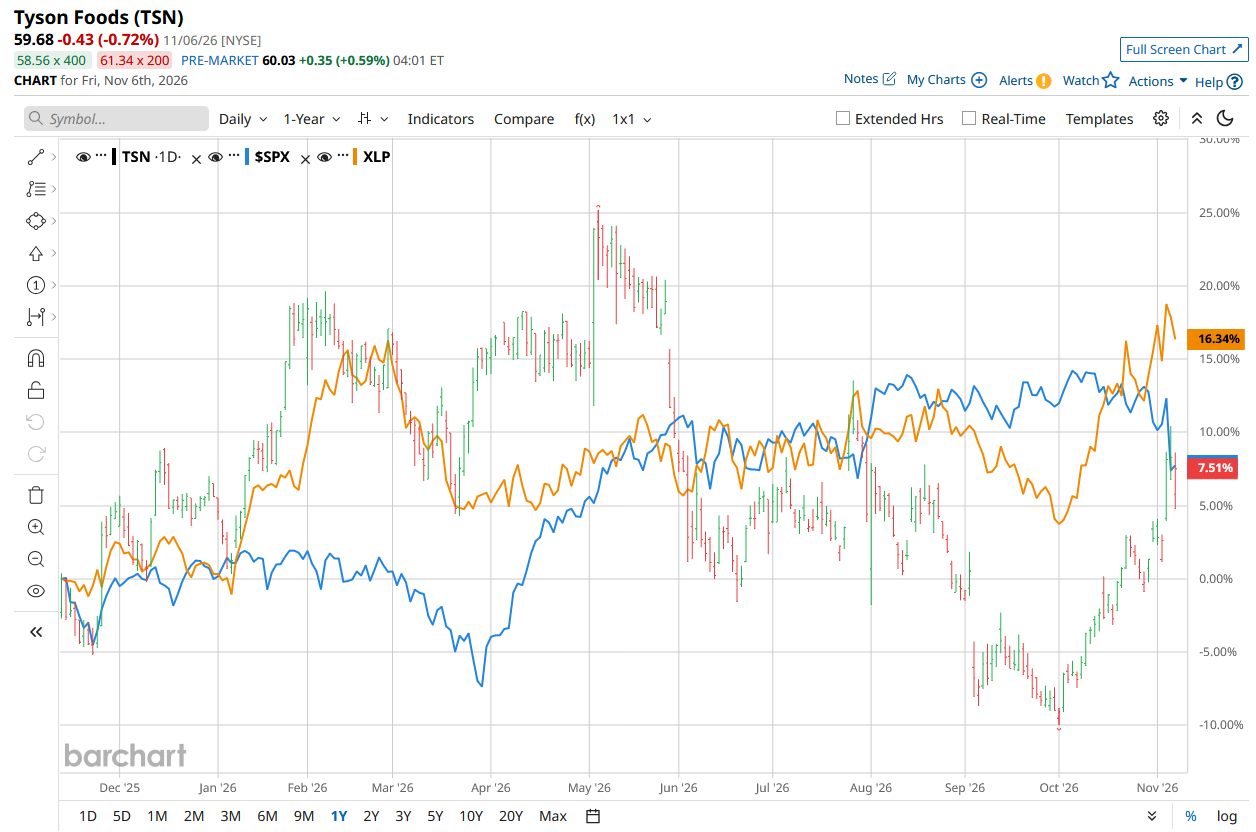
TSN’s fundamentals have not been quite up to par with analyst expectations. The company’s unit sales over the past two years have remained flat, indicating soft demand for its products. Moreover, Wall Street also expects its revenue to remain unchanged over the next year as well, again pointing out the company’s demand-related issues. TSN also has a gross margin of 6.9%, lagging behind the sector average.
For the current year, which ended in September, analysts expect TSN’s EPS to fall 15.3% to $3.49 on a diluted basis. The company surpassed the consensus estimate in two of the last four quarters, while missing on two occasions.
Among the 11 analysts covering TSN stock, the consensus is a “Moderate Buy.” That’s based on five “Strong Buy” ratings, five “Holds,” and one “Strong Sell.”
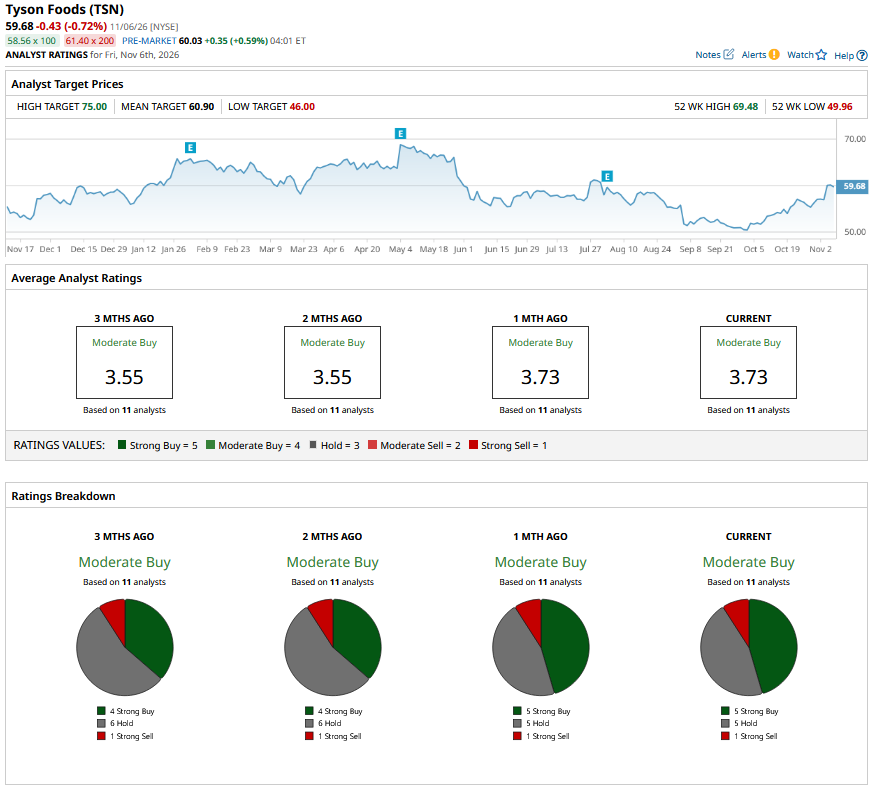
The configuration has turned bullish over the past months, as the company now has five Strong Buy ratings, up from only four two months ago.
On Sept. 5, Barclays analyst Benjamin Theurer maintained a “Buy” rating on Tyson Foods and set a price target of $75.
TSN’s mean price target of $60.90 represents a 2% premium over the current market price. Its Street-high target of $75 implies a 25.7% upside from current levels.
On the date of publication, Aritra Gangopadhyay did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.