


EN
Dividend Increase Might Change The Case For Investing In Associated Banc Corp Stock
- Associated Banc-Corp's board recently approved a higher regular quarterly cash dividend of $0.25 per common share, alongside scheduled Series E and Series F preferred stock dividends, all payable on December 15, 2026 to shareholders of record on December 1, 2026.
- The richer common payout signals how management currently balances capital between growth initiatives such as higher yield commercial lending and cash returns to investors, which matters for anyone tracking Associated Banc-Corp's balance sheet remix and acquisition integration goals.
- We will now look at how Associated Banc-Corp's higher common dividend payout could influence the existing investment narrative around capital deployment.
Associated Banc-Corp Investment Narrative Recap
To own Associated Banc-Corp, you need to be comfortable with a bank that is leaning into higher yielding commercial and industrial lending while integrating American National and scaling fee businesses. The analyst consensus Narrative on Simply Wall St frames the near term upside around executing on this remix without eroding credit quality or the relationship driven deposit base.
The main short term catalyst remains delivery of projected cost saves and revenue benefits from the American National deal alongside stable core deposit trends. The biggest current risk is that higher commercial and CRE exposure and rising noninterest expense offset these benefits. The latest dividend increase is relatively small, so the operational impact looks limited.
The common dividend move to US$0.25 per share, plus the declared Series E and Series F preferred dividends, keeps income on the table while Associated Banc-Corp focuses on balance sheet mix and integration work. Income investors now see a slightly higher cash payout, but the essential story still sits in credit discipline, deposit retention and cost control.
That is why the American National integration remains the most relevant backdrop to this dividend news. Analysts are watching whether the targeted 30% cost saves, the shift toward C&I lending and growth in fee income lines such as treasury management actually show through in reported margins. Any shortfall here would matter more for the investment case than a one cent dividend change.
Associated Banc-Corp's current analyst storyline points to US$2.2b in revenue and US$714.1m in earnings by 2029, based on revenue growing 11.8% a year and earnings rising about US$222.5m from the US$491.6m recorded today.
Uncover how Associated Banc-Corp's fair value indicates a 13% potential upside to its current price before the discount gap closes.
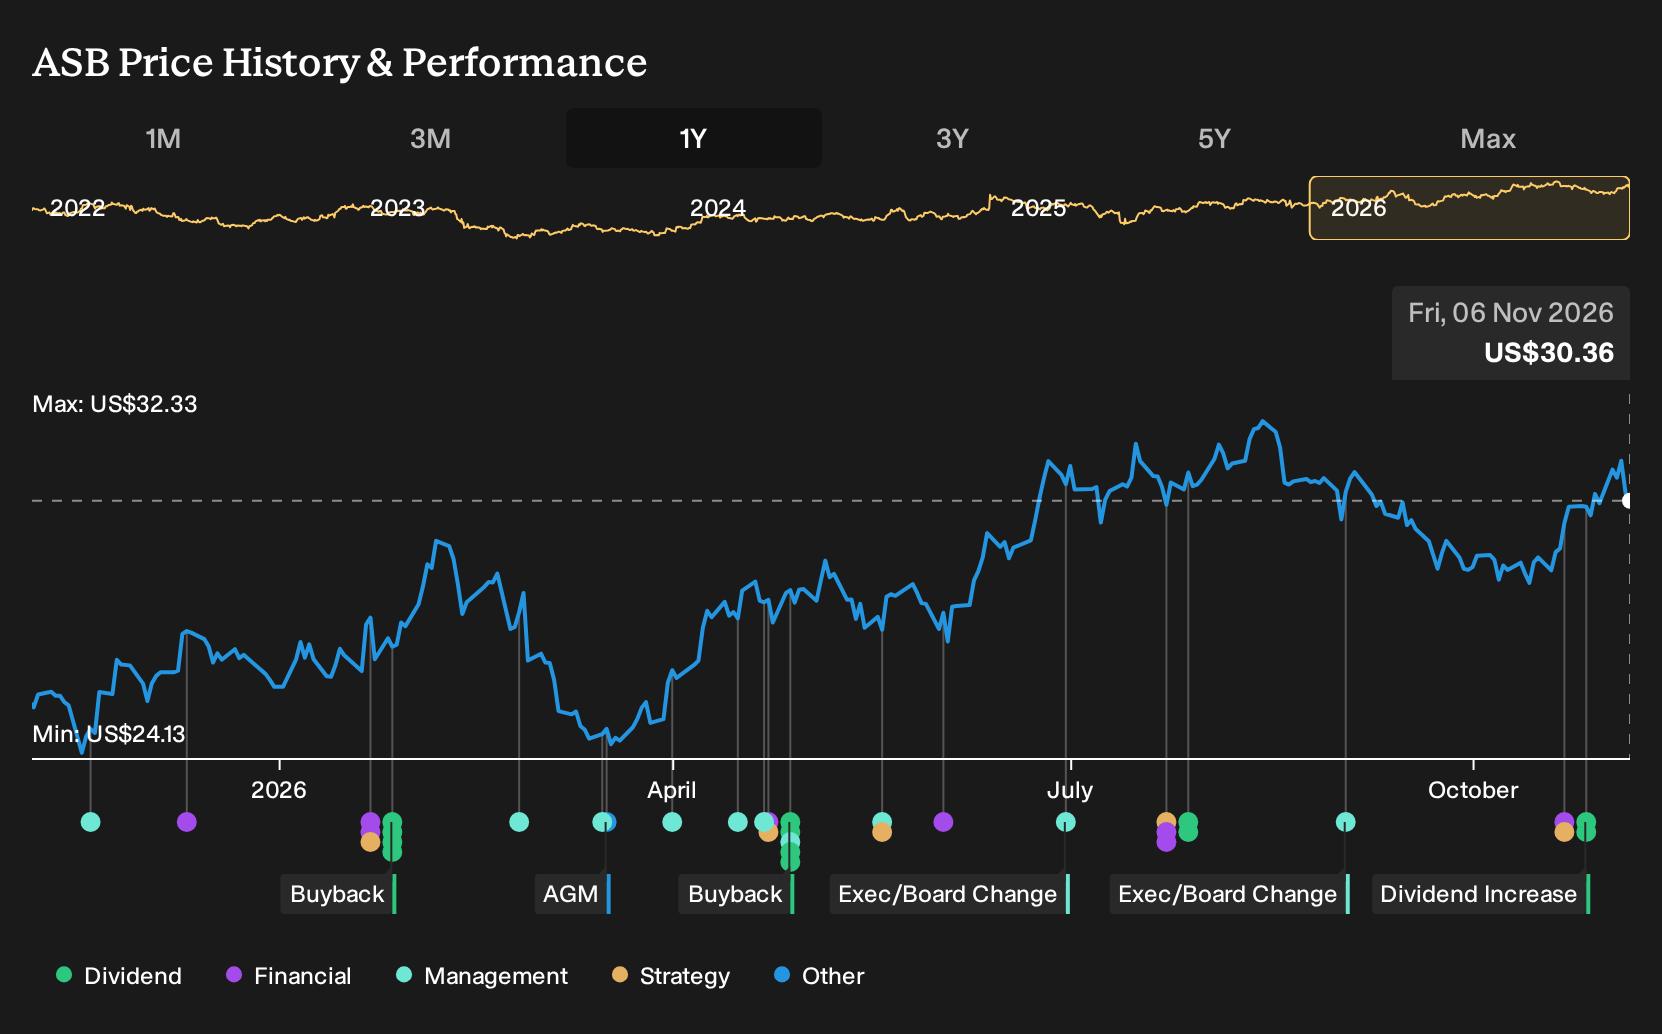
Exploring Other Perspectives
The Simply Wall St Community currently offers 2 fair value views on Associated Banc-Corp, stretching from about US$34.30 to roughly US$51.41 per share, which shows how far apart private estimates can land. You can weigh those opinions against risks around higher commercial and CRE exposure, or catalysts tied to fee income build out and American National integration.
Explore another Associated Banc-Corp fair value estimate, including one that suggests as much as 69% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Associated Banc-Corp research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Associated Banc-Corp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Associated Banc-Corp's overall financial health at a glance.
Looking For More Investment Ideas Beyond Associated Banc-Corp?
If you want to stress test your thesis on Associated Banc-Corp and broaden your watchlist, the Simply Wall St Screener can help you line up other candidates that match your income, quality or risk appetite.
- For investors who care most about steady income, compare Associated Banc-Corp's payout profile with a curated 7 dividend fortresses that focus on sizeable yields.
- If capital preservation and smoother return profiles matter more to you, weigh this bank against a 31 resilient stocks with low risk scores that currently screen well on resilience.
- For readers hunting for fresh ideas beyond well covered tickers, broaden your research with a 19 high quality undiscovered gems that pair solid fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com