


EN
Nokian Renkaat Oyj (HLSE:TYRES) After Strong Results And Higher Outlook, Is It Fully Valued?
Why Nokian Renkaat Oyj Stock Is Back on Investors’ Radar
Nokian Renkaat Oyj (HLSE:TYRES) just posted third quarter figures that showed higher sales and net income than a year earlier, and lifted full year 2026 guidance on net sales and operating profitability.
The upbeat earnings and raised outlook have arrived after a mixed stretch for Nokian Renkaat Oyj’s share price. The stock is up 47.46% year to date and has a 1-year total shareholder return of 74.05%, while the 5-year total shareholder return is still down 45.65%, so momentum looks to be rebuilding from a low base.
Scan beyond Nokian Renkaat Oyj to see how other hand-picked industrials are pricing in earnings momentum with the 225 high quality undervalued stocks.
Nokian Renkaat Oyj has just delivered stronger earnings and lifted its 2026 targets, yet the share price is already up sharply this year. Is the better move leaning in now, or waiting for a calmer entry point as valuation comes into focus?
Most Popular Narrative: 6.7% Overvalued
Nokian Renkaat Oyj closed at €14.23 compared with a narrative fair value of €13.33, which the analyst consensus Narrative on Simply Wall St derives using an 8.38% discount rate and detailed revenue and earnings forecasts.
The long term goal to reach €1.8b to €2b net sales with segment EBITDA above 24% and segment operating profit above 15% by 2029 requires a large uplift from a Q1 2026 segment EBITDA margin of 10.8%. Any slowdown in execution on price mix or efficiency plans would leave earnings and return metrics short of current expectations.
See why 3 investors see Nokian Renkaat Oyj as 7% overvalued.
Result: Fair Value of €13.33 (OVERVALUED)
Still, if Nokian Renkaat Oyj sustains a higher value tyre mix and continues tightening costs, earnings and margins could move closer to the long term targets.
Find out about the key risks to this Nokian Renkaat Oyj narrative.
Another View on Nokian Renkaat Oyj’s Valuation
There is a different read from the SWS DCF model. On those cash flow assumptions, Nokian Renkaat Oyj at €14.23 screens about 13.1% below an estimated value of €16.37, which points to undervaluation rather than a premium price.
Put the cash flow lens under the microscope with the Look into how the SWS DCF model arrives at its fair value..
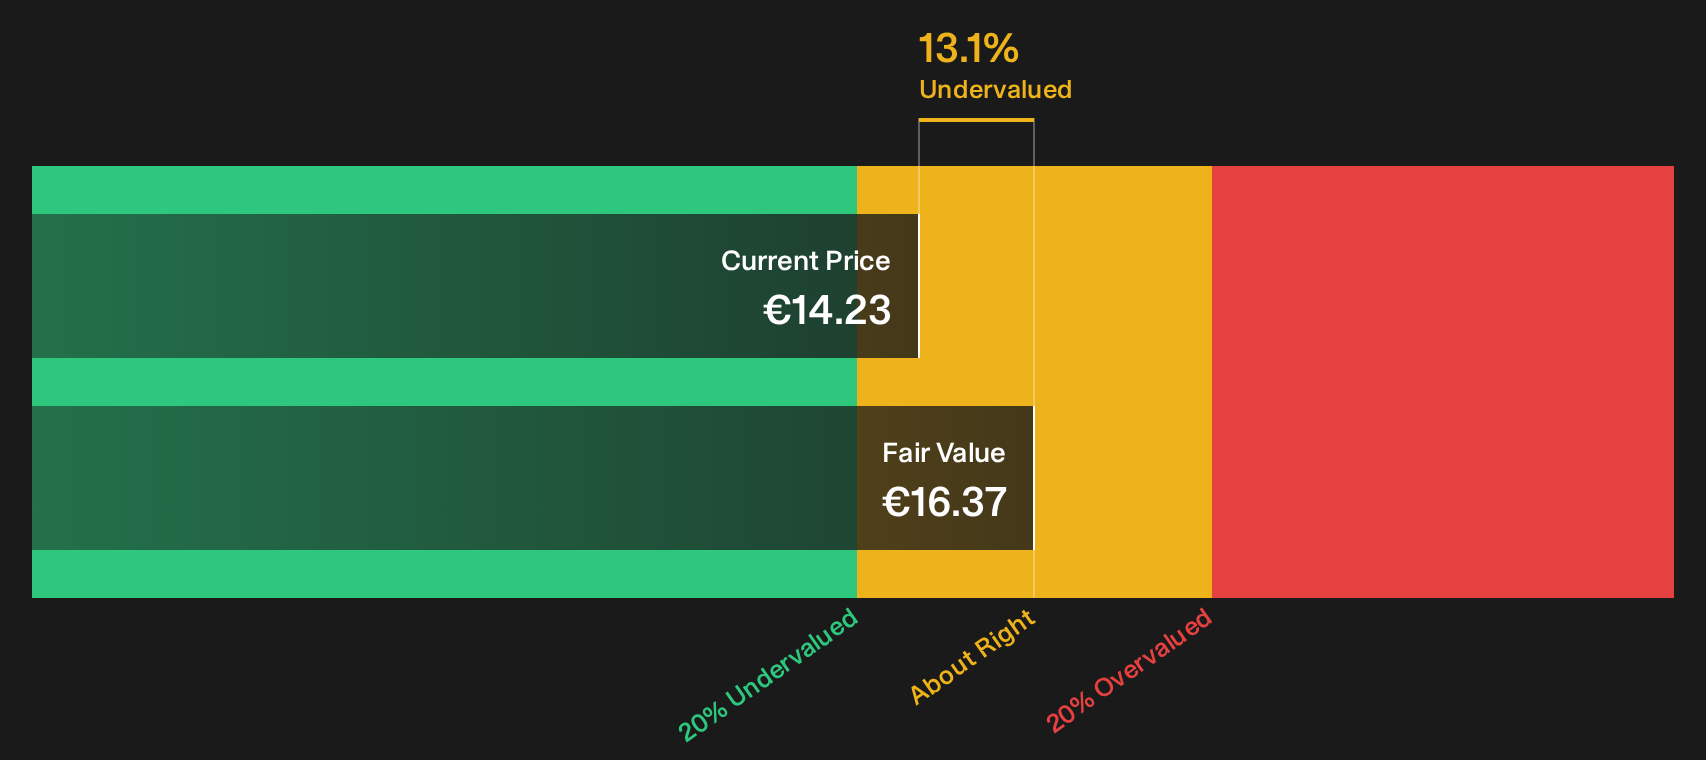
With one method flagging the shares as overvalued and another suggesting upside to €16.37, which yardstick do you trust more for your own framework?
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nokian Renkaat Oyj for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 225 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals around Nokian Renkaat Oyj leave you torn, that is exactly when it helps to move fast and dig into the underlying data yourself, then weigh the risks and potential upsides flagged by our 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Nokian Renkaat Oyj?
If you are serious about building a stronger portfolio, do not stop at Nokian Renkaat Oyj when the rest of the market is full of mispriced opportunities.
- Target dependable income streams by reviewing a curated set of high-yield opportunities through the 226 dividend fortresses.
- Hunt for quality at a discount by scanning companies that look fundamentally mispriced using the 225 high quality undervalued stocks.
- Protect your downside first by focusing on financially resilient businesses through the 207 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com