


EN
Boot Barn Holdings (BOOT) Could Be 28% Undervalued After Strong Earnings And Growth Guidance
How the latest earnings reset the conversation around Boot Barn Holdings
Boot Barn Holdings (BOOT) just paired a strong second quarter earnings report with fresh guidance and an ambitious plan to open 75 to 80 new stores in fiscal 2027.
Sales for the quarter reached US$581.81 million compared with US$505.40 million a year earlier, while net income came in at US$52.5 million against US$42.22 million. Basic earnings per share from continuing operations were US$1.74, up from US$1.38, with diluted earnings per share at US$1.73 versus US$1.37.
Despite the upbeat guidance and store rollout plans announced on 28 October 2026, Boot Barn Holdings’ share price fell 5.66% on the day and is down 4.63% over the past week. The year to date share price return has declined 29.83% and the 1 year total shareholder return has slipped 29.99%, even though the 3 year total shareholder return remains up 89.85%. This pattern suggests long term holders are still ahead, but recent momentum has faded as investors reassess how much risk they are willing to take on future execution.
Spot opportunities that are similar to Boot Barn Holdings’ growth story by checking out a curated list of retailers showing strong fundamentals in our list of solid balance sheet and fundamentals (25 results).Boot Barn Holdings just delivered higher sales, earnings and fresh expansion plans, yet the share price pulled back. Is the latest drop about business fundamentals or a mood swing in how the market is pricing that story?
Most Popular Narrative: 28% Undervalued
On the latest numbers, the analyst consensus Narrative on Simply Wall St marks Boot Barn Holdings’ fair value at about $180.67 compared with a last close of $130.96. That gap frames the current pullback as a valuation debate rather than a clean verdict on the earnings print.
The main thing that has to go right is that new stores, exclusive-brand penetration, digital channels and the work and B2B categories continue to generate attractive economics despite higher occupancy and distribution costs and pockets of softer Western demand.
The current valuation implies that the market is still discounting the scale of Boot Barn Holdings' long-term store growth, merchandise margin expansion and earnings power. This makes the stock look undervalued and supports a bullish view.
See why 11 investors see Boot Barn Holdings as 28% undervalued.
Result: Fair Value of $180.67 (UNDERVALUED)
Still, the Boot Barn Holdings story can crack if aggressive store openings strain returns, or if softer Western demand lingers and drags on same store sales.
Find out about the key risks to this Boot Barn Holdings narrative.
Another View on Boot Barn Holdings’ Valuation
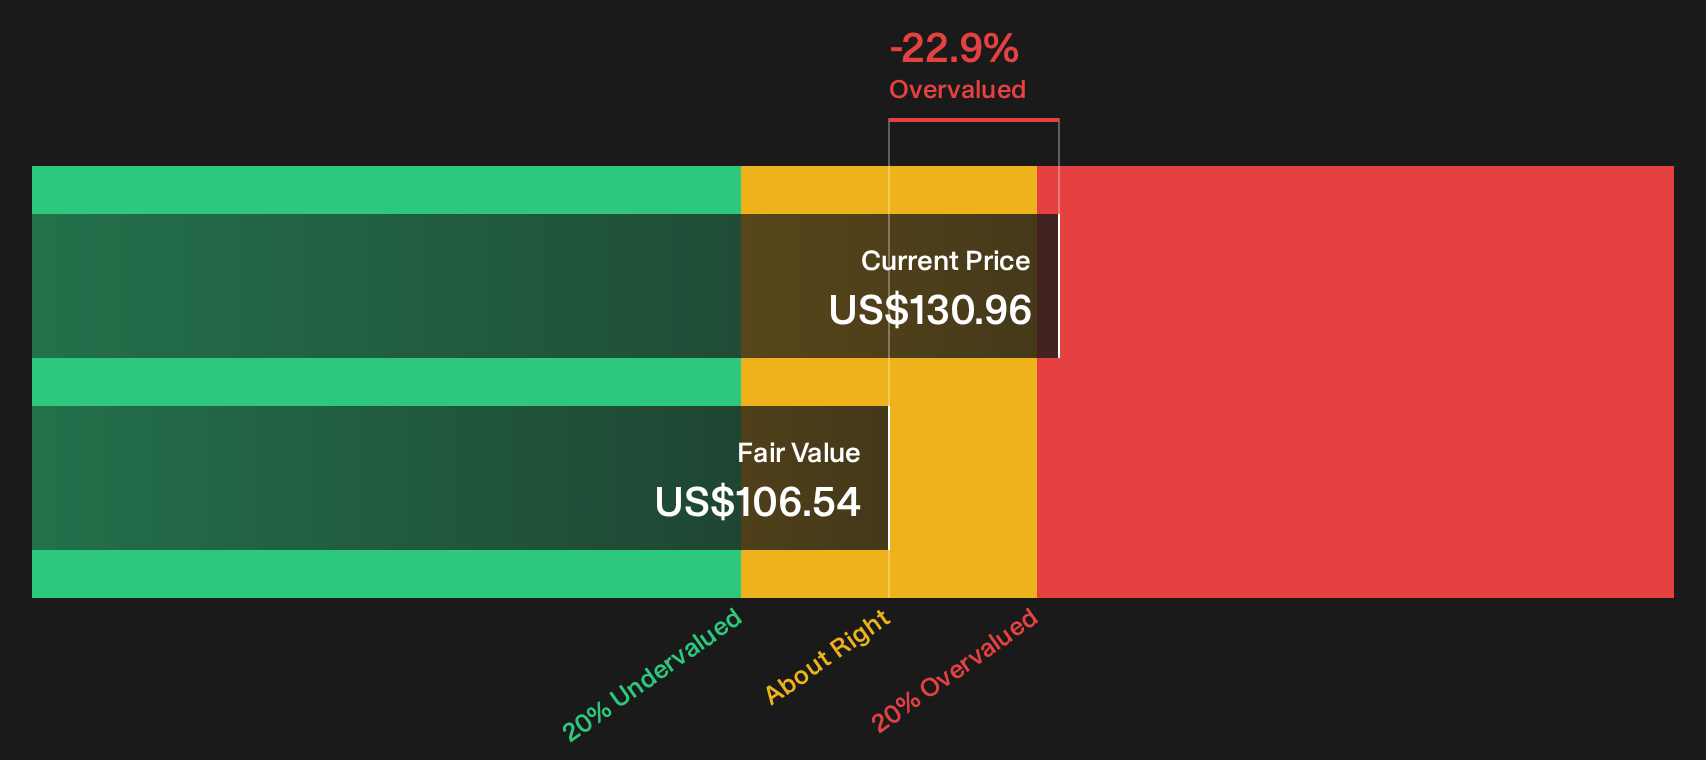
The analyst narrative frames Boot Barn Holdings as about 28% undervalued based on a fair value of $180.67, yet the SWS DCF model points the other way. On that future cash flow view, the stock at $130.96 sits above an estimated value of $106.54, which signals an overvalued outcome instead.
That gap matters. One approach leans on earnings forecasts and target P/E multiples; the other focuses on projected cash generation and discount rates. When two frameworks disagree this clearly, it prompts a practical question for investors: Which set of assumptions about Boot Barn Holdings feels more realistic?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Feeling unsure which story to trust around Boot Barn Holdings right now is natural, especially with sentiment pulling in different directions. Act while the details are fresh in mind and weigh the upside drivers for yourself by checking the 3 key rewards.
Looking for more investment ideas beyond Boot Barn Holdings?
If Boot Barn Holdings has you thinking harder about risk and reward, do not stop there. Put that same energy to work across a broader watchlist.
- Target resilient compounders by scanning companies with steady finances and room to grow using the 40 high quality undervalued stocks.
- Focus on capital preservation first and hunt for stability with the 31 resilient stocks with low risk scores.
- Aim for quality and strength in the balance sheet by reviewing the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com