


EN
Piper Sandler Companies (PIPR) Could Be 12% Below Fair Value After Mixed Earnings
Piper Sandler Companies (PIPR) drew fresh investor focus after third quarter 2026 results showed softer quarterly earnings, higher year-to-date revenue and profit, a new buyback authorization, and a maintained dividend.
Piper Sandler Companies shares closed at US$65.92 after the earnings, with the one day share price return declining 1.82% and the 7 day share price return down 2.22%, while the 30 day share price return is up 0.98% and the 90 day share price return has fallen 12.93%.
That short term softness sits against a year to date share price return that is down 24.66% and a 1 year total shareholder return that has declined 19.26%. At the same time, the 3 year total shareholder return is up 97.11% and the 5 year total shareholder return is higher by 67.32%, so recent weakness contrasts with much stronger long term results.
Compare Piper Sandler Companies with a curated set of financial firms that also pair shareholder returns with disciplined balance sheets through the list of solid balance sheet and fundamentals (25 results).
After a sharp pullback from stronger multi year returns, investors now have to judge Piper Sandler Companies on today’s earnings power and capital returns. Is most of the upside already cashed in, or is there more ahead at this valuation?
Most Popular Narrative: 12% Undervalued
On the analyst consensus Narrative on Simply Wall St, Piper Sandler Companies screens as undervalued, with a fair value of $74.75 against the last close at $65.92. That view leans heavily on how deal activity, sector coverage and funding needs could shape earnings over time.
Rising consolidation among US banks and related balance sheet restructurings are creating more complex M&A and fixed income assignments. This can support advisory and trading revenues as Piper Sandler advises on both bank deals and associated balance sheet repositioning.
See why 1 investors see Piper Sandler Companies as 12% undervalued.
Result: Fair Value of $74.75 (UNDERVALUED)
Still, if equity and M&A activity slow or compensation creeps higher, the Piper Sandler Companies recovery narrative that underpins the 12% undervaluation can crack.
Find out about the key risks to this Piper Sandler Companies narrative.
Another View on Piper Sandler Companies Valuation
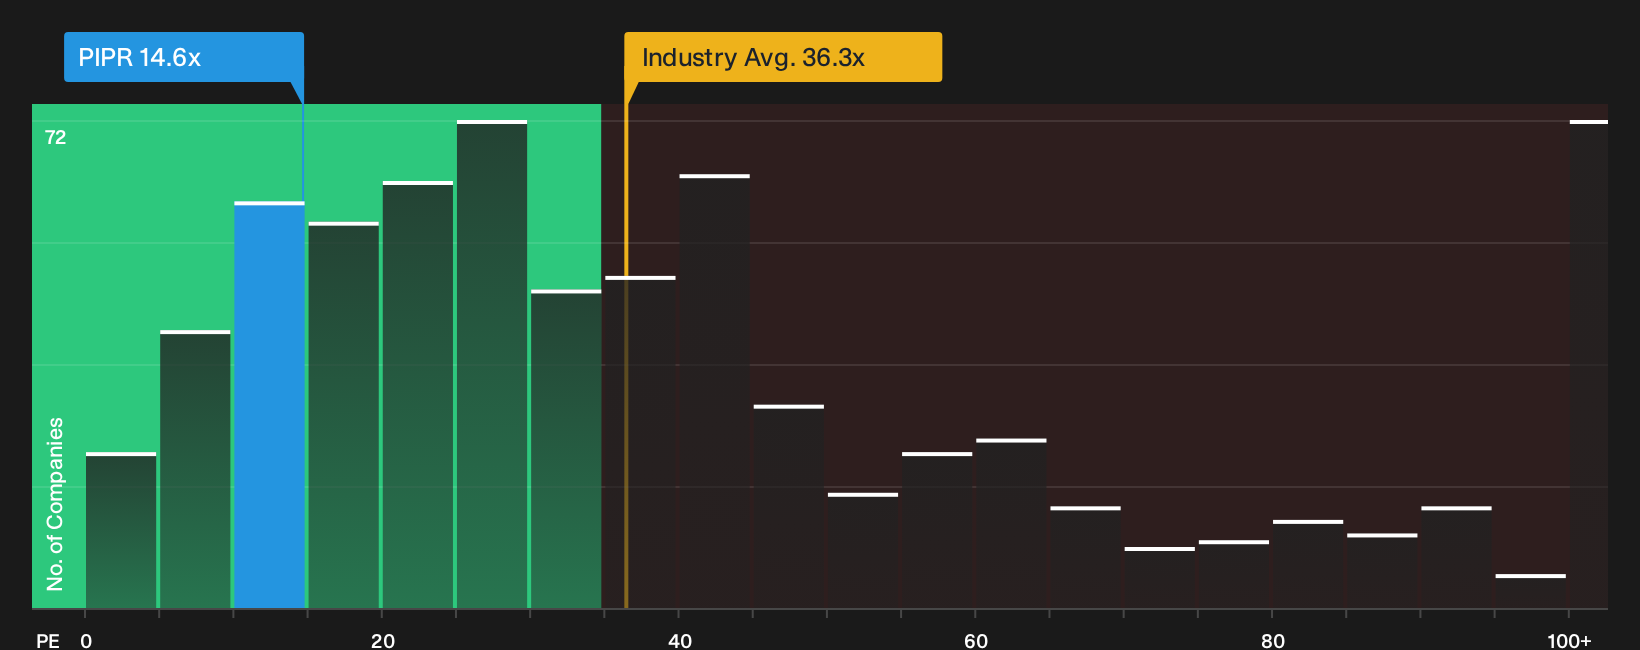
On plain P/E math, Piper Sandler Companies looks cheaper than peers, but not cheap against its own fair ratio. The stock trades at 14.6x earnings versus a peer average of 17.5x, yet the estimated fair ratio is 11.7x, which suggests less of a clear bargain and more of a debate about how much quality you are paying for.
That gap can cut both ways. It may reflect room for the share price to move toward peer levels if execution holds, or it could highlight downside risk if the multiple reverts toward the fair ratio. Which outcome do you think current earnings power truly supports?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Piper Sandler Companies can feel confusing. Move quickly to review the full picture and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Piper Sandler Companies?
If Piper Sandler Companies has sharpened your focus on valuation and quality, do not stop here. Broaden your watchlist now using targeted screeners built for this kind of market.
- Prioritize resilience by reviewing a curated 31 resilient stocks with low risk scores that can help you focus on businesses with steadier risk profiles when conditions change.
- Hunt for potential value by scanning a 40 high quality undervalued stocks that flags companies where pricing and fundamentals tell a different story to the market.
- Target cash returns by checking a 7 dividend fortresses that filters for higher yielding payers with the income profile you want.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com