


EN
Paylocity Holding (PCTY) Raises Outlook As AI Growth Puts Fair Value In Focus
Why Paylocity’s Latest Quarter Matters For Investors
Paylocity Holding (PCTY) just posted first quarter fiscal 2027 results that topped its own guidance, paired with a higher full year outlook tied to growing use of its AI driven HR tools.
The fresh guidance for second quarter and full year fiscal 2027 now anchors the conversation around Paylocity, with investors weighing double digit revenue and profit growth against a stock that has lagged over the past five years.
Recent price action shows momentum rebuilding. The 30 day share price return of 12.46% and 90 day gain of 19.37% contrast with a 5 year total shareholder return that is down 34.63%. At the same time, the latest quarterly beat and higher guidance have refocused attention on Paylocity Holding’s AI driven model and perceived risk profile.
Capitalize on the renewed focus on Paylocity Holding’s AI tools by scanning a curated group of peers with strong automation and software economics using 42 profitable AI stocks that aren't just burning cash.The recent jump in Paylocity Holding’s share price still leaves a wide gap between the current US$173 level, analyst targets near US$190, and some models implying a far steeper discount. Which anchor looks closer to fair value?
Most Popular Narrative: 3.2% Undervalued
Against the last close at $173.15, the analyst consensus Narrative on Simply Wall St pins Paylocity Holding’s fair value at $178.85. This frames the stock as modestly discounted while hinging a lot on how its AI driven platform and cross sell engine perform over time.
Expansion of Paylocity Holding’s unified HR, finance and IT platform with embedded AI agents such as Ignite AI and the AI assistant, along with planned premium SKUs tied to tools like Grayscale and Aidora, is set up to convert rising AI usage into higher recurring revenue and average revenue per client over time, which can support earnings growth.
Broader adoption of adjacent offerings including Paylocity for Finance, Elevate managed services, Paylocity Retirement and IT asset and access management, on top of a client base of about 44,400 organizations and revenue retention above 92%, gives the company more modules to cross sell which can lift ARPU and operating margins.
See why 11 investors see Paylocity Holding as 3% undervalued.
The Narrative uses a 7.48% discount rate and assumes revenue growth of roughly 7.38% a year with profit margins reaching 18.51%. As a result, the modest 3.2% discount to fair value depends on Paylocity converting its AI tools, cross sell and capital returns into the earnings and cash flows embedded in those forecasts.
Result: Fair Value of $178.85 (UNDERVALUED)
Still, the narrative around Paylocity Holding could crack if slower guided revenue trends persist or if AI add ons and premium SKUs see weaker than expected uptake.
Find out about the key risks to this Paylocity Holding narrative.
Another View: Paylocity Looks Expensive On Earnings
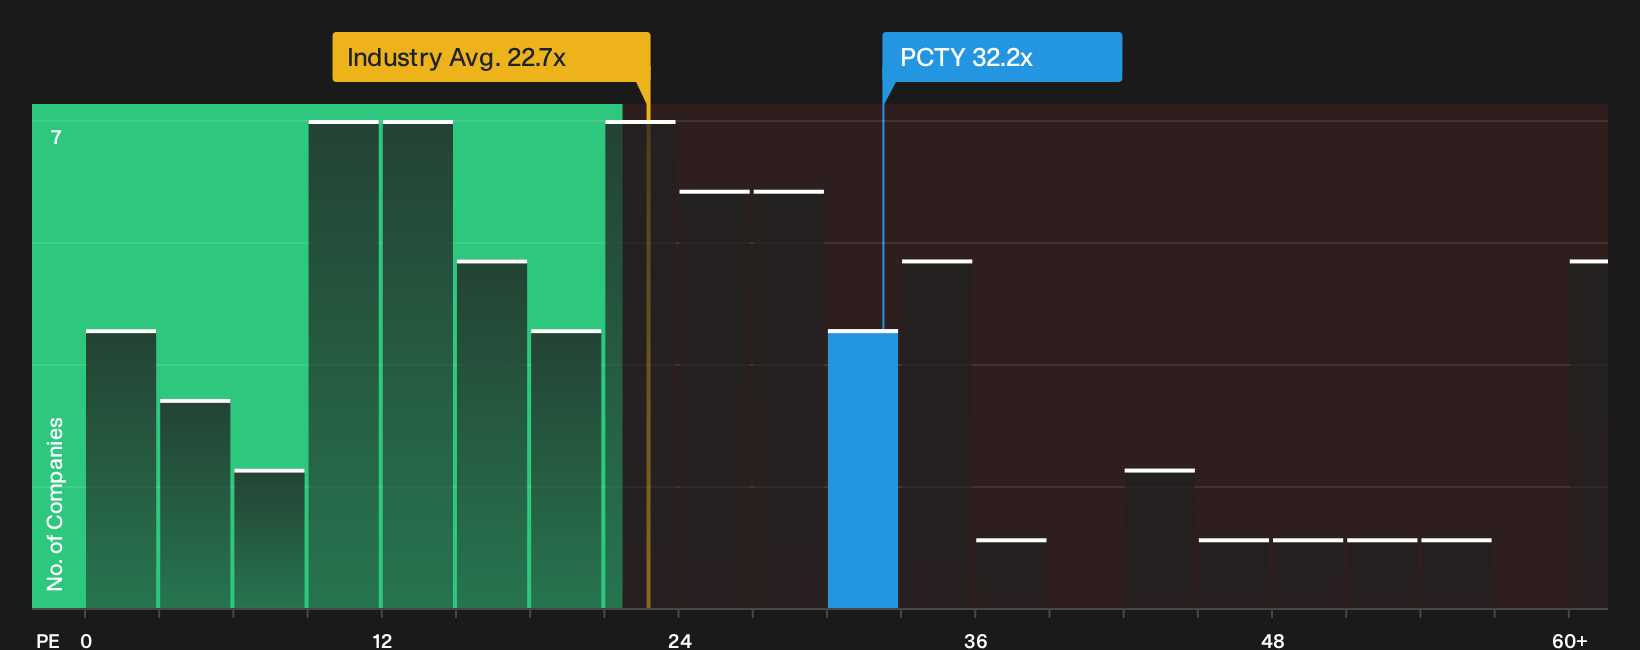
There is a different read on Paylocity. On current numbers the stock trades at a P/E of 32.2x, while the US Professional Services industry sits at 22.7x and close peers average 20.4x. The Simply Wall St fair ratio is 22.3x, which flags valuation risk if sentiment cools.
That gap means investors are already paying up for execution on AI, cross sell and margins before it shows up in reported results. It raises a simple question for anyone tracking Paylocity Holding: Are you comfortable underwriting that premium if growth or AI adoption land closer to the lower end of expectations, or do you prefer to wait for the market to move nearer to the fair ratio first?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Paylocity Holding’s valuation and execution can feel messy. Pull up the data, pressure test the assumptions, and ground your own thesis using 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Paylocity?
Do not stop with Paylocity Holding. Broaden your opportunity set by stress testing your thesis against other listed companies that match clear, disciplined filters on fundamentals and risk.
- Target potential mispricings by scanning for quality companies trading at a discount using the 40 high quality undervalued stocks.
- Prioritize resilience and capital strength by filtering for businesses with cleaner finances and sturdier funding profiles via the list of solid balance sheet and fundamentals (25 results).
- Hunt for under-the-radar opportunities with strong underlying numbers before the crowd catches up through the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com