


EN
How Investors Are Reacting To Exelon Stock As Data Center Demand Supports Guidance
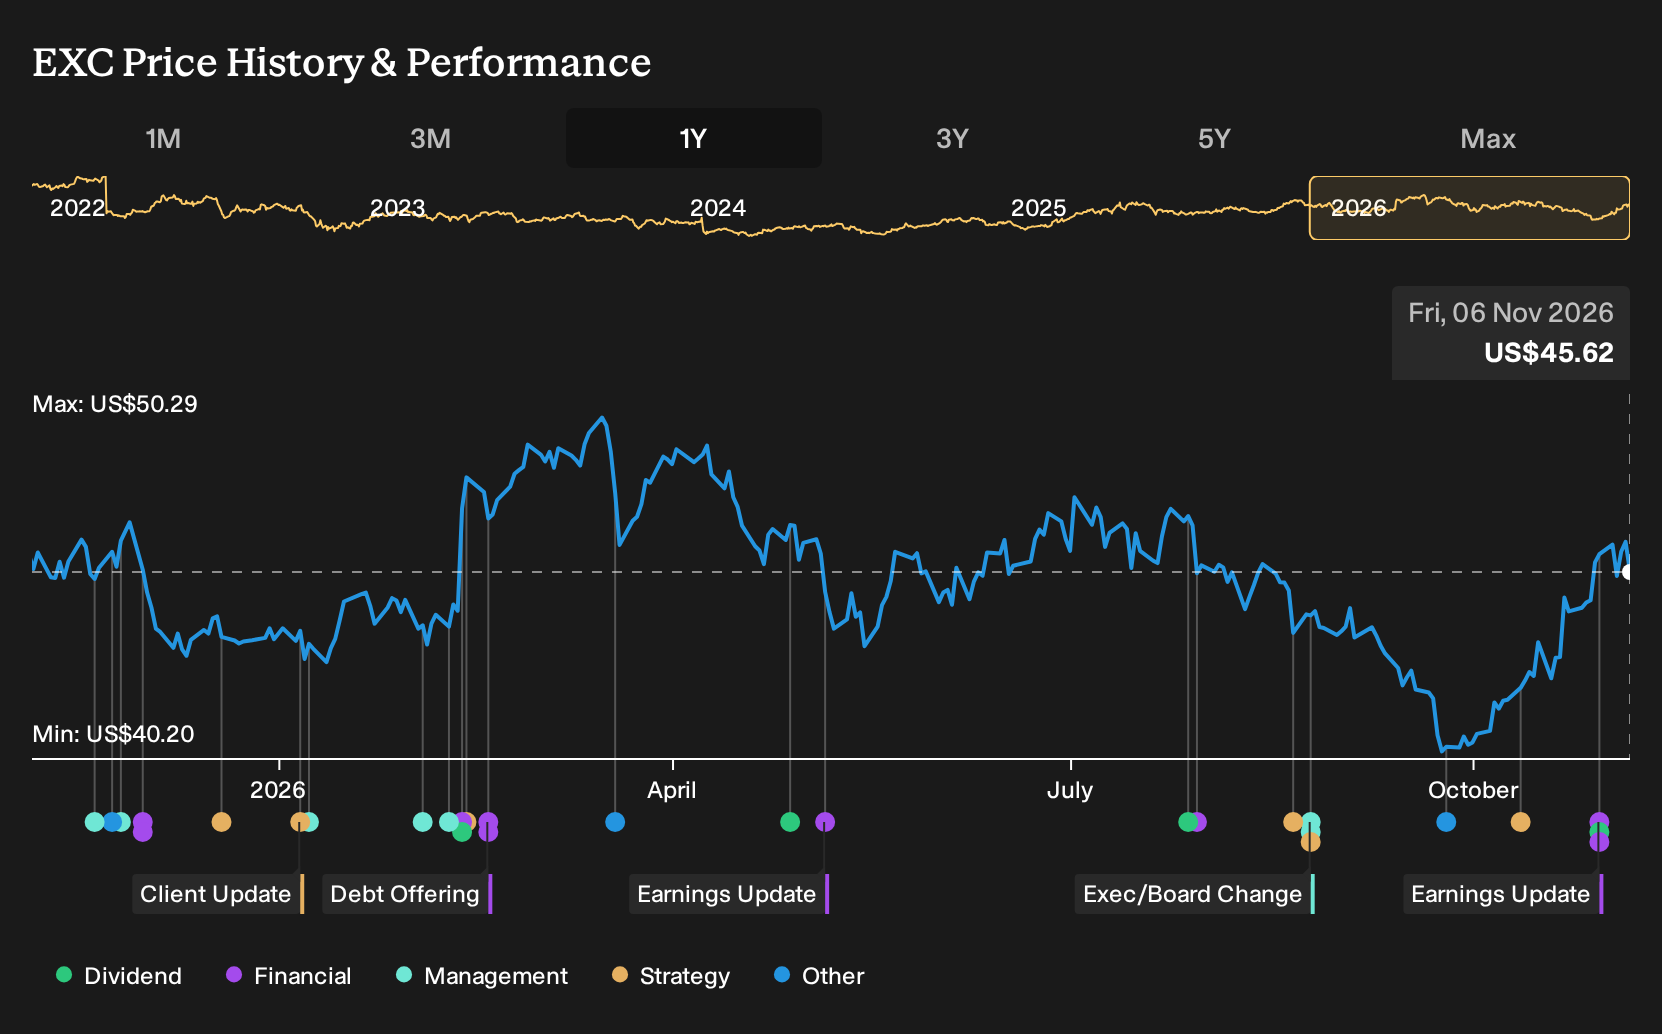
- Exelon reported third quarter 2026 revenue of US$7,319 million and net income of US$729 million, and its Board declared a regular quarterly dividend of US$0.42 per share payable on December 15, 2026.
- The utility reaffirmed its 2026 earnings guidance while highlighting about 11 GW of data center linked grid projects backed by over US$1b of customer collateral.
- We will look at how Exelon’s investment narrative is shaped by reaffirmed earnings guidance alongside growing data center driven grid demand.
Scan how Exelon’s data center driven grid projects compare with other potential power beneficiaries by reviewing the hand picked 42 power grid technology and infrastructure stocks alongside this earnings update.
Exelon Investment Narrative Recap
To own Exelon, you need to believe in a long, regulated build out of transmission and grid upgrades tied to rising large load demand, especially data centers, while the analyst consensus Narrative on Simply Wall St assumes operating EPS growth supported by this capex. The latest quarter shows higher revenue but lower net income and EPS versus last year, so execution rather than headline growth sits at the center of the near term story.
The reaffirmed 2026 earnings guidance signals that management views the current year as on track despite softer quarterly profitability. The key near term catalyst remains converting the roughly 11 GW of high probability data center related projects into timely, regulator approved rate base growth. The main risk is still regulatory and affordability pressure that could slow or resize that US$41.7b capital plan and squeeze returns.
The most relevant new data point is Exelon reaffirming operating EPS compounded annual growth near the top end of 5% to 7% from 2025 to 2029. That sits directly against a quarter where net income and per share earnings declined year on year, so investors have to reconcile current margin pressure with management’s confidence in the long range program.
This guidance ties back to the catalysts already in play, including transmission heavy spending, screened data center interconnection demand backed by over US$1b of collateral, and efforts to cap adjusted O&M growth. If Exelon executes on those investment and cost plans while handling regulatory scrutiny over affordability, that guidance range becomes a useful reference point rather than just an aspirational target.
Exelon's current analyst framework points to revenue of US$27.8b and earnings of US$3.6b by 2029, underpinned by forecast top line growth of 3.2% per year and an increase in earnings from US$2.8b today to US$3.6b, representing a US$0.8b uplift.
Uncover why Exelon's fair value indicates a 4% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$12.73 to US$47.59 per share, so retail views on Exelon are already wide even before the latest earnings, guidance reaffirmation and dividend news. Regulatory pushback on affordability and the large US$41.7b grid plan provide strong reasons to compare more opinions.
Explore another Exelon fair value estimate, including one that suggests as much as 72% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Exelon research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Exelon. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Exelon's overall financial health at a glance.
Looking for more investment ideas beyond Exelon?
Once you have formed a view on Exelon, it can help to broaden the watchlist with other companies that line up with your risk tolerance and return goals. The Simply Wall St Screener lets you filter by balance sheet strength, income potential, or mispriced opportunities so you can apply the same level of discipline across the rest of your portfolio.
- For investors who want income to feel sturdier, consider screening for companies that look like potential income workhorses by reviewing 7 dividend fortresses.
- If capital preservation is the first priority, narrow your focus to businesses with stronger financial footing by working through a list of solid balance sheet and fundamentals (25 results).
- For those hunting for overlooked opportunities with solid fundamentals, cast a wider net across 19 high quality undiscovered gems that may not yet be on every investor's radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com