


EN
Agree Realty (ADC) Gets A Buy Lift, Is It Still 10% Undervalued?
Agree Realty event puts income focus in the spotlight
Argus recently lifted its rating on Agree Realty (ADC) to BUY, putting fresh attention on this net lease REIT just as income investors compare it with peers like Realty Income.
For readers weighing long term cash flow, the contrast between a retiree swapping Realty Income for Agree Realty and the analyst upgrade sets up a clear question. How does this REIT’s income profile stack up relative to its current share price near US$69.87 and its recent return pattern over the past month and past 3 months?
Agree Realty’s share price has drifted over the past year, with a year-to-date share price return that is down 3.12%. However, the recent 30-day share price return of 5.94% hints at improving momentum as income-focused headlines and rating upgrades refocus attention on the stock.
Compare Agree Realty with a curated group of income-focused peers by scanning our hand picked 7 dividend fortresses for potential alternatives in the same high-yield corner of the market.
Agree Realty has climbed in the past month while still trading below both analyst targets and intrinsic value estimates. Does that gap signal a reasonable entry for its income stream, or a valuation trap forming after the bounce?
Most Popular Narrative: 10% Undervalued
Agree Realty’s last close at $69.87 sits below the analyst consensus Narrative fair value of $77.75. This estimate uses an 8% discount rate to weigh future cash flows against today’s price.
Record capital deployment in Q2 2026 of more than US$500 million across acquisitions, development and developer funding, together with higher 2026 investment guidance of US$1.6 to US$1.8 billion and a medium term goal of at least US$250 million of annual development and developer funding commencements, points to a wider asset base that can support higher rental revenue and AFFO over time.
See why 121 investors see Agree Realty as 10% undervalued.
Result: Fair Value of $77.75 (UNDERVALUED)
Still, the bullish Agree Realty story can crack if higher funding costs persist, or if construction inflation squeezes returns on new developments and slows deal flow.
Find out about the key risks to this Agree Realty narrative.
Another View: Agree Realty on Earnings-Based Valuation
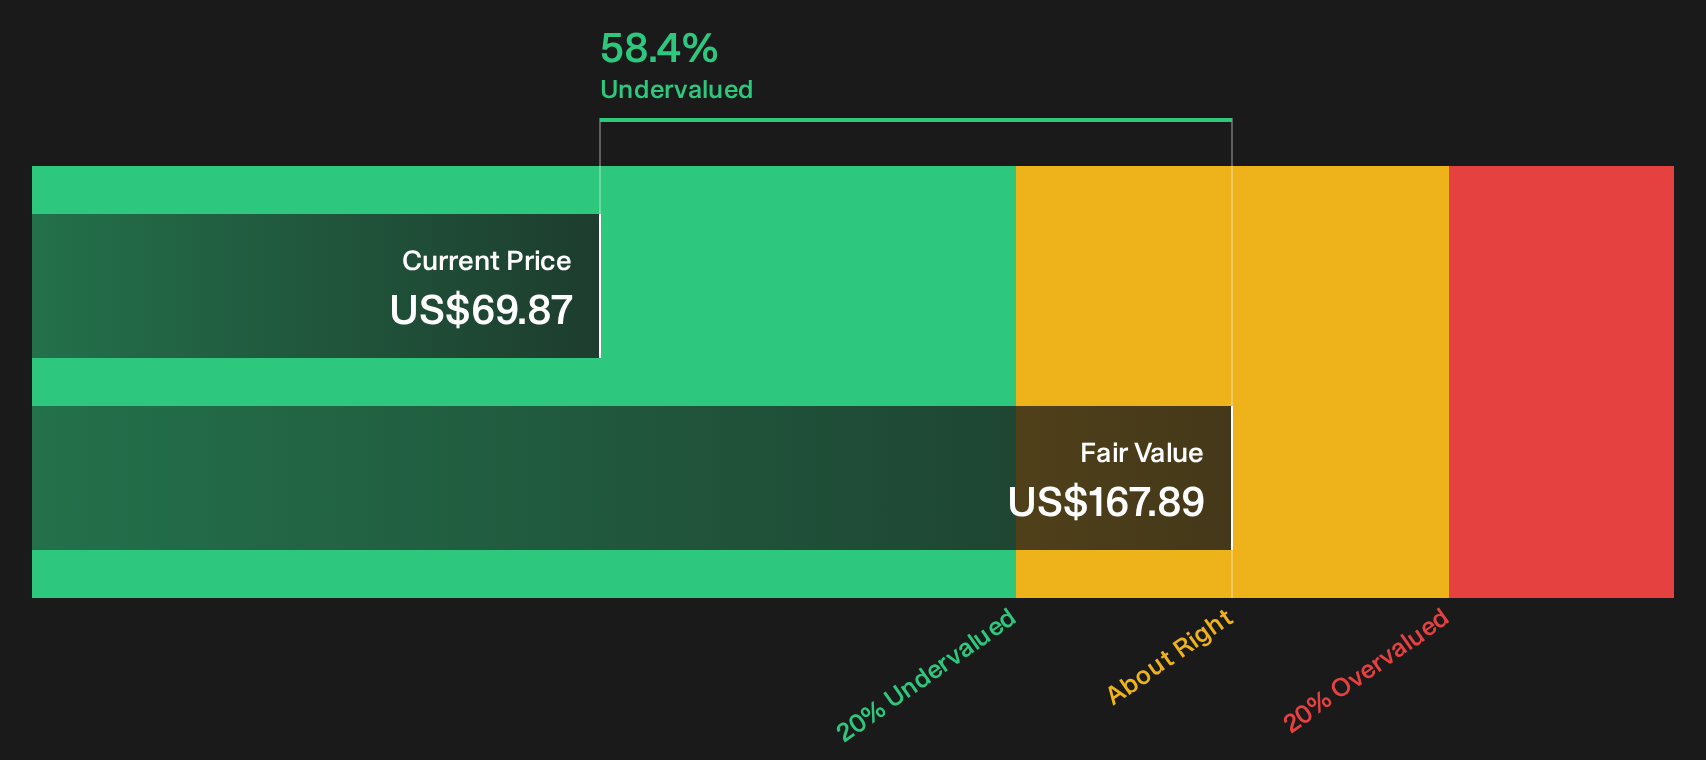
On a cash flow lens, Agree Realty screens cheap, with the stock trading at a 58.4% discount to an estimated future cash flow value of $167.89. Earnings tell a very different story. The current P/E of 38.9x is richer than both the US Retail REITs industry at 24.7x and a fair ratio of 36.4x, which points to less margin for error in the near term if growth or funding costs disappoint.
For readers weighing which signal to trust, it can help to see how the SWS DCF model connects the cash flow inputs to that $167.89 figure. It also shows what would need to change for the gap to close or stay open over time. Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on Agree Realty so far. If the blend of one or more risks and one or more rewards has you on the fence, check the underlying data and pressure test the narrative against your own criteria by reviewing 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Agree Realty?
If Agree Realty is on your radar, you can widen your opportunity set and pressure test your income thesis by comparing it with other high conviction stock ideas.
- Target dependable returns by focusing on resilient businesses through our 31 resilient stocks with low risk scores.
- Hunt for quality at a discount by scanning the 40 high quality undervalued stocks that pair strong fundamentals with appealing prices.
- Spot potential future front runners early by reviewing our 19 high quality undiscovered gems before attention and capital crowd in.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com