


EN
Paymentus Holdings (PAY) Could Be 17% Undervalued On Stronger Earnings
Paymentus Holdings earnings spark fresh look at the stock
Paymentus Holdings (PAY) just posted third quarter and nine month 2026 results, with higher sales, net income, and earnings per share from continuing operations compared with the same periods last year.
Paymentus Holdings’ recent earnings drop into a mixed price story, with the share price rising 17.56% year to date, but the 1 year total shareholder return slipping 11.43%. A 108.80% 3 year total shareholder return suggests earlier momentum that has eased back in recent months.
Seize this earnings momentum in Paymentus Holdings to scan a curated set of payment and fintech peers with resilient fundamentals through our list of solid balance sheet and fundamentals (25 results).Paymentus Holdings now pairs double digit annual growth in sales and net income with a share price that has cooled over the past year. Does that gap point to a fair deal or a rich one today?
Most Popular Narrative: 16.6% Undervalued
At a last close of $33.47 against a fair value estimate of $40.14, the analyst consensus Narrative on Simply Wall St views Paymentus Holdings as undervalued based on its long term revenue and earnings forecasts and a 7.28% discount rate.
The AI native Service Commerce stack, including patented BillWallet, Billeo and AI360 products that already show early user adoption without marketing spend, positions Paymentus Holdings to capture new software and AI driven payment use cases, which can add higher margin revenue streams and support adjusted EBITDA growth.
See why 12 investors see Paymentus Holdings as 17% undervalued.
Result: Fair Value of $40.14 (UNDERVALUED)
Still, pricing pressure from large enterprise clients and the earlier 2026 share price drop that weakened investor confidence could both challenge the Paymentus Holdings bull story.
Find out about the key risks to this Paymentus Holdings narrative.
Another view on Paymentus Holdings valuation
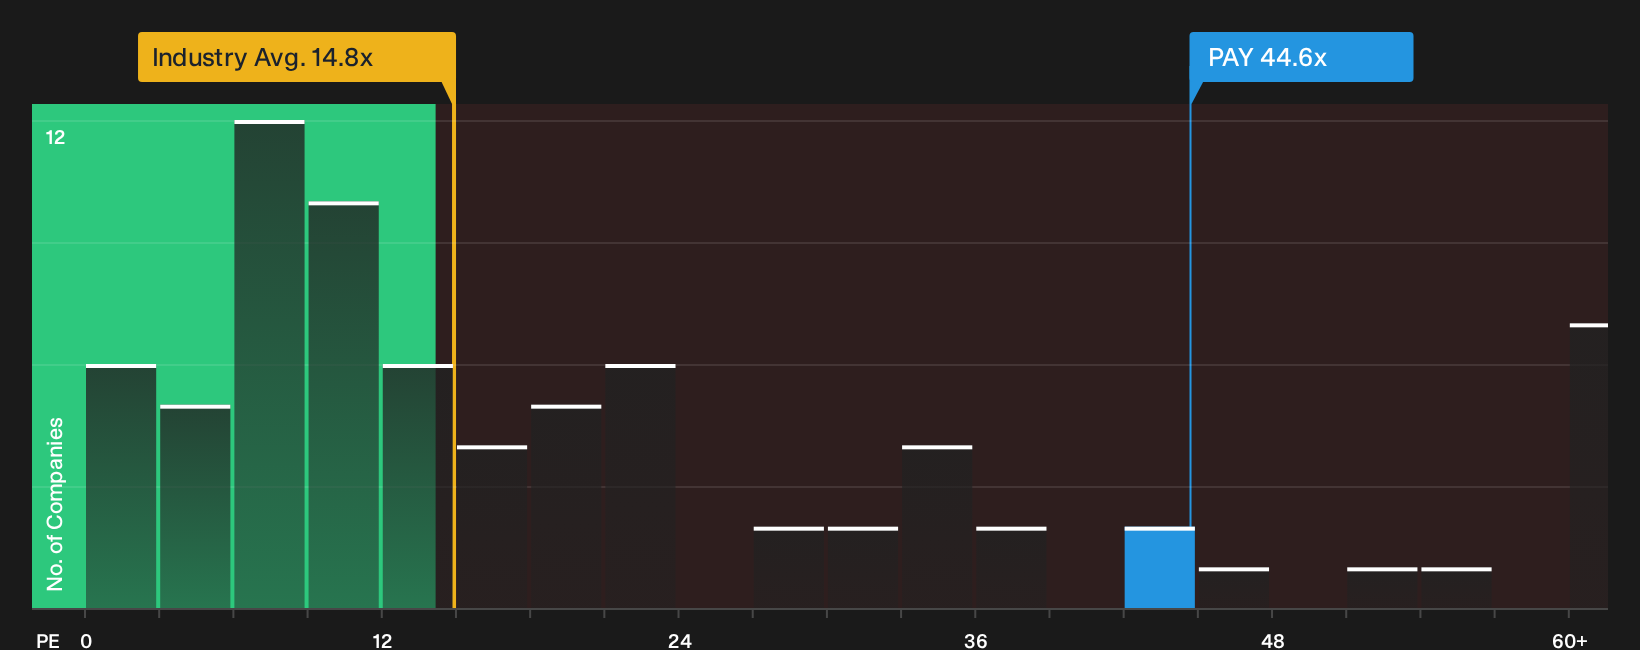
The first narrative leans on long term earnings forecasts and a $40.14 fair value. A simple P/E lens paints a sharper price tag. Paymentus Holdings trades at about 44.6x earnings, compared with 14.8x for the US diversified financials sector and a fair ratio of 16x. That kind of gap raises a basic question for investors: Is the market paying up for quality or just paying too much?
To see how those earnings multiples stack up against detailed assumptions about future cash flows and growth, it is worth lining this up against our DCF workup on Paymentus Holdings. Start with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Paymentus Holdings is split, and that is exactly why your own homework matters. Move quickly, review the full picture of its potential, and pressure test the bullish angles against the 3 key rewards.
Looking for more investment ideas beyond Paymentus Holdings?
If Paymentus Holdings has your attention, broaden your watchlist with a few focused screens that surface different types of opportunities before others spot them.
- Target resilient compounding potential by checking companies that combine quality fundamentals with attractive pricing through our 40 high quality undervalued stocks.
- Prioritise staying power and sleep-better-at-night holdings by reviewing stocks highlighted in our 31 resilient stocks with low risk scores.
- Hunt for tomorrow’s potential standouts early by scanning financially solid out-of-the-spotlight opportunities in our 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com