


EN
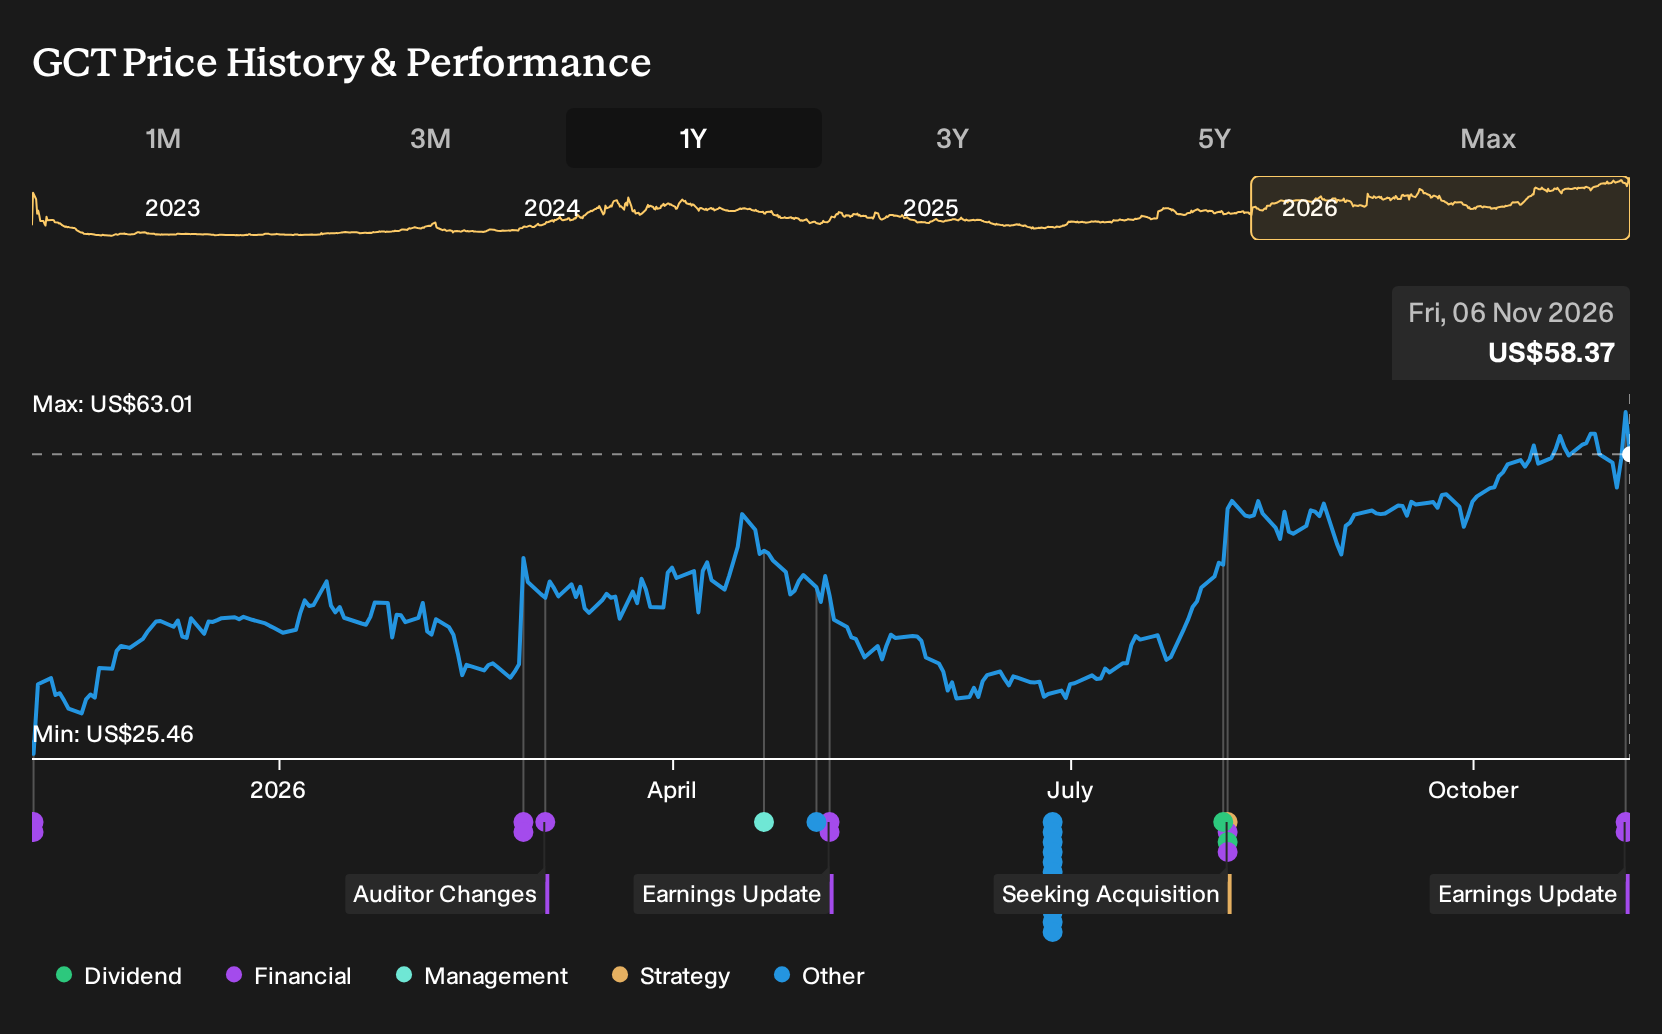
Earnings Beat May Reshape The Case For GigaCloud Technology Stock
- GigaCloud Technology reported Q3 2026 revenue of US$423.56 million and net income of US$50.61 million, alongside Q4 revenue guidance of US$425 million to US$450 million and a US$120 million share repurchase authorization.
- The combination of higher earnings per share, fresh revenue outlook and a larger buyback plan indicates management confidence in GigaCloud Technology's cash generation and operating model resilience.
- This article examines how GigaCloud Technology's reported earnings and new US$120 million repurchase plan shape the current investment narrative.
Scan beyond GigaCloud Technology and evaluate other high quality operators with strong fundamentals using our curated 19 high quality undiscovered gems as a starting universe for ideas tied to this earnings story.
GigaCloud Technology Investment Narrative Recap
To own GigaCloud Technology, you need to be comfortable with a marketplace model that leans on international expansion, especially Europe, and on steady integration of acquired portfolios. The latest Q3 2026 report, which shows higher revenue and net income versus a year ago, helps reinforce that the operating playbook can still work at the current scale.
The short term catalyst is continued stabilization at New Classic and sustained gross profit from the marketplace as Q4 2026 revenue lands within or outside the US$425 million to US$450 million range. The primary near term risk remains logistics and freight volatility, which could pressure service margins even if GMV and product revenue stay healthy.
The most relevant fresh data point is GigaCloud Technology's Q3 2026 earnings release. Management reported revenue of US$423.56 million and net income of US$50.61 million for the quarter, with basic and diluted EPS of US$1.41 from continuing operations, all higher than the prior year period.
This update feeds directly into the analyst consensus Narrative on Simply Wall St, which focuses on continued execution in Europe, network effects and acquisition integration as core drivers. Stronger recent profitability supports those themes, while investors still have to weigh governance questions and cost volatility as potential brakes on that thesis if conditions worsen.
GigaCloud Technology's current earnings sit at US$169.6 million, and analysts expect earnings to reach US$243.5 million by 2029. This implies an earnings increase of about US$73.9 million, alongside a 7.1% yearly revenue growth rate that would take revenues to US$1.9b in the same year.
Uncover why GigaCloud Technology's fair value indicates a 19% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view puts governance risk at the center for GigaCloud Technology. The most cautious analysts were penciling in 2029 earnings of about US$208.9 million on roughly US$1.9b of revenue before this Q3 report. That is a more muted storyline. Use the new figures to test which narrative you find more convincing.
Explore 3 other GigaCloud Technology fair value estimates, including one that suggests it could be worth just $69.67.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your GigaCloud Technology research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for GigaCloud Technology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate GigaCloud Technology's overall financial health at a glance.
Looking for more investment ideas beyond GigaCloud Technology?
Once you have a view on GigaCloud Technology, it can help to compare that thesis against a wider watchlist of potential opportunities. The Simply Wall St Screener lets you filter for very different profiles, from resilient balance sheets to income focused holdings and lower risk candidates.
- If you want sturdier balance sheets and cleaner fundamentals, start with a list of solid balance sheet and fundamentals (25 results) that can help you focus on financially stronger operators.
- For investors who care most about stability over excitement, scan a 31 resilient stocks with low risk scores that filters for companies with more resilient risk profiles.
- If income is your priority and you prefer yield to headlines, consider a 7 dividend fortresses that surfaces higher yielding dividend payers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com