


EN
3 Undervalued Stocks With Discounts Up To 48%
China’s producer inflation recently reached its fastest pace in nearly four and a half years, while consumer prices stayed muted. That mix of rising input costs and cautious spending can leave many shares mispriced as investors focus on headlines rather than underlying cash generation. This is where companies producing solid cash flows yet trading below estimated fair value start to look interesting. This article highlights 3 such opportunities from our cash flow valuation list.
The three stocks below are just a small sample. The full cash flow screen surfaced 434 more companies with equally compelling stories that are not covered here. To identify and analyze candidates that best fit your style, head straight into the Undervalued Stocks Based On Cash Flows screener.
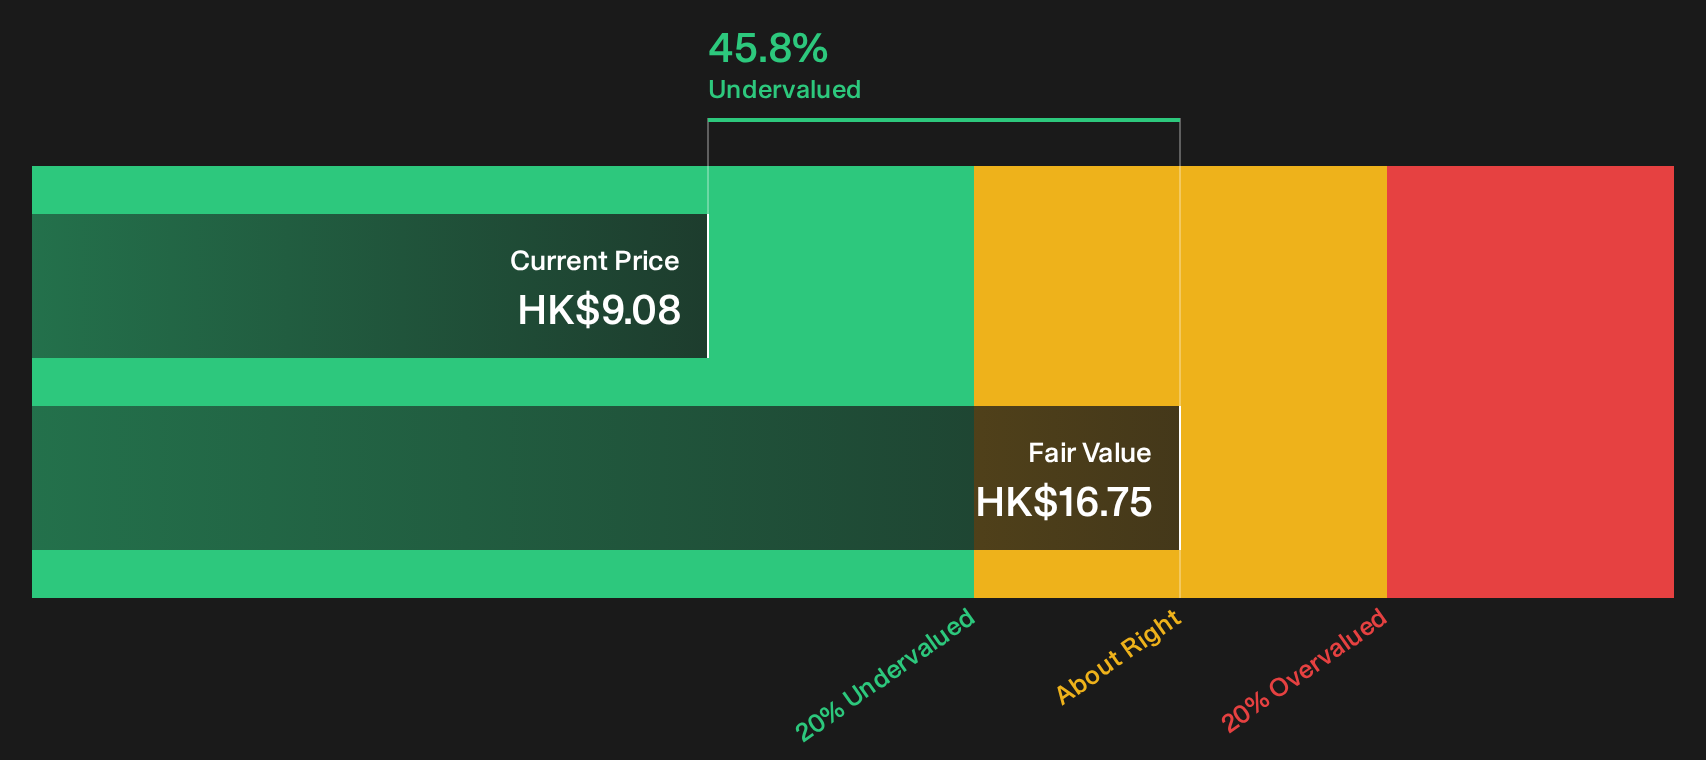
China Tower (SEHK:788)
Overview: China Tower runs shared telecom towers and related digital infrastructure across China, renting space and power services to mobile operators and other clients.
Operations: The business generates about CN¥98.1b from telecommunications tower infrastructure services and related activities, all earned within mainland China.
Market Cap: HK$158.6b
China Tower matters for this cash flow focused screen because its rental style tower network underpins a long-lived revenue base that the analyst consensus Narrative on Simply Wall St believes the market is currently undervaluing.
"The ongoing rollout and densification of 5G infrastructure in China, now reflected in China Tower adding 364,000 new 5G base stations in 2025 and 187,000 in the first half of 2026 with over 95% delivered through co-location, continues to support leasing demand that can help sustain tower and DAS revenue and support earnings."
The outcome for China Tower's valuation depends on how one less visible pressure reshapes the balance between expanding services and future cash conversion.
That pressure point is exactly where expectations and reality can decouple, and the full narrative for China Tower breaks down how China Tower’s cash generation, capital needs and risks all tie together.
Crocs (CROX)
Overview: Crocs designs and sells casual footwear and accessories under the Crocs and HEYDUDE brands. It converts global shoe demand into cash flows that are central to this undervalued cash flow theme.
Operations: Crocs generates about US$3.4b in revenue from its Crocs brand and roughly US$692 million from HEYDUDE, with meaningful international exposure.
Market Cap: US$6.9b
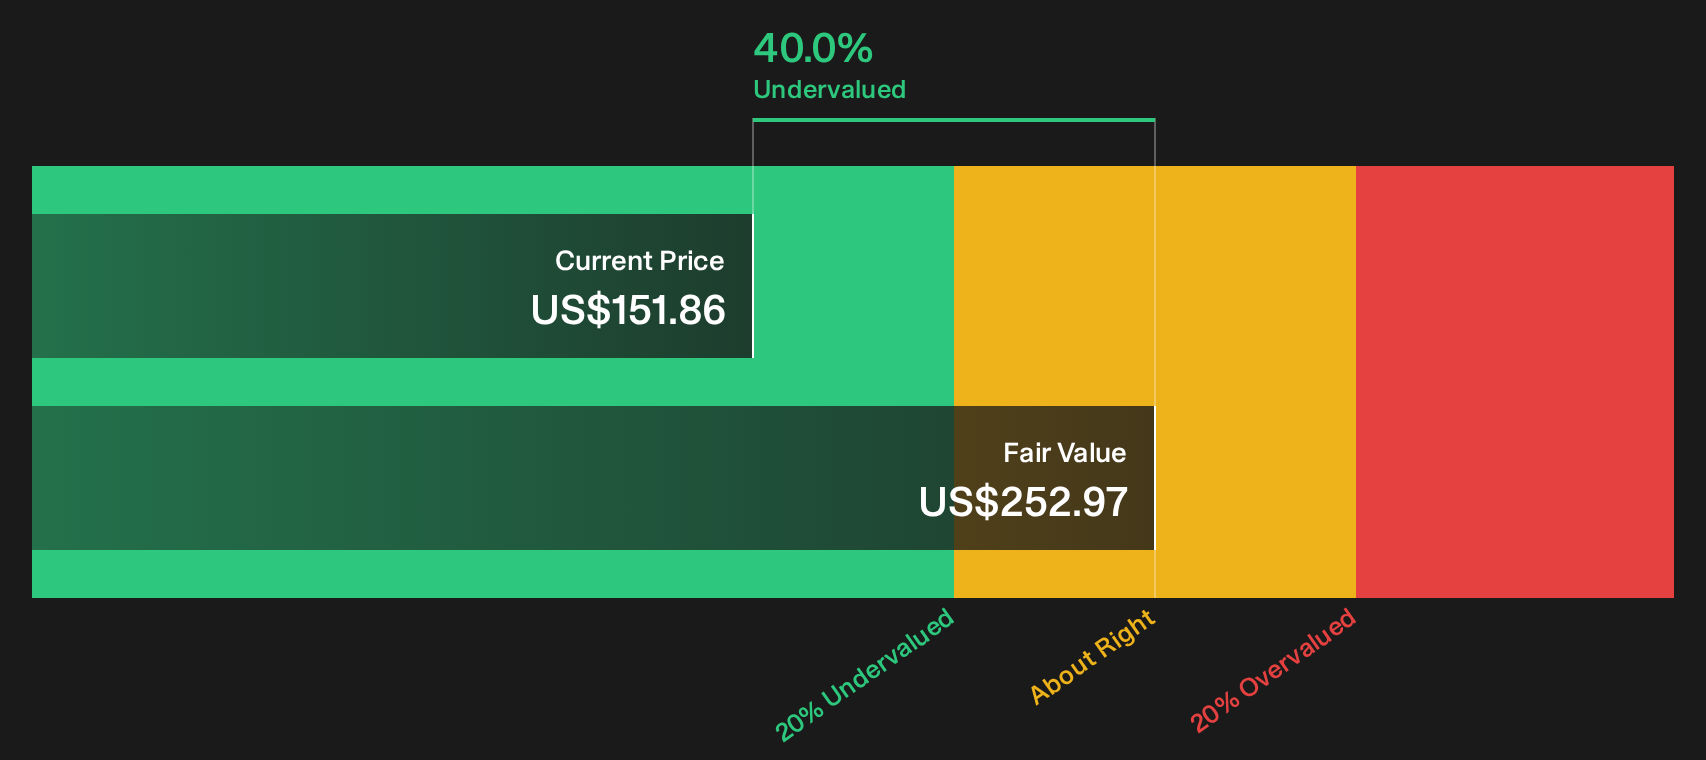
For this cash flow focused list, Crocs matters because its footwear cash engine runs through highly visible retail, wholesale and online channels. The analyst consensus Narrative on Simply Wall St argues that investors are not fully pricing in what those cash streams could be worth.
"Expansion of Crocs beyond the Classic Clog into sandals approaching $0.5b in expected 2026 revenue, new lifestyle franchises such as Ballet Flat and Mellow, and HEYDUDE extensions in sandals, work and boots points to a broader portfolio that can support a wider customer base and more stable revenue."
The real swing factor is how one cost and pricing pressure shapes the balance between that broader portfolio and future cash returns.
That pressure point is already shifting how investors frame risk and opportunity, and the full narrative for Crocs unpacks where Crocs’ cash engine could accelerate or stall next.
Amazon.com (AMZN)
Overview: Amazon.com runs a global e-commerce platform, subscription services, advertising network and AWS cloud division that collectively generate substantial cash flows.
Operations: Amazon.com earns about US$460.3b from North America, US$175.8b from International, and US$161.4b from AWS cloud services.
Market Cap: US$2.8t
Amazon.com matters for this cash flow focused screen because AWS converts cloud demand into high margin, recurring cash that anchors the wider group’s valuation, and MarketMuse, a Simply Wall St Community investor who wrote the Narrative, argues that this cash engine is still being misread by many investors.
"AWS reaccelerated through 2025 with roughly 20% year-over-year growth, exiting the year with an annualized revenue base exceeding $130 billion."
What investors really need to watch is how one big capital spending cycle ultimately reshapes future margins and the timing of free cash flow.
That capital cycle is exactly where expectations can misprice what comes next, and the full narrative for Amazon.com shows how those spending plans, cash flows and risks are really stacked.

Seeking Fresh Alternatives Before Others Do
Some of the most interesting ideas often move from quiet to breakout before most investors react. Scan fresh lists that could be flying under the radar for now and explore them early.
- Spot cash rich businesses quietly gaining momentum by running your filters through the list of solid balance sheet and fundamentals (193 results) while the data still gives you a head start.
- Target income opportunities that might hold up when sentiment swings by zeroing in on the 228 dividend fortresses before yields change.
- Track early movers in critical metals and companies tied to them through the curated 33 best rare earth metal stocks while these opportunities are still thinly covered.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com