


EN
Raised Sales Guidance Could Be A Big Test For Incyte Stock (INCY)
- Incyte reported third quarter 2026 revenue of US$1,557.2 million and a net loss of US$784.8 million, while raising full year 2026 total net sales guidance to a range of US$5,210 million to US$5,300 million.
- Fresh Phase 1 oncology data from ESMO 2026, including high objective response rates for INCB161734 combinations in metastatic pancreatic and colorectal cancer, highlights how Incyte’s pipeline progress sits alongside heavier development spending and a much lower year to date net income base.
- We will now assess how Incyte’s raised 2026 net sales guidance shapes the broader investment narrative around its emerging franchises.
Scan how Incyte’s oncology-heavy story compares with other high-potential biopharma plays by reviewing our hand-picked 35 healthcare AI stocks that could be building the next wave of treatment breakthroughs.
Incyte Investment Narrative Recap
To own Incyte, you need to be comfortable with a story that trades near term earnings pressure for potential longer term breadth across oncology, dermatology and hematology. The third quarter showed revenue of US$1,557.2 million but a net loss of US$784.8 million, and for the first nine months net income fell sharply to US$104.13 million, which keeps margin compression squarely in focus.
The analyst consensus Narrative on Simply Wall St already flagged higher R&D and SG&A as a key risk, and the latest figures reinforce that point. Raised 2026 net sales guidance to US$5,210 million to US$5,300 million matters operationally, yet the biggest short term catalyst still looks like clean execution on upcoming launches and label expansions, while the main risk is that heavy spending does not translate into a broader non Jakafi revenue base.
The most relevant update here is Incyte’s raised 2026 total net sales guidance. Management now sees US$5,210 million to US$5,300 million of net sales, slightly above the prior range. That sits alongside nine month revenue of US$4,503.92 million and a sharp drop in net income to US$104.13 million, which shows how growth investments and one off items are weighing on reported profitability.
For you as a shareholder, this combination means the headline loss in the third quarter and thinner margins are not being ignored, but they are being paired with a higher top line outlook. The guidance tweak interacts with the GI oncology and dermatology catalysts by effectively raising the bar on execution, while the risk case remains that ongoing R&D intensity, including large transaction costs, keeps pressuring earnings if key Phase 3 programs and launches underperform expectations.
Incyte's current analyst narrative points to 2029 revenue of US$5.4b and earnings of US$775.4 million, based on an assumed yearly revenue decline of 3.3% and a move from earnings today of US$403.4 million to that US$775.4 million level by 2029. This implies earnings would need to rise by about 1.9x from the current base.
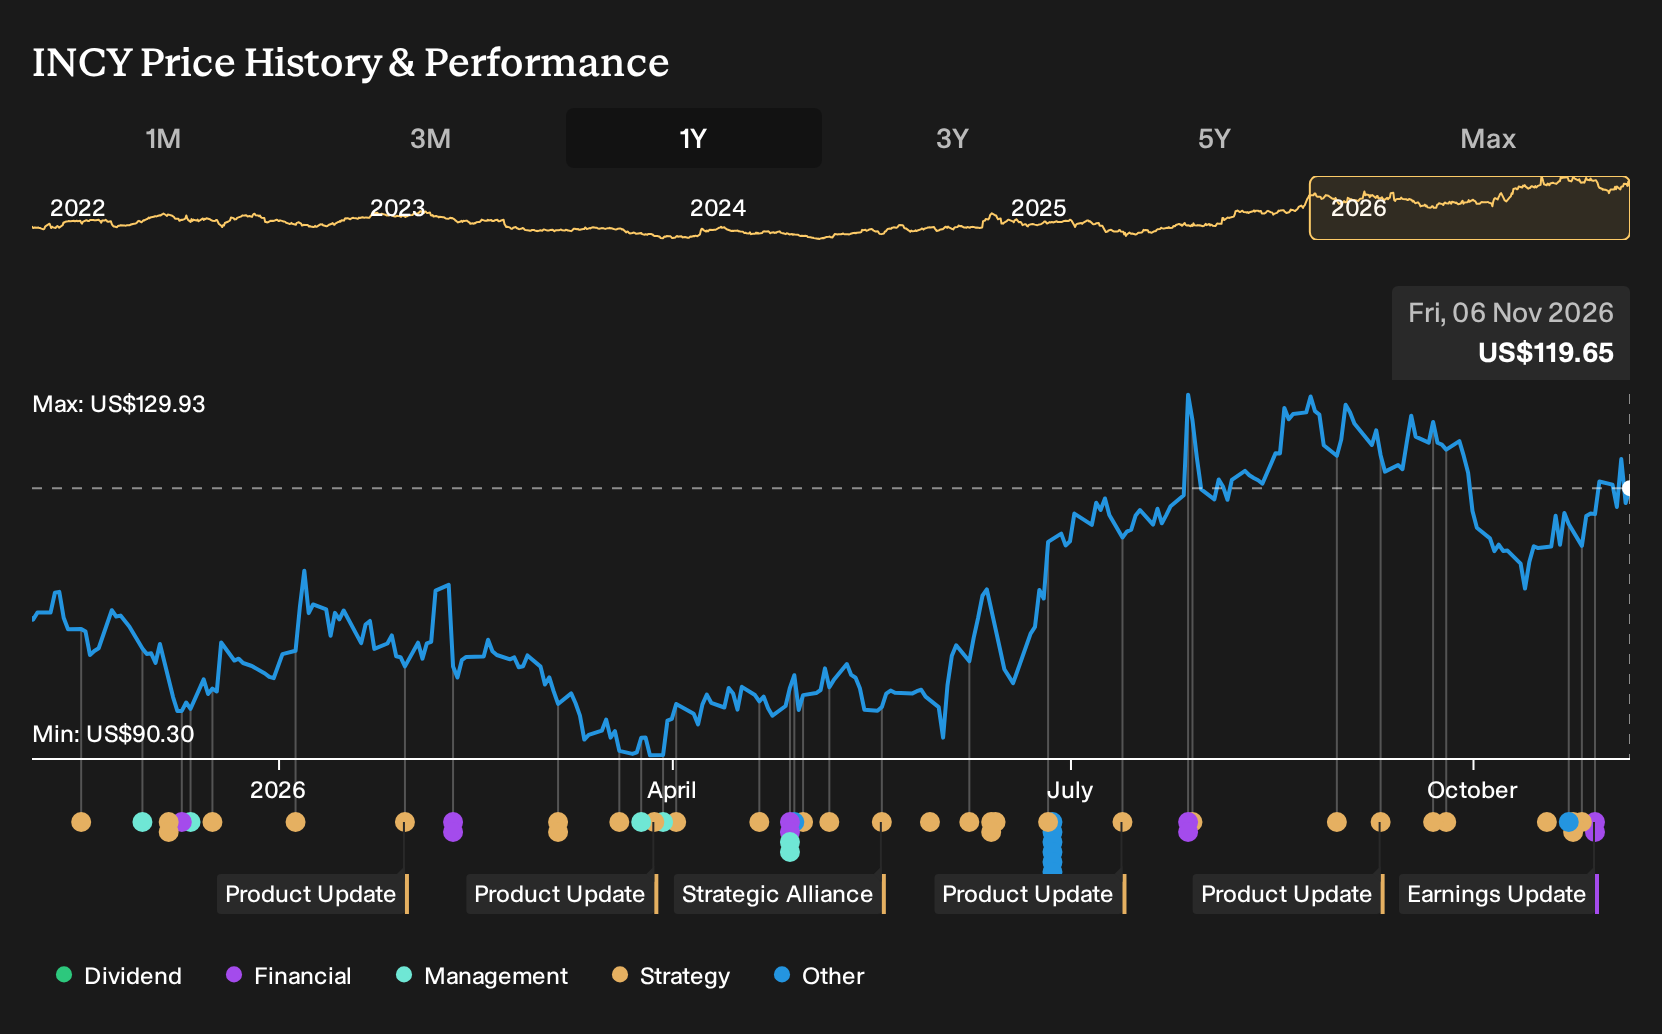
Uncover why Incyte's fair value indicates a 10% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view leans hard into the oncology catalyst. The most optimistic analysts were penciling in revenue of about US$7.6b and earnings of US$2.2b by 2029 before this Incyte update. You can treat the raised 2026 sales guidance and fresh GI oncology data as a real time test of that far more bullish script.
Explore 4 other Incyte fair value estimates, including one that suggests there could be as much as 40% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Incyte research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Incyte. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Incyte's overall financial health at a glance.
Looking For More Investment Ideas Beyond Incyte?
If the Incyte story has sharpened your sense of what you want in a healthcare or biotech holding, the next step is to widen the lens and compare it with other opportunities using the Simply Wall St Screener.
- If you care about quality at a sensible entry point, scan a curated 40 high quality undervalued stocks that combine solid fundamentals with prices that may not fully reflect them yet.
- If capital preservation and smoother rides appeal more than big swings, focus on a 31 resilient stocks with low risk scores that score well on balance sheet strength and business stability.
- If you want to get in early on lesser-known stories, search through a 19 high quality undiscovered gems that pair robust financials with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com