


EN
Kestra Medical Technologies (KMTS) Nears Analyst Targets, Does It Look Fully Valued?
Kestra Medical Technologies (KMTS) drew fresh attention after recent trading left the share price at $28.80, with returns mixed over the past week, month, and past 3 months for this US-based medical device player.
Recent trading paints a picture of cooling momentum for Kestra Medical Technologies, with a 1 day share price return of 0.95% and a 7 day share price return that declined 3.39%, alongside a year to date share price return of 18.08% and a 1 year total shareholder return of 9.01%.
Scan how Kestra Medical Technologies compares with other healthcare players showing resilient momentum and fundamentals by reviewing the hand picked list of solid balance sheet and fundamentals (25 results).
Kestra Medical Technologies shows double digit revenue growth alongside a sizeable loss and a share price edging near analyst targets. Do those figures back the optimists or strengthen the cautious view as valuation comes into focus next?
Most Popular Narrative: 4% Undervalued
Kestra Medical Technologies is trading at $28.80 compared with a narrative fair value of $30.00, which the analyst consensus Narrative on Simply Wall St derives from its combined revenue and earnings forecasts along with a 7.52% discount rate.
This narrative expects Kestra Medical Technologies to widen its share of an underused U.S. wearable cardioverter defibrillator market and to translate more prescriptions into higher revenue per fit. The expectation is that improved payer coverage, a larger sales footprint and platform upgrades help the company work toward better gross margins and narrower losses.
See why 1 investors see Kestra Medical Technologies as 4% undervalued.
Result: Fair Value of $30 (UNDERVALUED)
Still, the Kestra Medical Technologies story could face pressure if losses remain sizeable relative to its US$106.7 million in revenue, or if execution around payer coverage and prescription conversion falls short of expectations.
Find out about the key risks to this Kestra Medical Technologies narrative.
Another View: Kestra Medical Technologies Looks Expensive On Sales
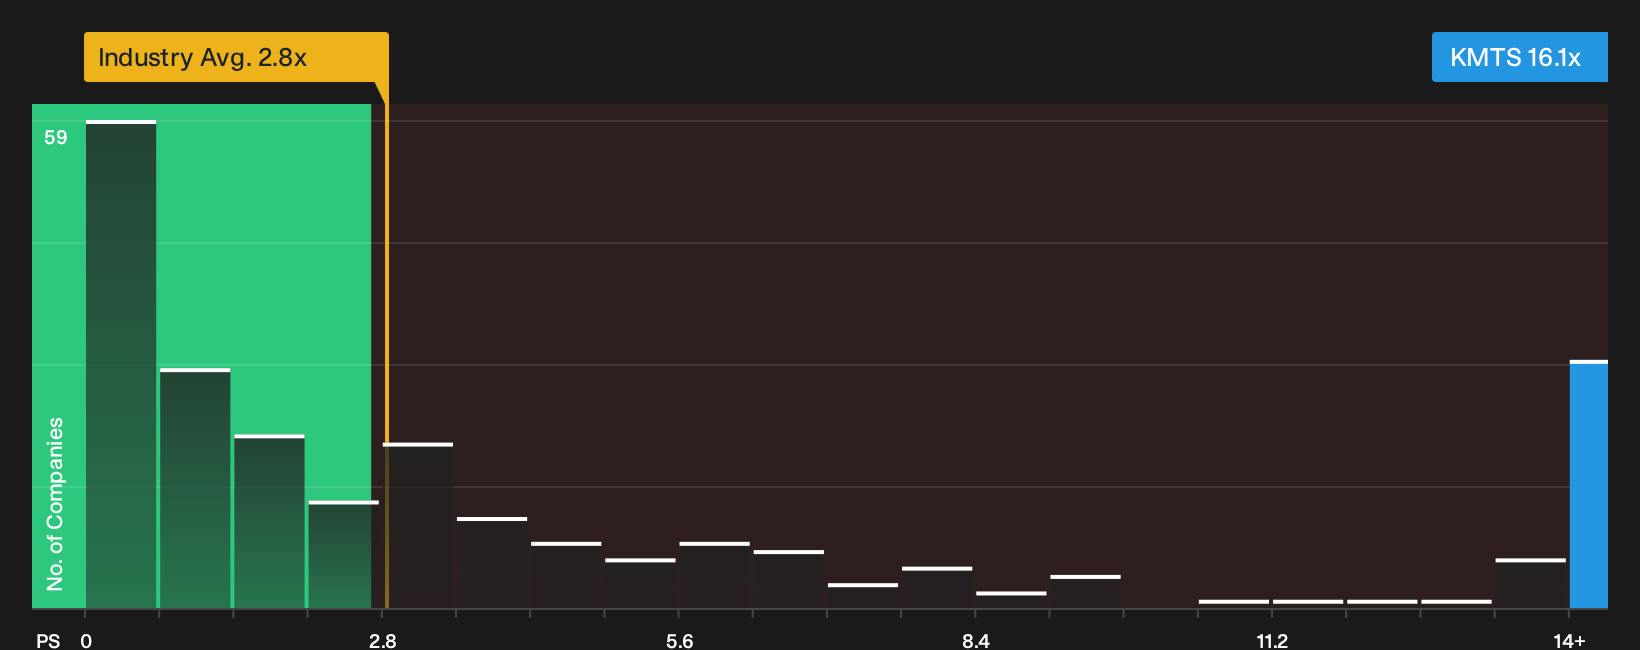
While the narrative fair value of $30 suggests Kestra Medical Technologies is modestly undervalued, the P/S picture tells a different story. The stock trades on a P/S of 16.1x, compared with a 4.1x fair ratio, 2.8x for the wider US Medical Equipment group and 4.5x for peers. That gap points to meaningful valuation risk if sentiment cools or execution stumbles.
Investors weighing this richer P/S starting point against the 4% narrative discount may want to stress test their own assumptions around growth, margins and future market enthusiasm for Kestra Medical Technologies before leaning too hard on either signal. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Reading this mix of optimism and concern around Kestra Medical Technologies, it makes sense to move quickly and check the details that matter most to you. To balance both sides of the story, review the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Kestra Medical Technologies?
Do not stop with Kestra Medical Technologies. Use this momentum to compare other opportunities and pressure test your portfolio against fresh, data driven ideas.
- Spot potential bargain opportunities early and review the 19 high quality undiscovered gems that combine strong fundamentals with lower market attention.
- Prioritise resilience and check the 31 resilient stocks with low risk scores to see companies that pair lower risk scores with sturdier financial profiles.
- Target quality at a reasonable price and scan the 40 high quality undervalued stocks that blend strong cash flows with balance sheets that can handle shocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com