


EN
Jack Henry & Associates (JKHY) Could Be 1% Overvalued As Earnings And 2027 Guidance Lift Confidence
Jack Henry & Associates earnings jolt investor focus
Jack Henry & Associates (JKHY) just posted first quarter results with sales of US$701.55 million and net income of US$160.41 million, alongside fresh fiscal 2027 revenue and EPS guidance.
At a share price of US$173.23, Jack Henry & Associates has logged a 30-day share price return of 16.02% and a 90-day share price return of 11.70%. The 1-year total shareholder return of 9.37%, alongside fresh earnings, fiscal 2027 guidance, and recent client wins, suggests momentum has recently picked up after a softer year-to-date share price return of 2.87%.
Capitalize on the renewed interest in Jack Henry & Associates by scanning a curated set of financial technology peers with strong balance sheets and steady fundamentals using our list of solid balance sheet and fundamentals (25 results).Bulls point to Jack Henry & Associates’ recent earnings, guidance, and client wins as proof the rerating is justified. Bears see a stretched move. Which side does the current valuation actually support?
Most Popular Narrative: 1% Overvalued
Jack Henry & Associates closed at $173.23 against a narrative fair value of $170.89, a slight premium that has sharpened the debate on whether the recent rally has already priced in the current earnings and contract wins. According to LunaRodas, a Simply Wall St Community investor who wrote the narrative, the real story sits in how management’s promises on sales momentum, margins, and platform strategy compare to what is now showing up in the transcripts.
The August call's dominant narrative posture was confidence compounding on confidence. Adelson opened with three "records": financial performance, sales wins, and trifecta attach, and structured the rest of the prepared remarks as evidence for a fourth record: the platform's upmarket credibility. The Woodforest name, withheld in May for contractual reasons, served double duty in August: it proved the almost-$10-billion figure mentioned in May and anchored a broader argument that the company can now demonstrate its technology rather than describe it.
See why 3 investors see Jack Henry & Associates as 1% overvalued.
Result: Fair Value of $170.89 (ABOUT RIGHT)
Still, the Jack Henry & Associates story could be knocked off course if management’s margin caution persists despite stronger quarters, or if Banno’s outside-core push continues to fade from the script.
Find out about the key risks to this Jack Henry & Associates narrative.
Another View on Jack Henry & Associates' Valuation
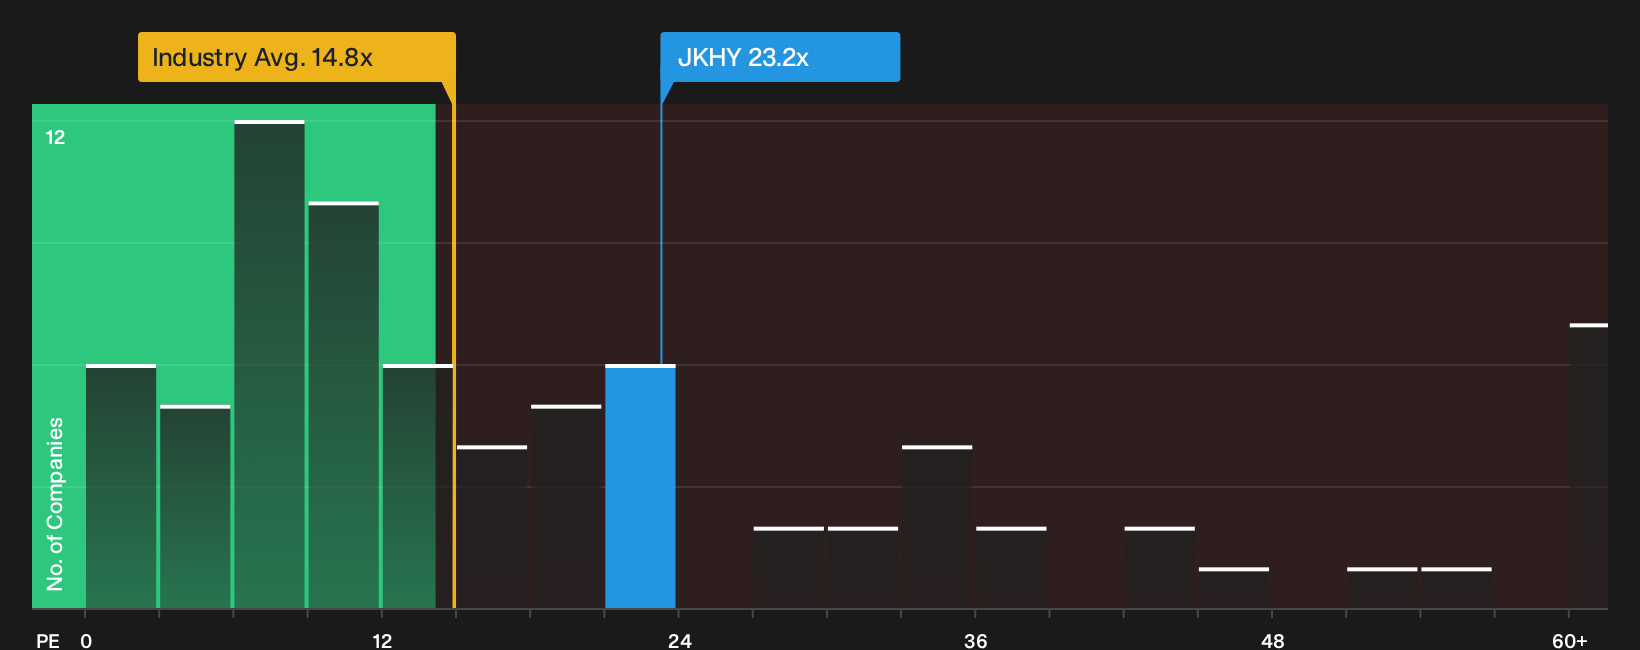
Jack Henry & Associates may look close to fair value against the community narrative, yet the P/E picture tells a different story. The shares trade on a 23.2x multiple versus 14.8x for the US Diversified Financial industry and a fair ratio of 13.2x, which suggests investors are paying a hefty premium that could compress if sentiment cools.
That gap between today’s pricing and the fair ratio leaves an open question for you as a shareholder: whether this premium reflects durable quality or simply optimistic expectations that have crept too far ahead.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of investors see reasons for optimism in Jack Henry & Associates, yet any premium only matters if it matches your own conviction. Act while the details are fresh and weigh the upside yourself by checking the 4 key rewards
Looking for more investment ideas beyond Jack Henry & Associates?
If Jack Henry & Associates has sharpened your focus on quality, keep that momentum going by lining up your next candidates with a few focused screeners.
- Zero in on potential mispricings by reviewing a curated set of quality companies that still trade below intrinsic value through the 40 high quality undervalued stocks.
- Strengthen your income plan by filtering for reliable payers with higher yields using the targeted 7 dividend fortresses.
- Dial up resilience in your watchlist by scanning for businesses with healthier finances through the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com