


EN
Loews (L) Could Be 4% Below Fair Value After Profitability Pressured Earnings
Profitability pressure behind Loews earnings reaction
Loews (L) just posted third quarter results that showed higher revenue alongside lower net income, a mix that put profitability in focus and helped trigger the latest move in the stock.
The insurer and conglomerate reported third quarter revenue of US$4.76b, compared with US$4.67b a year earlier, while net income declined to US$306m from US$504m.
Basic and diluted earnings per share from continuing operations for the quarter were US$1.50, down from US$2.43 in the prior year period, highlighting pressure on per share profitability despite the larger top line.
Over the first nine months of 2026, Loews recorded revenue of US$14.05b against US$13.72b a year before, with net income at US$1.09b compared with US$1.27b for the same stretch in 2025.
Nine month basic and diluted EPS from continuing operations came in at US$5.29, lower than US$6.03 a year earlier. This leaves investors weighing the trade off between revenue scale and earnings power as of early November 2026.
The latest earnings update appears to have checked near term enthusiasm, with the share price slipping 1.3% on the day and 3.0% over the past three months. This comes even as Loews still shows a positive year to date share price return of 4.8% and a much stronger five year total shareholder return of 98.4%.
Scan beyond Loews and see how other insurers and diversified financials are handling the same profitability squeeze with our curated list of 31 resilient stocks with low risk scores.
Loews looks like a solid, diversified business on paper, yet the recent earnings dip and share pullback raise a sharper question: Are you paying a fair price for that quality today or stretching for it?
Preferred P/E of 14.9x: Is it justified?
Valuation on Loews today hinges on a fairly simple question. You are paying a P/E of 14.9x for earnings that have slowed relative to both the firm’s own history and the wider insurance group.
The P/E multiple compares the current share price of $109.71 with the most recent annual earnings per share. For a diversified insurer and conglomerate like Loews, it is a shorthand for how much investors are willing to pay for each dollar of profit from its insurance, pipelines, hotels, and manufacturing operations.
Here the numbers start to bite. Recent earnings growth of 2.5% over the past year trails the 5.3% per year rate seen over the past five years, and it also lags the 16.2% earnings expansion reported for the broader Insurance industry. That slower pace of profit growth sits next to high quality earnings and an 8.2% return on equity that is described as low, which suggests the current earnings stream is solid but not especially high returning.
The market is charging a richer P/E than both the peer group and the industry as a whole, with Loews at 14.9x versus a peer average of 13.5x and a US Insurance industry average of 11.4x. That is a clear valuation premium, and given the stock has underperformed both the Insurance sector and the broader US market over the past year, it implies investors are already paying up for a collection of assets that is not currently matching industry level profit growth.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 14.9x (OVERVALUED).
Still, the Loews story could be knocked off course if profitability pressure deepens or if key units like CNA or Boardwalk Pipelines encounter operational roadblocks.
Find out about the key risks to this Loews narrative.
Another view on Loews valuation
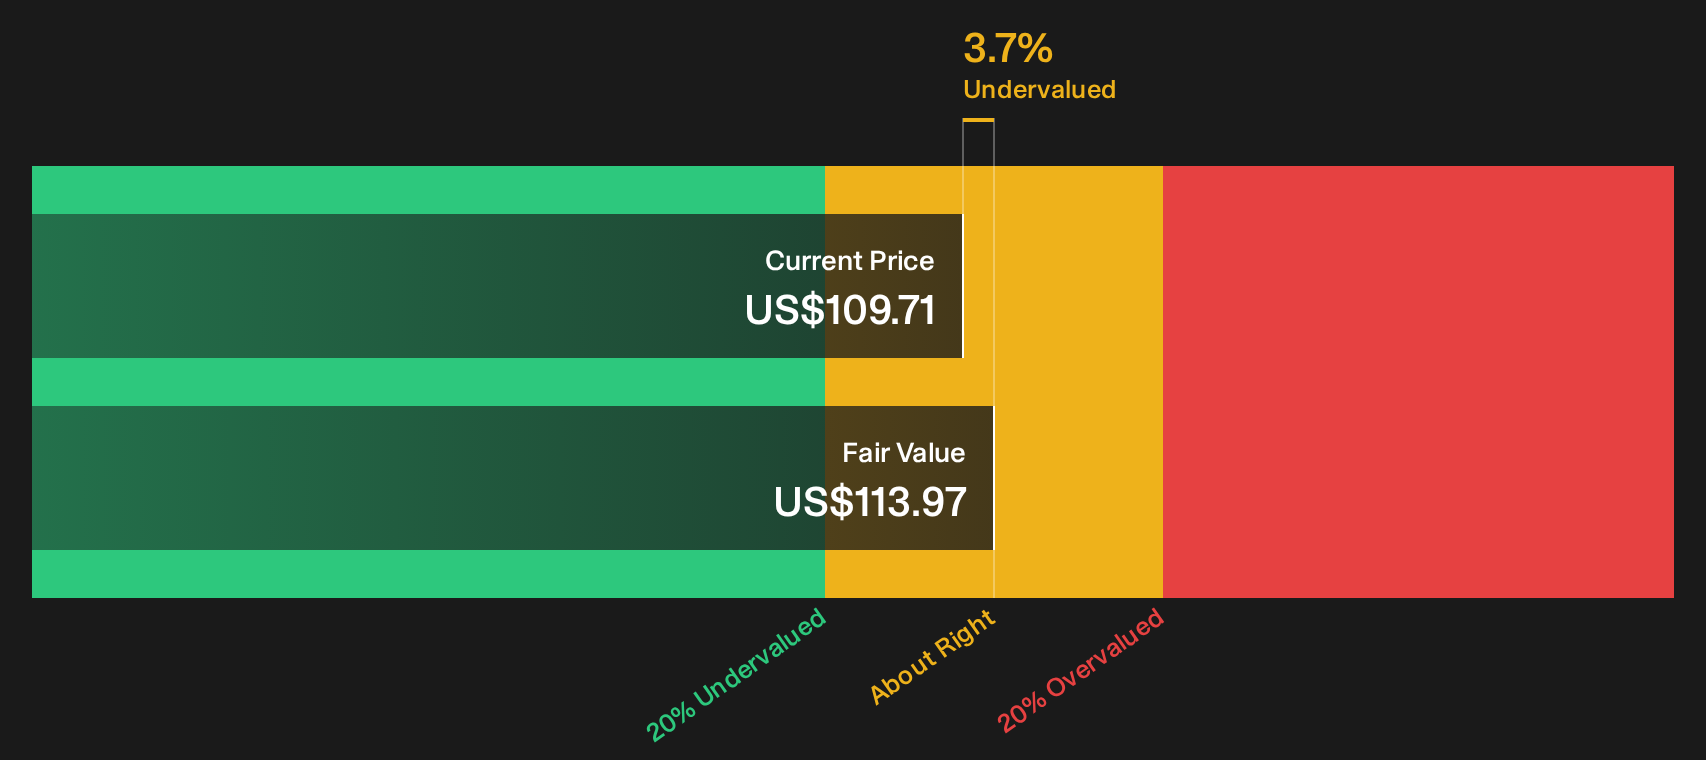
The earnings based P/E story makes Loews look expensive, yet the SWS DCF model points in a different direction. On that view, the shares at $109.71 sit about 3.7% below an estimated future cash flow value of $113.97, which frames the question very differently. Is this a quality on sale, or just a small discount for slowing profit growth?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Loews for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 40 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the tone so far feels cautious, that is intentional; it is exactly why you should pressure test the numbers yourself and move quickly while sentiment is still resetting around Loews. To see what investors currently view as the upside case, take a closer look at 2 key rewards.
Looking for more investment ideas beyond Loews?
Loews gives a useful reference point, but your portfolio benefits when you line it up against other clear, rule based ideas sourced from consistent screening.
- Target resilience first and see which businesses clear our quality filters through the list of solid balance sheet and fundamentals (25 results).
- Hunt for value by focusing on companies where price lags fundamentals with the 40 high quality undervalued stocks.
- Build a foundation of stability and income potential by reviewing the 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com