


EN
Manchester United (MANU) Faces A Fresh Valuation Test Following Relegation Warning
Event driven focus on Manchester United stock
Manager Erik ten Hag’s recent warning that relegation risk cannot be ruled out puts Manchester United (NYSE:MANU) in sharp focus for investors assessing how on pitch uncertainty interacts with a rich share price.
Recent trading indicates that momentum has been building. The share price return over the past month is 10.24%, and the year-to-date share price return of 43.28% contrasts with a 42.11% total shareholder return over one year, as speculation around relegation risk, potential squad turnover and new sponsorship deals keeps Manchester United in sharp focus for investors weighing rich pricing against rising volatility in perceived future cash flows.
Compare Manchester United’s recent surge with other clubs-linked and media-related plays by scanning a curated group of 19 high quality undiscovered gems that the market may not be fully pricing yet.
Manchester United offers a powerful global brand and diverse media income, yet the recent share price surge puts a sharper spotlight on whether that strength is already embedded in today’s valuation.
Most Popular Narrative: 4.4% Undervalued
Against a last close of $22.61, the analyst consensus Narrative on Simply Wall St points to a fair value of $23.65 for Manchester United, which frames the current debate around whether recent on pitch uncertainty is fully reflected in the price.
The current valuation implies that the market is not fully pricing in the narrative that Manchester United is undervalued, and that successful execution of the rebuild and player trading approach could be more favourable for the share price than current expectations suggest.
See why 5 investors see Manchester United as 4% undervalued.
Result: Fair Value of $23.65 (UNDERVALUED)
Still, high wage contracts and reliance on uneven transfer income leave Manchester United exposed if the rebuild stutters or key sales fail to materialise.
Find out about the key risks to this Manchester United narrative.
Another view on Manchester United valuation
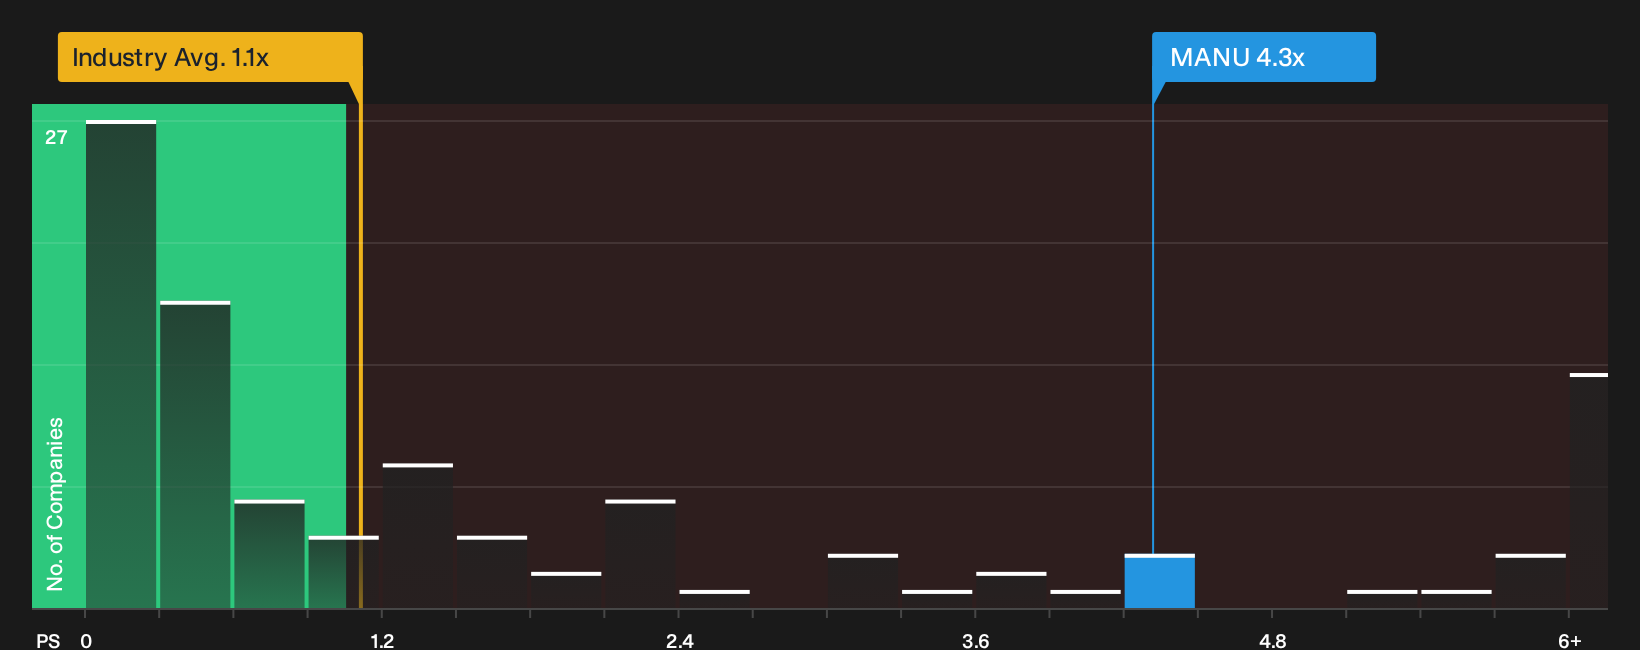
That analyst fair value of $23.65 suggests a modest 4.4% gap to the $22.61 share price. Manchester United trades on a P/S of 4.3x compared with 2.5x for peers and 1.1x for the wider US Entertainment group, while the fair ratio sits at 2x. Is the premium a cushion or a cliff edge?
To see how those sales multiples stack up against expected cash generation and sector norms, and what that could mean for future valuation risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Manchester United is clearly split, so this is the moment to move quickly, review the numbers and test your own thesis. To pressure test that view against flagged issues, take a closer look at the 1 important warning sign
Looking for more investment ideas beyond Manchester United?
Do not stop at Manchester United. Fresh ideas often come from scanning outside your comfort zone, and that is where structured screeners really help.
- Target resilience by focusing on companies with stronger finances than the crowd through a list of solid balance sheet and fundamentals (25 results).
- Hunt for potential mispricings by starting with a carefully filtered pool of 40 high quality undervalued stocks that already clear key quality checks.
- Dial down portfolio stress by concentrating on a curated universe of 31 resilient stocks with low risk scores that score well on stability and downside protection.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com