


EN
XPEL (XPEL) Could Be 38% Undervalued On Third Quarter 2026 Results
XPEL (XPEL) just posted third quarter and year to date 2026 results, giving investors fresh detail on revenue, earnings per share and overall profitability as the car protection specialist moves through the back half of the year.
Despite the stronger quarterly earnings picture, XPEL’s share price has been under pressure, with the stock down 4.17% on the day, a 7 day share price return of down 14.39%, and a year to date share price return of down 23.59%, while the 1 year total shareholder return is almost flat and the 5 year total shareholder return is down 47.80%, which points to fading momentum over a longer horizon as investors reassess the risk and growth profile after a strong run earlier in the decade.
Scan beyond XPEL and look for other car and mobility stocks that are under pressure yet still posting solid earnings progress with the hand picked 40 high quality undervalued stocks.
The share price reset has been sharp, while XPEL’s earnings and analyst price target sit higher than the current quote. Is the real upside still ahead, or has most of it already played out in the past cycle?
Most Popular Narrative: 37.7% Undervalued
On the analyst consensus Narrative on Simply Wall St, XPEL screens as undervalued, with a fair value of $61.67 versus the last close at $38.39, and that view leans heavily on how new manufacturing projects and higher margin services shape future earnings.
Increasing vertical integration through the planned US$110 million manufacturing and supply chain build out in San Antonio and China, supported by recent term debt and record operating cash flow, is expected to replace an asset light sourcing model with in house production. This could structurally lift gross margin and operating margin as facilities ramp.
See why 18 investors see XPEL as 38% undervalued.
Result: Fair Value of $61.67 (UNDERVALUED)
Still, the XPEL story could be knocked off course if the US$110 million manufacturing build out runs into delays or if lower cost Asian rivals pressure pricing and margins.
Find out about the key risks to this XPEL narrative.
Another Look At XPEL Using Market Ratios
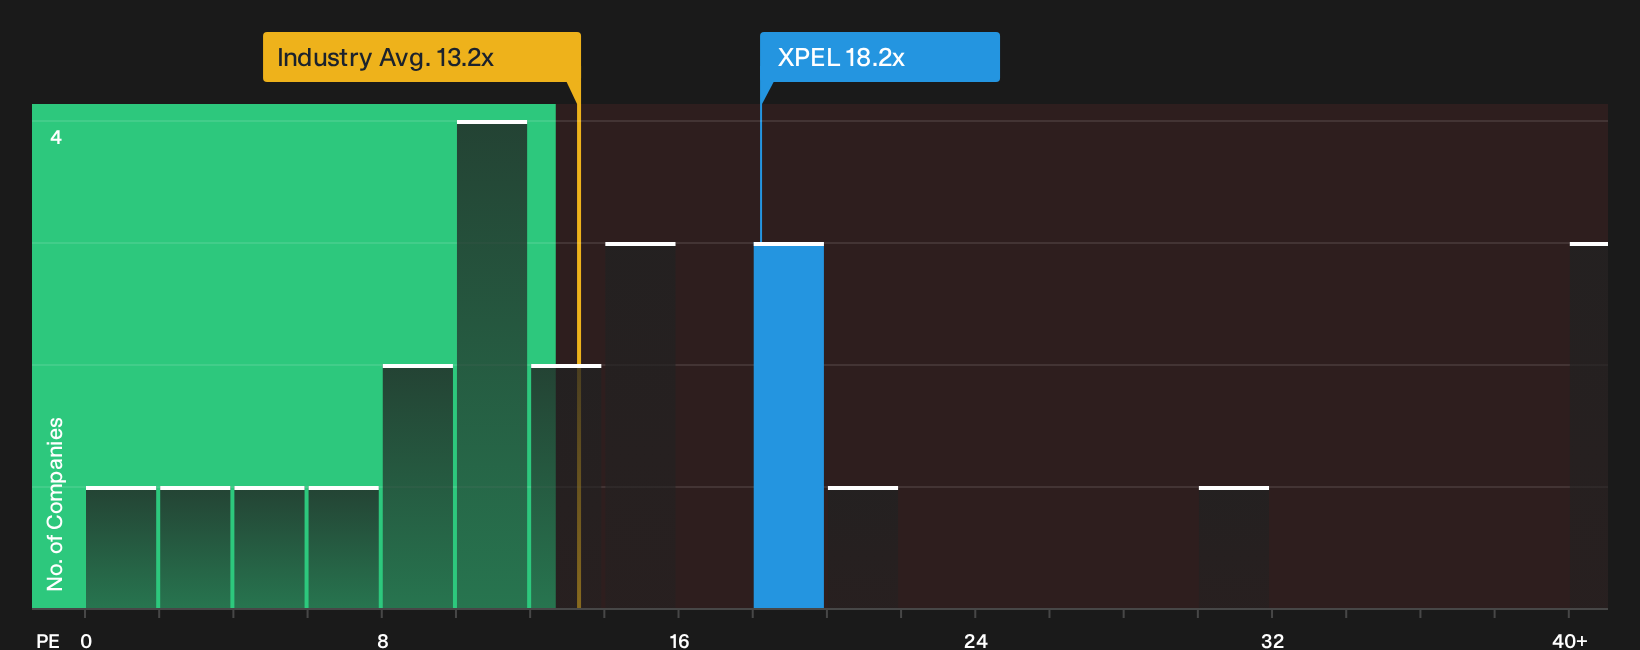
The SWS DCF model points to XPEL trading at a 47.3% discount to an estimated future cash flow value of $72.82, while the current P/E of 18.2x sits slightly above a fair ratio of 16.8x and above the US Auto Components average of 13.2x. Is the discount an opportunity or a signal that expectations need tempering?
For a closer look at how this earnings multiple compares, and where the fair ratio suggests the market could shift over time, see the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on XPEL is split, with risks and rewards pulling in opposite directions. Move quickly, review the numbers yourself, and weigh both sides through the 4 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond XPEL?
Do not stop at XPEL. Broaden your watchlist with fresh ideas that match different goals, risk comfort levels, and income needs using powerful stock screeners.
- Explore potential mispricing by focusing on quality companies that screens highlight as out of favor with the 40 high quality undervalued stocks.
- Reinforce your portfolio’s foundation by filtering for balance sheets and fundamentals that meet your criteria through the list of solid balance sheet and fundamentals (25 results).
- Scan for under followed opportunities that fit your strategy using the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com