


EN
ECB Rate Signals Put Eurozone Bank Shares Back In Focus
ECB officials are hinting at stronger support for sovereign bond markets and a gentler path on rate hikes. That combination is quietly rewiring the risk and reward trade off across Eurozone assets. Investors who wait for absolute clarity often find the best terms are already gone. This article unpacks how these policy signals could reshape pricing and reveals three Eurozone banks and financials from our screener that appear positively exposed to this shift.
The three stocks highlighted below are only a starting sample, and the full Eurozone banks and financials screen surfaced 14 more companies with equally grounded narratives that are not covered here. If you want to identify which of these larger Eurozone players best fits your own thesis, go straight to the Eurozone Banks and Financials screener to filter and analyze the full set of potential high conviction ideas.
Mediobanca Banca di Credito Finanziario (BIT:MB)
Overview: Mediobanca Banca di Credito Finanziario is an Italian diversified bank that blends wealth management, consumer lending, corporate and investment banking, insurance investing, and treasury services across Italy and other key global markets.
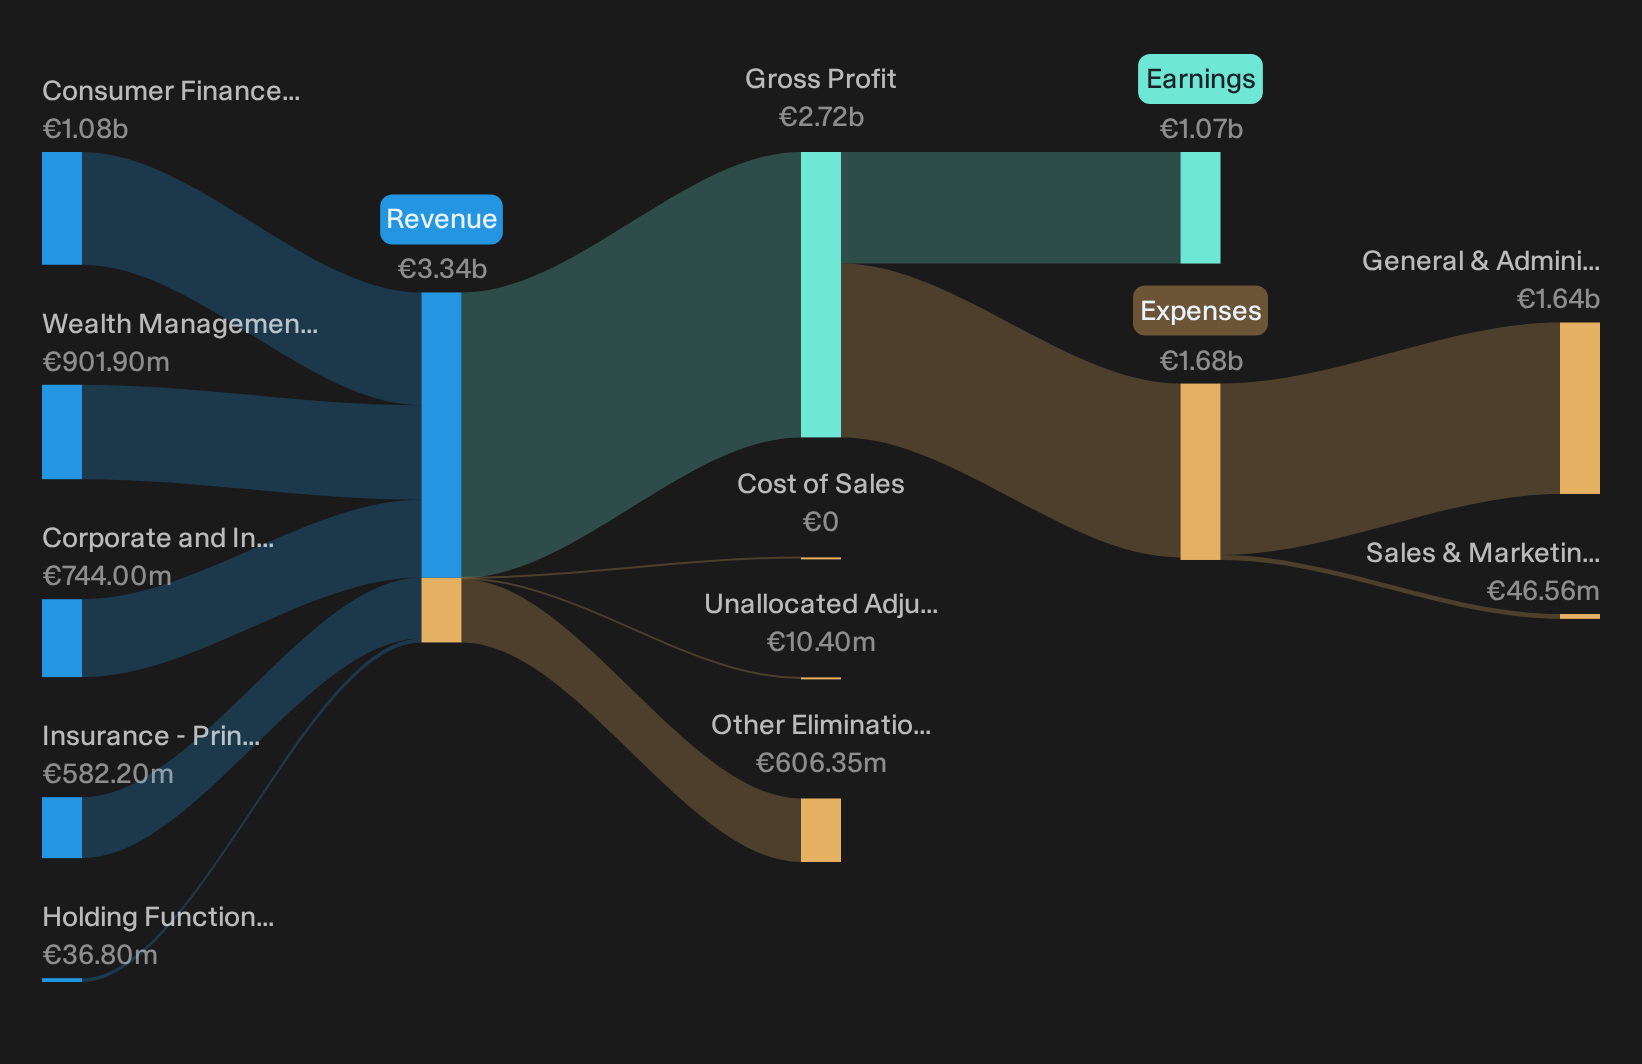
Operations: Mediobanca generates sizeable revenue from Consumer Finance (€1.1b), Wealth Management (€901.9 million), Corporate and Investment Banking (€744 million), and Insurance Principal Investing (€582.2 million), with Holding Functions making a smaller contribution.
Market Cap: €21.1b
Mediobanca Banca di Credito Finanziario sits within the Eurozone banks and financials theme, where earnings are closely linked to credit conditions and ECB decisions. The analyst consensus Narrative on Simply Wall St highlights how fee-driven activities can be important when bond markets and policy signals are in flux.
"The continued expansion of Wealth Management and Private Banking, supported by earlier net new money inflows and hiring in advisory roles, still points to additional fee income that can support Mediobanca Banca di Credito Finanziario revenue and smooth future earnings."
Investors may wish to consider whether a steadily building fee engine could be strong enough to help offset pressure from funding costs and credit quality.
Whether that fee engine proves enough, the full narrative for Mediobanca Banca di Credito Finanziario shows how Mediobanca Banca di Credito Finanziario's mix of lending, advisory and insurance could be quietly decoupling its risk profile.
Banca Monte dei Paschi di Siena (BIT:BMPS)
Overview: Banca Monte dei Paschi di Siena is a large Italian lender and wealth manager whose fortunes closely track Eurozone sovereign spreads and ECB policy.
Market Cap: €34.19b
Within the Eurozone Banks and Financials theme, Banca Monte dei Paschi di Siena is one of the clearest tests of how far ECB support for sovereign bonds can feed through into funding costs, capital plans and fee growth. This is exactly what the analyst consensus Narrative on Simply Wall St focuses on.
"Execution of the Mediobanca integration, with targeted annual synergies of €700 million by 2028 and early progress already reported, is set to affect Banca Monte dei Paschi di Siena’s cost base and support net margin resilience."
What happens if a single pressure point in that wider merger and consolidation plan shifts could matter a lot for how those margins settle.
If that pressure point matters to you, the full narrative for Banca Monte dei Paschi di Siena explains how the merger plan, capital decisions and fee engines could be accelerating or quietly stalling.
Piraeus Bank (ATSE:TPEIR)
Overview: Piraeus Bank is a Greek Eurozone lender that provides retail, business, markets and digital banking services closely tied to regional sovereign conditions.
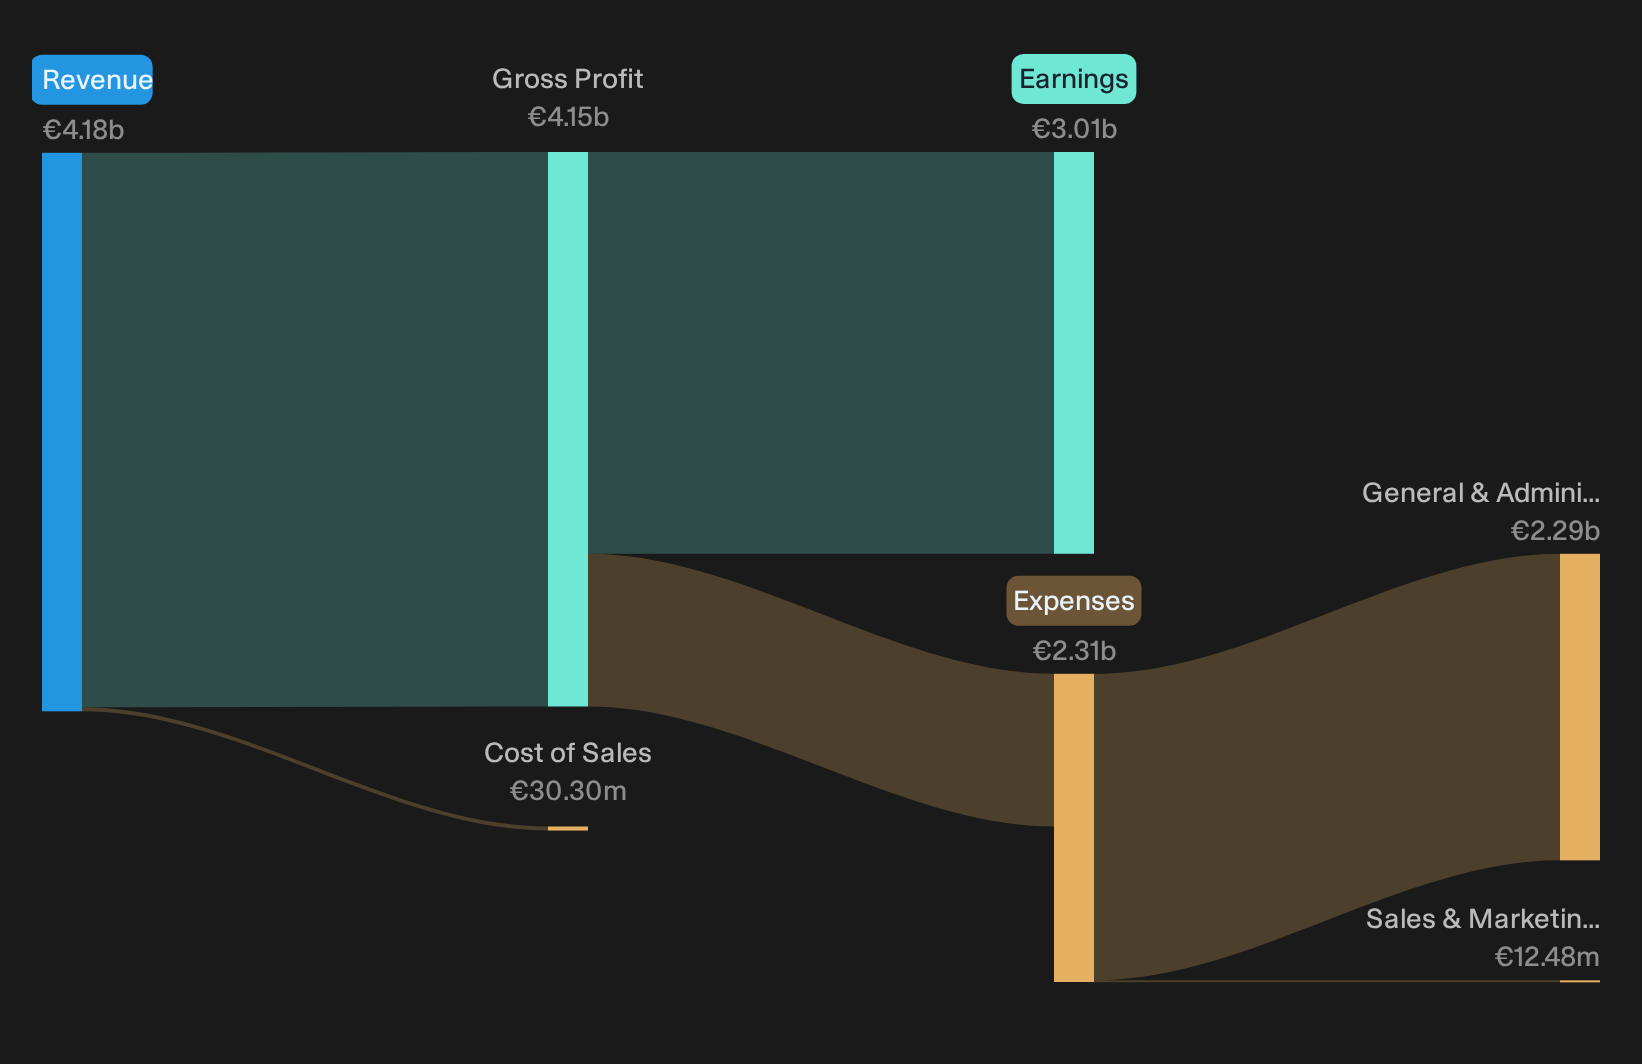
Operations: Piraeus Bank generates most of its income from Core Retail Banking (€1.4b), Core Corporate Banking (€831 million) and Core Piraeus Financial Markets (€467 million).
Market Cap: €11.87b
Piraeus Bank matters for this Eurozone Banks and Financials theme because its lending book and bond portfolio are tightly linked to Greek government spreads. The analyst consensus Narrative on Simply Wall St frames that sensitivity through the lens of digital efficiency, capital returns and fee growth as ECB support signals evolve.
"The rapid digitalization of banking services in Greece and across Europe, combined with Piraeus Bank's newer platforms like Odyssey, robo-advisors and the AI hub with Accenture, is building on earlier progress with Snappi and low cost-to-income levels. This is helping to further reduce unit servicing costs and support net margin resilience as more activity shifts to digital channels."
What happens if one pressure point in that wider balance between rising digital fee income and lingering credit risk shifts will matter for future profitability.
That balance can shift quickly, so read the full narrative for Piraeus Bank to see how Piraeus Bank’s digital push and credit risks could be quietly resetting its earnings profile.

Seeking Alternatives Before Momentum Flies
Fresh opportunities rarely stay under the radar for long. Once momentum builds, ideal entry points can change quickly. Review these curated ideas early and consider where they might fit in your own research process.
- Spot reliable income ideas and pressure test your current holdings against a curated list of 227 dividend fortresses before yields adjust.
- Track early movers in automation and position around operational momentum by scanning a focused basket of 91 robotics and automation stocks while they remain less widely followed.
- Target resilient balance sheets and stress test your portfolio against a hand-picked list of solid balance sheet and fundamentals (193 results) before the highest quality names become more broadly recognized.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com