


EN
What Alfa Laval Holders Bought Into
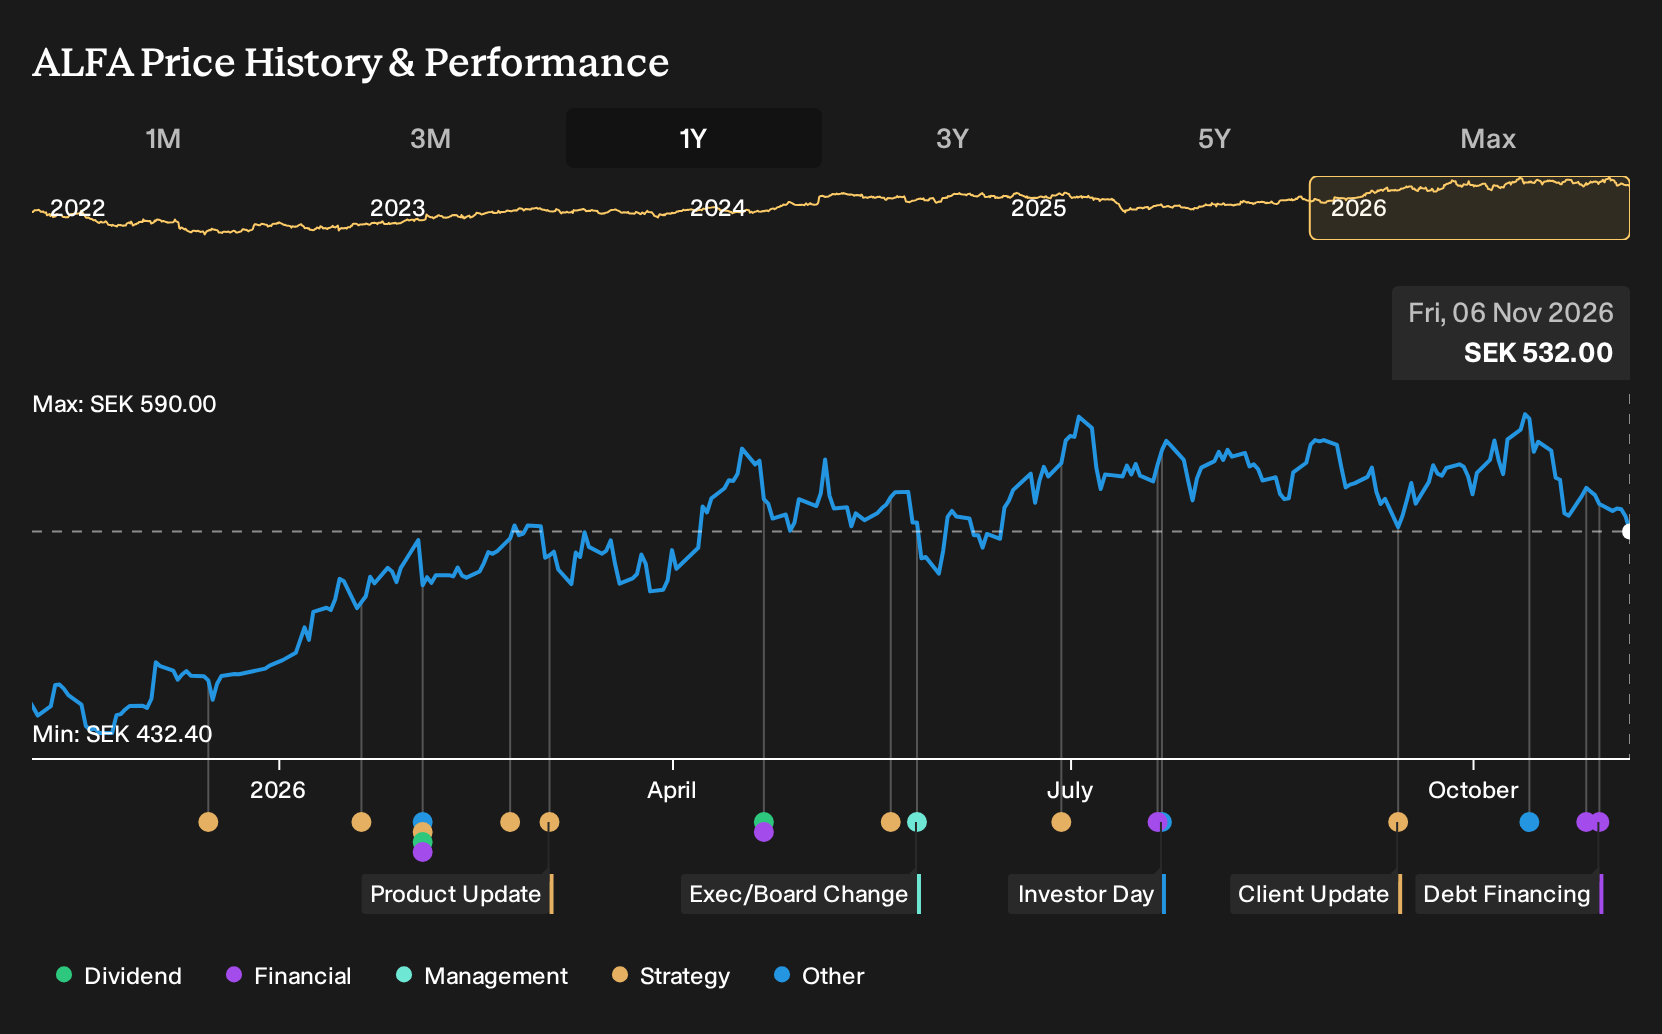
If you were skimming Alfa Laval headlines recently, the $700 million move to buy maritime software group NAVTOR probably caught your eye. Investors who held Alfa Laval over the past year are up 21.4%, including dividends. That outcome landed alongside news of higher Q3 2026 revenue but a weaker net margin. If you were deciding back in November 2025, what had to look credible about digital shipping, decarbonization and services to make that bet feel worth it?
Alfa Laval is not the only name tied to this theme. Zero in on 41 power grid technology and infrastructure stocks and compare how each one is priced.
The Two Stories Investors Had To Choose Between On Alfa Laval
The shares cost SEK445 at the start of the period, so anyone looking at Alfa Laval had to decide which story about decarbonization, services and regulation felt more realistic.
The bullish narrative pointed to a Fair Value of SEK530, a price level that reflected belief in LNG and hydrogen exposure plus growing digital services. That view leaned on assumptions of 8.1% annual revenue growth and profit margins rising from 11.8% to 12.5% by 2028.
The cautious camp anchored on a Fair Value of SEK345, based on concerns that faster decarbonization could weaken legacy fossil fuel equipment. Those expectations used 1.9% annual revenue growth, a margin shift from 11.8% to 11.9%, and a future P/E of 20.2x as key inputs.
What The Evidence Around Alfa Laval Actually Tested
The stand out data point was Alfa Laval’s Q3 2026 update. Revenue moved from SEK17,244m in Q3 2025 to SEK18,596m, which supported the bullish argument about demand, while net income slipped from SEK2,288m to SEK2,233m and net margin eased from 13.3% to 12.0%, which challenged the cleaner profitability story. Overall, the evidence cut both ways.
The key lesson for readers is simple. When a thesis leans on margin expansion, check whether reported net margin actually moves up alongside higher sales before trusting the growth story.
What Alfa Laval’s Recent Run Already Prices In
Today Alfa Laval trades at SEK532 after a 21.4% gain over the past year. The bearish analyst Narrative on Simply Wall St places its Fair Value below that level, framing the current quote as already reflecting strong belief in record orders, big projects and heavy investment paying off.
A buyer today effectively banks on data centers, biofuels, carbon capture and Marine service all scaling smoothly into resilient earnings. This raises the question of how the Narrative’s concerns on project timing, sanctions and service mix might challenge that assumption.
"The current valuation for Alfa Laval implies that record orders, a large order book and long dated growth projects are already priced in, which leaves limited room for disappointment if growth, margins or capital allocation fall short of expectations."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Before The Next Story Makes Headlines
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 39% below our estimate - expands power and refrigeration capacity while investing in technicians and additional facilities.
- Company 2 - 20% below our estimate - anchors advanced chip production as customers rely on leading process technology.
- Company 3 - 40% below our estimate - refocuses content and merchandise on core Asian fans while delaying English expansion.
Those are three of them. See the full list of 227 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com