


EN
Higher Grade Mining Could Reshape The Americas Gold And Silver Stock Story
- Americas Gold and Silver is shifting production toward higher grade silver copper ore at its EC120 Cosalá mine, targeting commercial output by late 2025 and pairing this strategy with operational upgrades at the Galena Complex.
- The company is testing antimony recovery as a potential new product stream, which could diversify revenue given rising US demand for this critical mineral.
- This article examines how Americas Gold and Silver's investment narrative is shaped by the EC120 higher grade silver copper production transition.
Americas Gold and Silver Investment Narrative Recap
To own Americas Gold and Silver, you need to be on board with a simple idea. The business is trying to turn a high cost, debt heavy mining portfolio into a leaner, more silver weighted operation built around EC120 and a more efficient Galena Complex. The recent update on higher grade EC120 material keeps that thesis alive but does not remove execution risk.
The near term swing factor is whether EC120 reaches commercial production around late 2025 while all in sustaining costs keep trending lower. The biggest current risk sits on the financial side. A $100m senior secured facility and continued losses, including $15m in Q2 2025, leave little room for prolonged delays or operational setbacks.
The analyst consensus narrative on Simply Wall St highlights the EC120 transition as a key driver for future revenue and cash generation. That same shift toward silver and copper has already coincided with revenue of $27m in Q2 2025 compared with $33m a year earlier, so the business needs the higher grade ore to translate into more efficient output rather than just a different mix.
EC120 also interacts directly with other moving pieces at Americas Gold and Silver. Concentration in Galena and Cosalá raises the impact of any disruption, and the all in sustaining cost level of $32.89 per ounce in Q2 2025 keeps the focus squarely on execution. For readers, the EC120 ramp is not just another project update. It is the operational lever that could either ease balance sheet pressure or make further dilution and tighter financing conditions more likely.
Americas Gold and Silver's current analyst narrative points to revenue of $557.4 million and earnings of $205.5 million by 2029, based on an assumed 45.3% yearly revenue growth rate and a move from a loss of $47.7 million today to that 2029 consensus profit. This implies an earnings swing of about $253 million over the period.
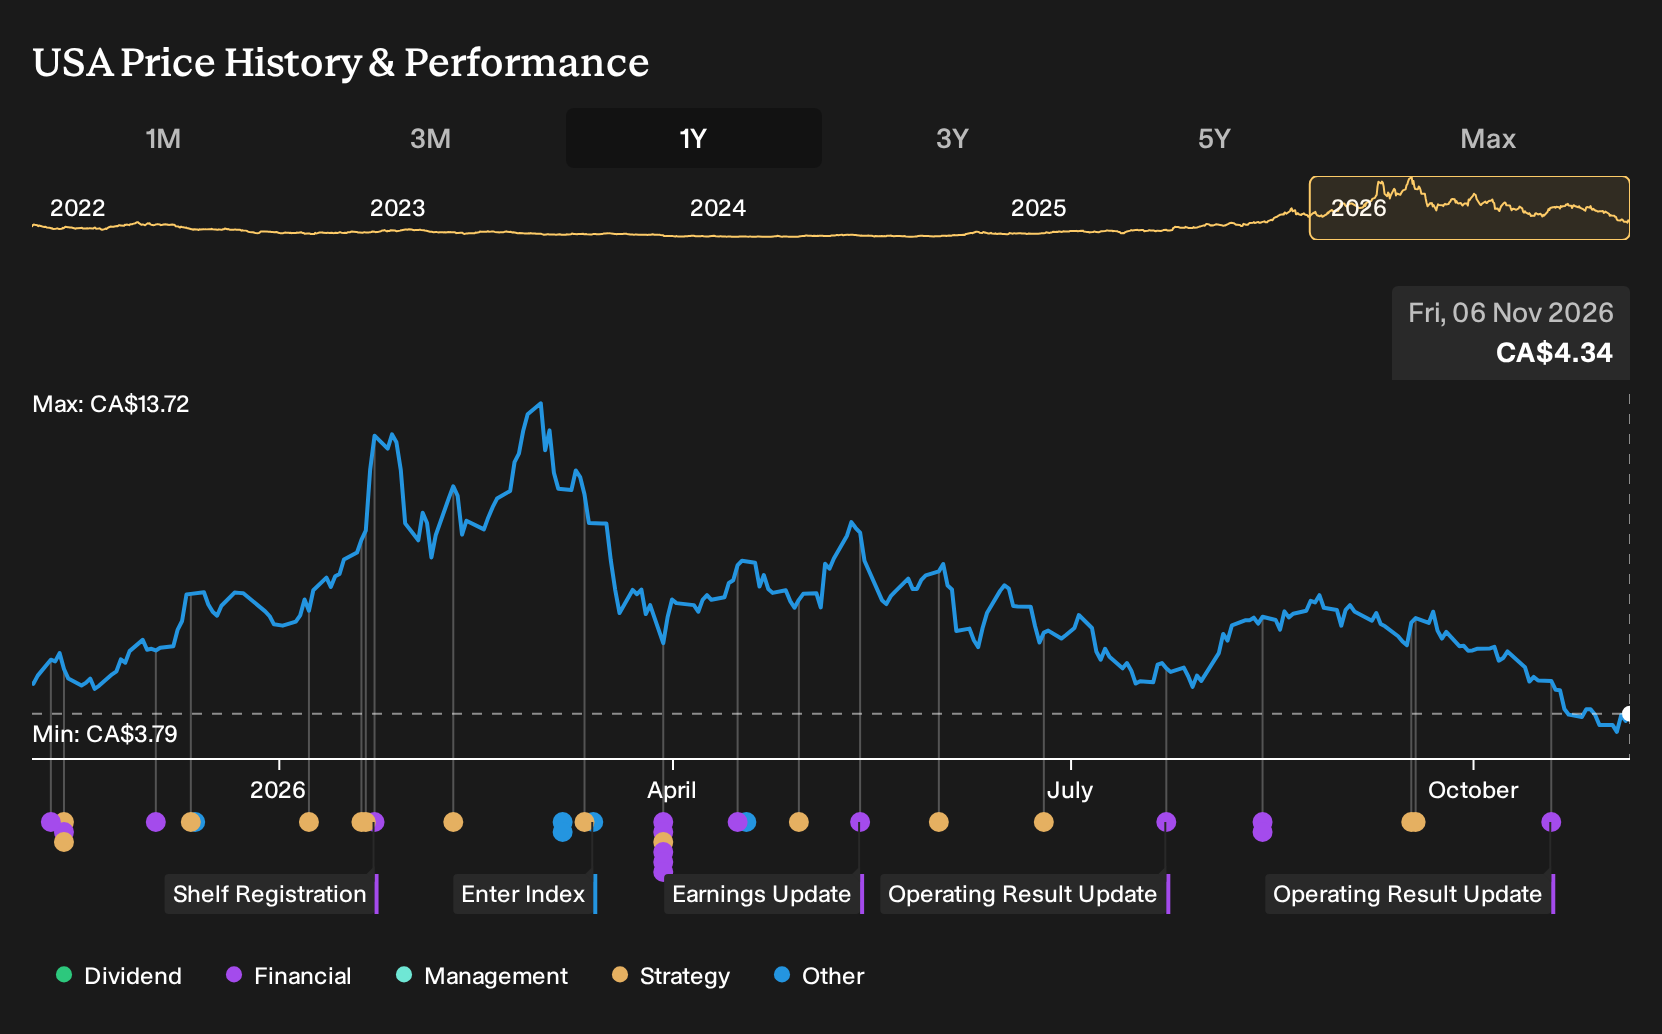
Uncover why Americas Gold and Silver's fair value signals a 191% potential upside to its current price, which could narrow quickly as sentiment catches up.
Exploring Other Perspectives
One alternate view focuses on the antimony plan at Americas Gold and Silver. The most optimistic analysts treat a future antimony business as the key upside swing, with prior forecasts running to about $674.9 million of revenue and $274.4 million of earnings by 2029. Your own view may change as EC120 and antimony test results evolve, so compare several narratives before deciding what feels realistic.
Explore 3 other Americas Gold and Silver fair value estimates, including one that suggests the potential for as much as 265% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Americas Gold and Silver research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Americas Gold and Silver. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Americas Gold and Silver's overall financial health at a glance.
Looking For More Ideas Beyond Americas Gold and Silver?
If you want to cross check the Americas Gold and Silver story against other potential opportunities, a quick pass through a few targeted stock lists can help you spot patterns in quality, balance sheets, and income resilience.
- For investors who care most about balance sheet strength and fundamental resilience, start with this curated list of solid balance sheet and fundamentals (5 results) and see which businesses combine financial stability with underlying quality.
- If dependable income is your priority, focus on potential high yield payers by scanning this hand picked group of 3 dividend fortresses that may suit a more income oriented approach.
- When you want to hunt for less crowded opportunities, review this carefully filtered set of 8 high quality undiscovered gems and compare their fundamentals with what you see at Americas Gold and Silver.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com