


EN
The Bet Kuehne + Nagel Holders Made
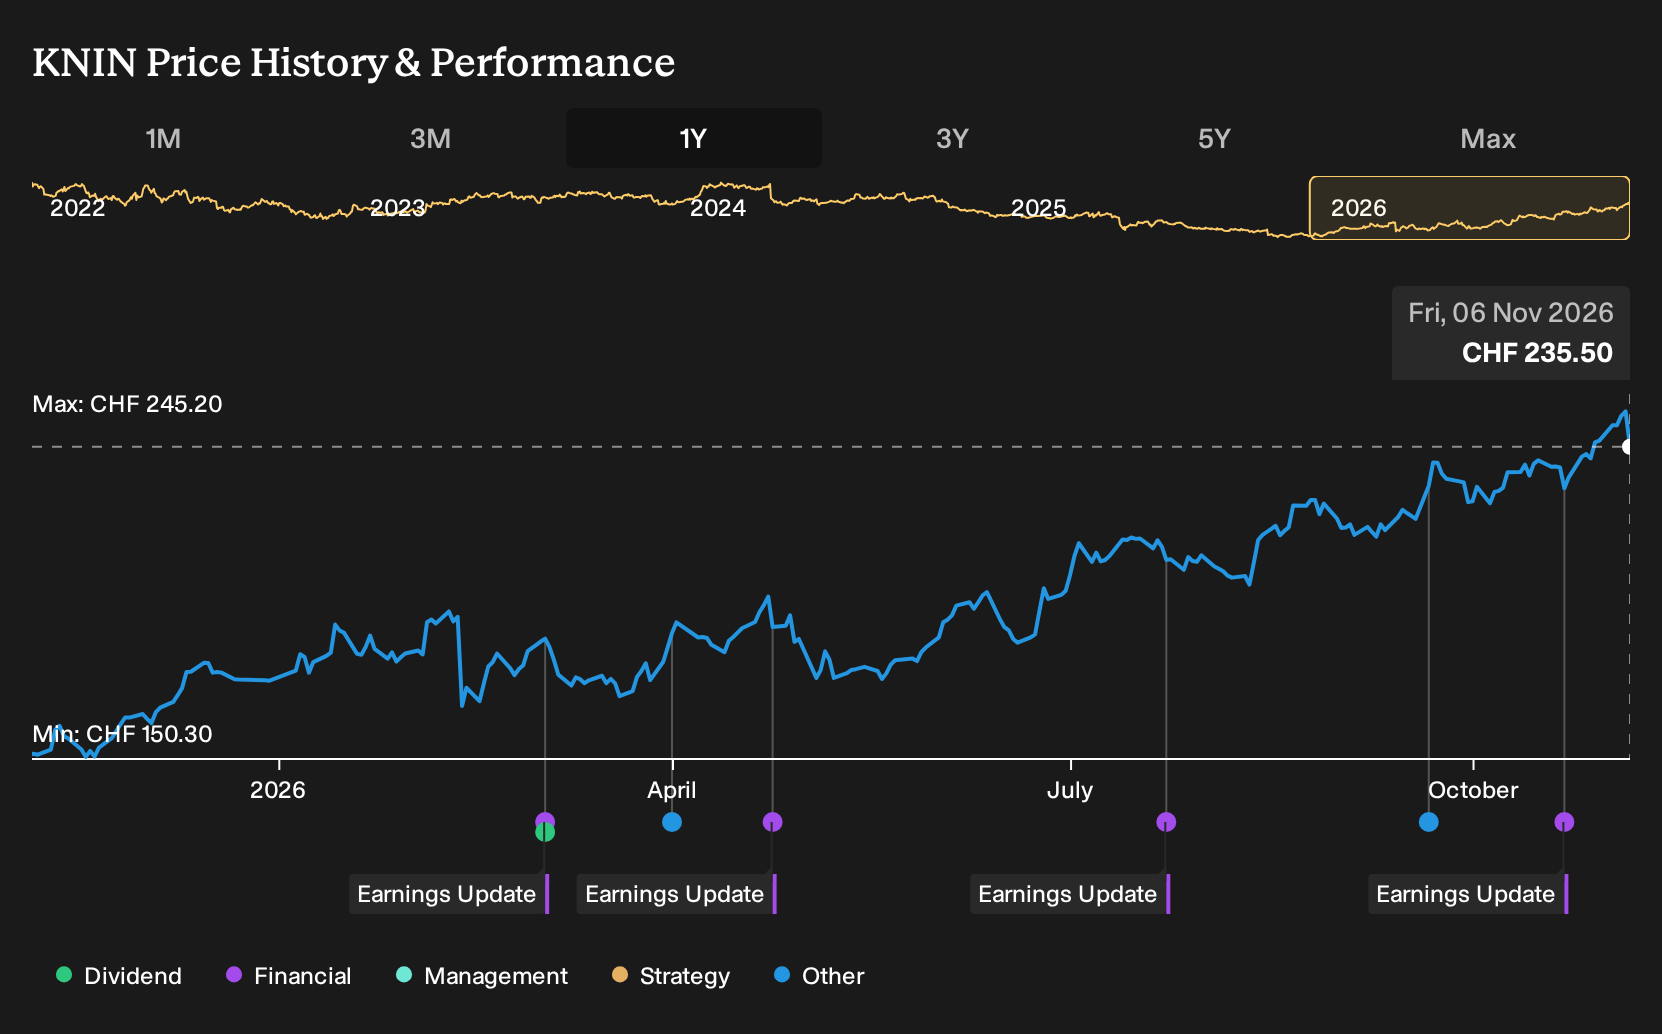
If you only glanced at Kuehne + Nagel International headlines, the eye catcher was the 2026 guidance bump that lifted recurring EBIT expectations into the CHF1,500m to CHF1,600m range. For Kuehne + Nagel International shareholders, the return over the past year was 60.1%, including dividends. If you were weighing a purchase back on 6 November 2025, what assumptions about future volumes, pricing and margins would have had to feel credible before that upgrade arrived?
The move put Kuehne + Nagel International in the middle of this trade. Scan 41 power grid technology and infrastructure stocks for other companies exposed to it.
The Two Futures Investors Saw For Kuehne + Nagel International
At the start of the period the shares cost CHF151, and anyone looking at Kuehne + Nagel International had to decide which story felt more realistic.
The bullish case, summarized in a November 2025 view with a Fair Value of CHF176 as an implied long term price anchor, leaned on revenue growth of 1.2% and a 4.7% profit margin assumption supported by expansion in e-commerce heavy sectors.
The bearish June 2025 narrative pointed to a Fair Value of CHF127 as its implied worth and focused on trade protectionism, digital disintermediation risk, and an assumed annual revenue decline of 5.4%.
What The Results Changed For Kuehne + Nagel International
The biggest development was Kuehne + Nagel International lifting its 2026 recurring EBIT guidance to CHF1,500m to CHF1,600m after Q3 2026 results, which backed the optimistic volume and margin story. Reported revenue moved from CHF6,043m in Q3 2025 to CHF7,386m in Q3 2026, while net income rose and net margin shifted from 3.2% to 4.2%. The evidence supported the optimistic case.
The episode turned on whether modest margin assumptions were realistic. When you look at another logistics stock, track whether later guidance and reported net margin land above or below the level investors pencilled in at the decision date.
What Kuehne + Nagel International's Price Now Assumes
Kuehne + Nagel International now trades at CHF236 after a 60.1% gain over the past year. The bearish analyst Narrative on Simply Wall St places its Fair Value below that level and frames freight tailwinds as fragile rather than permanent.
The Narrative asks what must keep going right. A buyer at CHF236 would need confidence that cost savings and AI driven productivity really offset any freight yield reset without hurting service quality.
"The main thing that has to go right is that AI driven productivity gains and the cost reduction program translate into the targeted CHF 200m plus of annualized savings and CHF 100 to 150m of additional EBIT by end 2027 without eroding service quality."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Looking One Step Beyond Kuehne + Nagel
Kuehne + Nagel shows how logistics software influences real world movements and costs.
Yet your decision rarely ends with one familiar transport specialist in focus.
Behind freight expectations sits a sharper question: who sets economics when algorithms match routes?
Another platform for rides, deliveries and freight already relies on data-driven marketplace matching.
The unresolved twist is autonomy. If software and fleet owners capture more value, how do marketplace operators defend their share?
One Narrative has already put a figure on it. → Uncover the company trading 41% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com