


EN
Profit Drop Could Be A Key Test For Ares Management Stock (ARES)
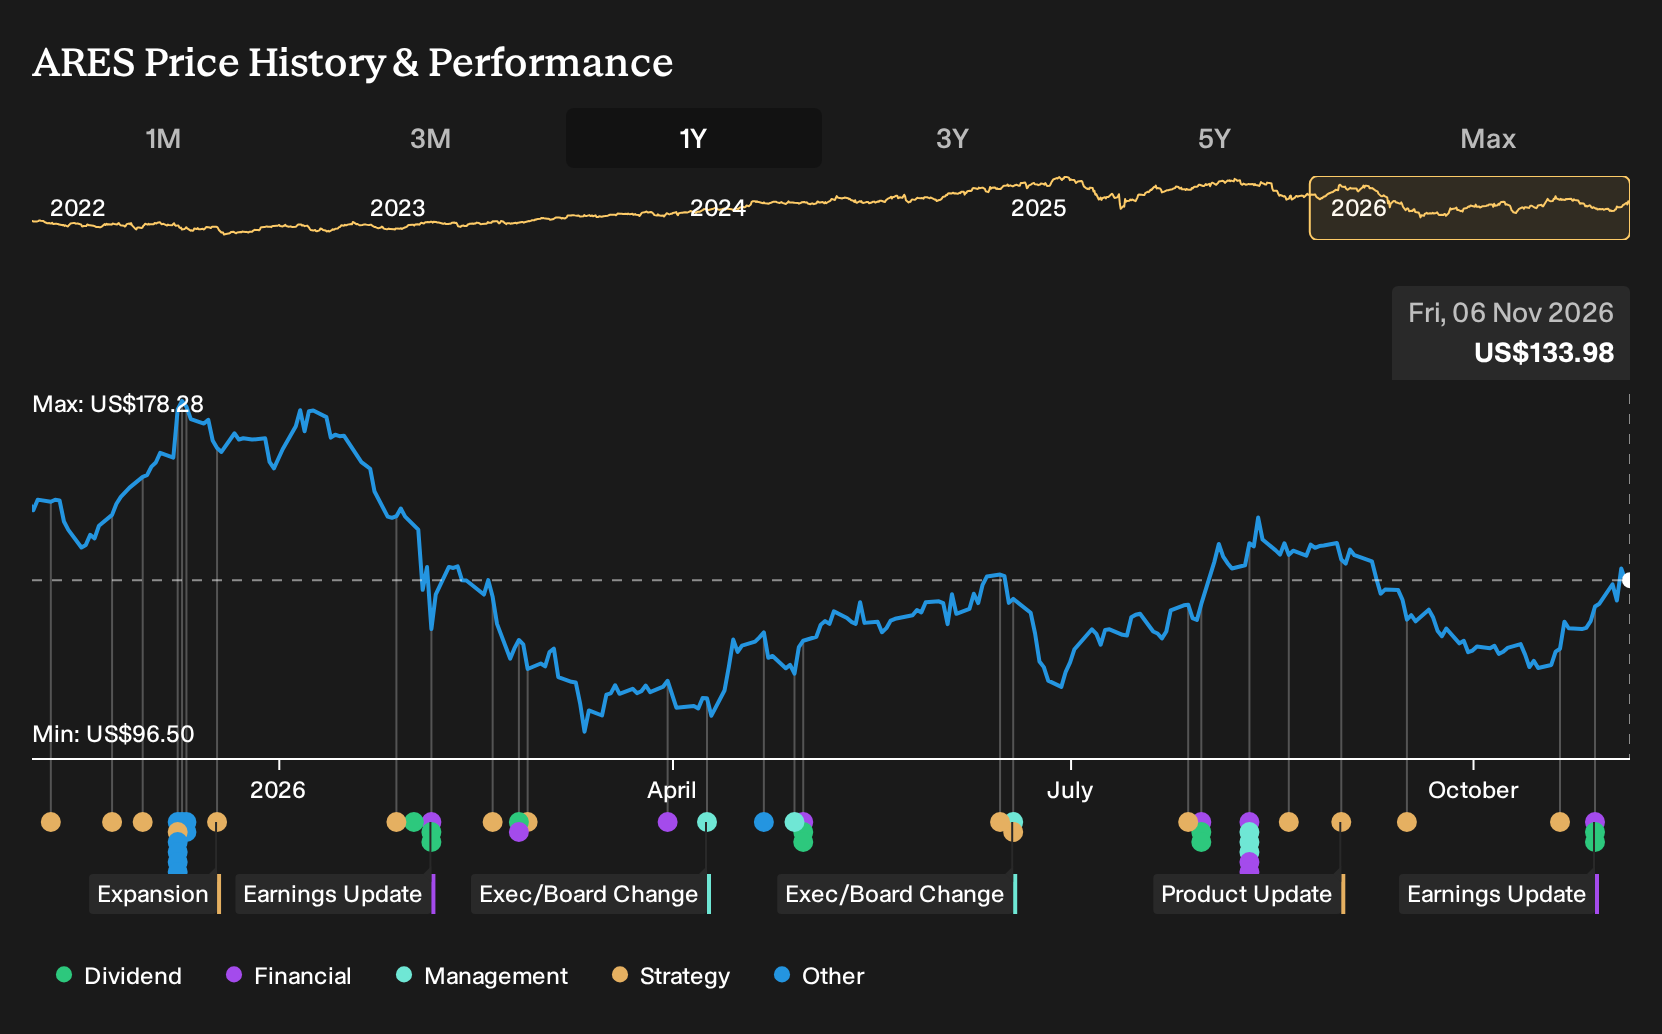
- Ares Management reported third quarter 2026 revenue of US$1,433.4 million and net income of US$85.33 million, with earnings per share of US$0.21 from continuing operations, and declared quarterly dividends on both its preferred and common stock payable at the end of 2026 and start of 2027.
- The sharp year on year drop in quarterly profit and earnings per share sits beside steady dividend commitments. This puts a spotlight on how Ares Management balances shareholder payouts with the pressure that lower current profitability can place on its fee driven business model.
- The next step is to review how Ares Management's weaker third quarter earnings could influence the investment narrative that focuses on fee growth.
Ares Management Investment Narrative Recap
An investor in Ares Management has to believe that its fee engine across credit, private equity and real assets can keep compounding despite earnings volatility. The analyst consensus narrative on Simply Wall St hinges on secular demand for alternatives and on Ares turning undeployed capital into fee paying assets. The sharp drop in quarterly profit highlights execution risk around margins, but does not on its own rewrite that bigger picture.
The more immediate swing factor is whether wealth channel redemptions and fundraising conditions keep fee related earnings on track. Weaker quarterly net income makes the existing risk points more visible, especially concerns around valuation, dividend coverage and debt being less supported by operating cash flow.
The most relevant fresh data point for this story is the third quarter 2026 earnings release itself. Revenue for the quarter was US$1,433.4 million, with net income of US$85.33 million and basic EPS from continuing operations of US$0.21. For the first nine months, revenue was US$4,258.45 million and net income was US$378.55 million.
Those figures sit alongside the affirmed quarterly dividends on both common and preferred shares. That combination keeps the focus on execution. Management needs to grow fee based earnings from areas like infrastructure, logistics and data centers while also covering a 4.03% dividend that screening flags as not well supported by current earnings and free cash flow.
Ares Management's narrative projects US$7.0b revenue and US$2.0b earnings by 2029. That aligns with analysts assuming 10.2% yearly revenue growth and implies earnings would need to rise by about US$1.5b from US$487.4m today.
Uncover why Ares Management's fair value indicates an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on Ares Management focuses on margin pressure if costs keep rising faster than fee income. The most cautious analysts were already pencilling in about US$7.1b of 2029 revenue and US$1.9b of earnings before this weaker quarter. That group paints a tighter story, and this new result could push opinions even further apart.
Explore 2 other Ares Management fair value estimates, including one that suggests as much as 9% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Ares Management research is our analysis highlighting 1 key reward and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Ares Management. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ares Management's overall financial health at a glance.
Looking For More Ares Management Investment Alternatives?
If the latest Ares Management earnings have you reassessing your watchlist, it can help to line this stock up against others with different risk and income profiles using the Simply Wall St Screener.
- For steadier balance sheets and healthier fundamentals, compare Ares Management with companies on our list of solid balance sheet and fundamentals (25 results).
- If income is your focus, weigh Ares alongside businesses in our 7 dividend fortresses that may offer more resilient payouts.
- To broaden your radar beyond well known tickers, scan the 19 high quality undiscovered gems that combine quality with quieter market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com