


EN
Uber (UBER) Stock May Look Fully Priced Despite Robotaxi Expansion News
Uber Technologies has been a volatile ride for shareholders, and after a mixed run in recent years the live question is whether the current price around US$68.59 is properly supported by the earnings the business is producing.
- Over the past 5 years, Uber Technologies has returned 57.3%, which puts real pressure on the current earnings profile to justify what investors have already paid for the stock.
- Fresh headlines around issues like a £2.6b VAT claim in the UK and big capital commitments to robotaxis and delivery partnerships can shift expectations for future profitability, cash requirements, and the timing of any surplus earnings to shareholders.
- The analysts covering Uber Technologies have run their own numbers. See what analysts think Uber Technologies's shares could be worth.
The issue now is whether Uber Technologies' earnings are strong and resilient enough to make the present valuation look sensible on an earnings basis.
If you want a broader set of ideas while you assess Uber Technologies and the recent headlines, a focused stock screen built around 39 high quality undervalued stocks can be a useful next stop in your research.
Has Uber Technologies Run Too Far on Earnings?
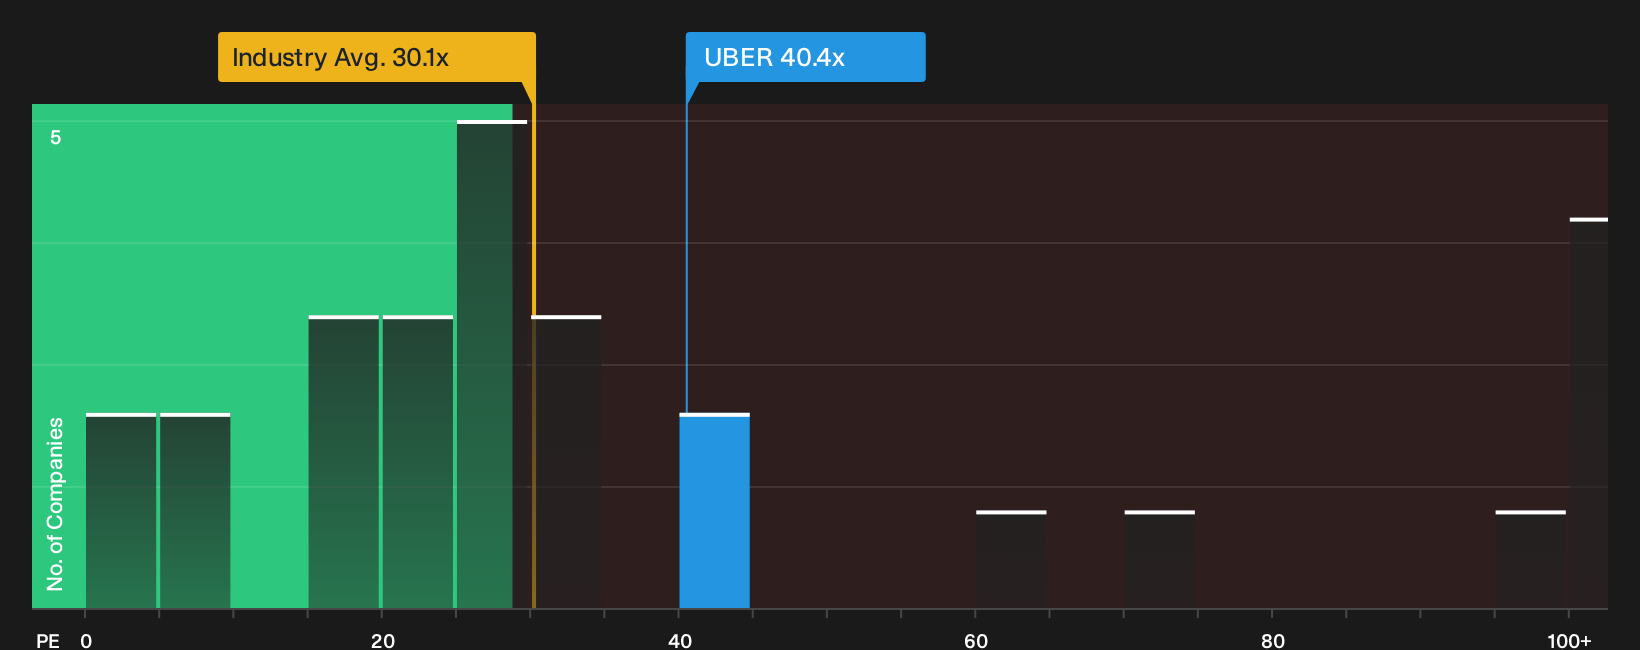
The P/E ratio fits Uber Technologies because earnings are now a key reference point for how the share price stacks up against what the business is producing. At roughly 40.4x, Uber’s P/E sits below the peer group average of 43.6x yet above the broader Transportation sector on about 30.1x. This tells you the market is still willing to pay a premium over the sector for this platform, but not an extreme one relative to closer rivals.
The fair multiple from Simply Wall St’s model, which blends assumptions about growth prospects, profitability and risk, comes out lower than where Uber trades today, so the current P/E screens as overvalued on that framework. Despite the recent £2.6b UK VAT claim and continuing spend on robotaxis and delivery tie ups, the valuation still leans on investors accepting a richer multiple for Uber’s earnings than the model implies is comfortable at this point. Explore the numbers behind Uber Technologies's P/E valuation.
The Uber Technologies Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for Uber Technologies' valuation leaves off, by spelling out which paths for future growth, profitability and earnings would need to play out for the share price to appear meaningfully higher or lower than today. Instead of a single output from a ratio or valuation model, they set out the future that number rests on so you can watch over time whether those conditions actually show up in the business.
One of the top community narratives on Uber Technologies: 41% undervalued
According to Ivoed, an investor in the Simply Wall St Community, the real question is how autonomous vehicles could reshape Uber Technologies over time.
"The reason for that disconnect is increasingly obvious, autonomous vehicles have become Uber’s most important valuation variable…"
Discover why this Narrative puts Uber Technologies at 41% undervalued.
One more piece of Uber Technologies that could change the story
Share price math only goes so far when the real leverage comes from who calls the shots at Uber Technologies, how their incentives are wired, and what that might push them to prioritise next. See who runs Uber Technologies and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com