


EN
Should Nine Month Earnings Growth Require Action From BCP Investors?
- Banco Comercial Português reported net income of €873.7 million for the nine months to 30 September 2026, with basic and diluted earnings per share of €0.057 compared with €0.05 for the same period a year earlier.
- The gap between net income and earnings per share year on year highlights how Banco Comercial Português’s profitability progress is being spread across a relatively stable share count.
- We will now look at how Banco Comercial Português’s investment narrative could be affected by the stronger nine month earnings delivery.
Scan how Banco Comercial Português stacks up against other banks with solid profitability trends by reviewing the hand picked list of solid balance sheet and fundamentals (193 results) alongside this earnings update.
Banco Comercial Português Investment Narrative Recap
To own Banco Comercial Português, you need to be comfortable with a fairly traditional banking story that leans on loan volume, fee income and disciplined risk costs across Portugal, Poland and Mozambique. The latest nine month net income of €873.7 million and earnings per share of €0.057 support the analyst consensus Narrative on Simply Wall St that assumes earnings growth and improving profitability over time.
The near term swing factor is still the interest rate path in Portugal and Poland. A faster fall in rates could pressure net interest margins if loan volumes and fees do not offset the squeeze. On the risk side, heavier exposure to SME and corporate lending, plus Mozambique sovereign and political uncertainty, keep credit costs and capital consumption in focus.
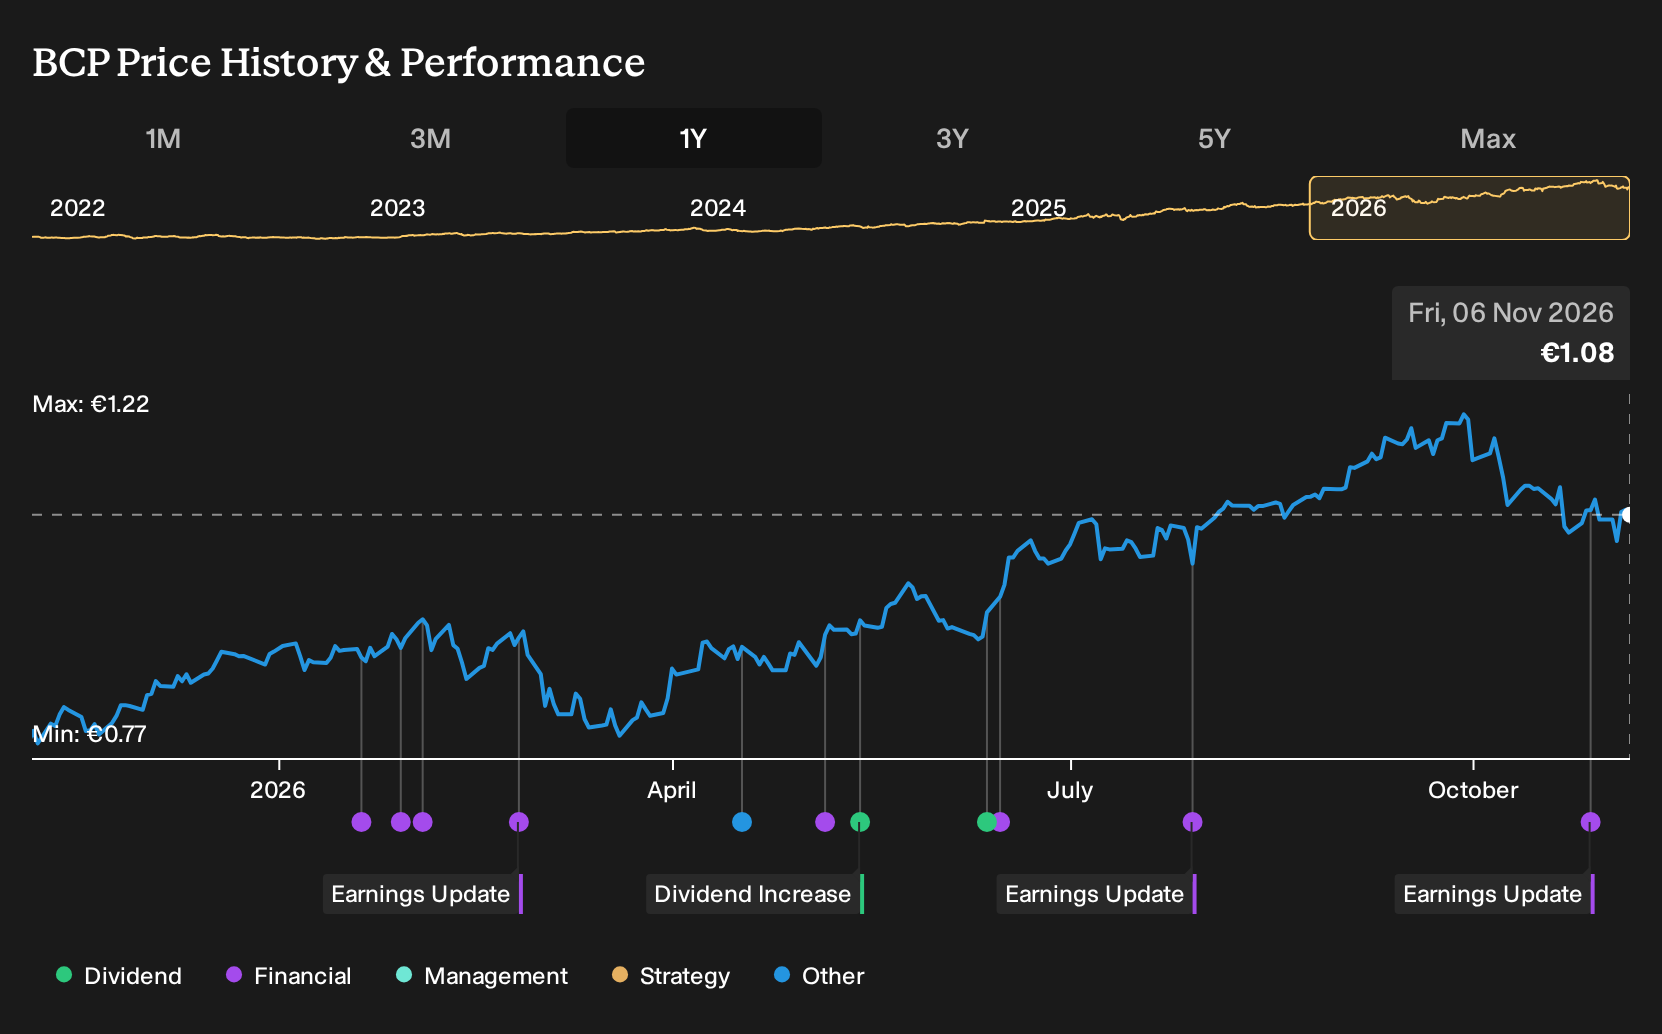
The most relevant fresh information for that story is the October 2026 earnings release itself. Management reported net income of €873.7 million for the nine months to 30 September 2026 compared with €775.92 million a year earlier, with both basic and diluted earnings per share at €0.057 versus €0.05. That gives you a cleaner read on how the operating engine is running right now.
Those figures sit against analyst expectations of mid single digit loan growth, disciplined cost of risk and earnings expansion of around 11.8% per year. They also feed directly into views on valuation, given Banco Comercial Português is flagged as trading at a discount to an estimate of its future cash flow value while on a higher P/E than many European banking peers. Investors will likely keep testing whether future updates confirm that earnings path while monitoring any hit from rate cuts, regulation or Mozambique exposures.
Banco Comercial Português' narrative projects €4.6 billion revenue and €1.5 billion earnings by 2029, which implies 7.7% yearly revenue growth and an earnings increase of about €0.5 billion from €1.0 billion today.
Uncover why Banco Comercial Português' fair value highlights an 11% potential upside to its current price that could close sooner than investors expect.
Exploring Other Perspectives
Across 3 fair value estimates from the Simply Wall St Community, Banco Comercial Português is pegged between €1.20 and about €1.49, with most views clustered in the lower half of that range. Some contributors focus on stronger recent earnings, while others flag interest rate cuts or Mozambique risk as reasons to stress test their own assumptions.
Explore 2 other Banco Comercial Português fair value estimates, including one that suggests as much as 38% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Banco Comercial Português research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Banco Comercial Português. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Banco Comercial Português' overall financial health at a glance.
Looking For More Ideas Beyond Banco Comercial Português?
If the Banco Comercial Português story has you thinking about how to round out your watchlist, it can help to scan a wider field of stocks that share some of the qualities you care about most.
- For readers who want potential mispricing combined with solid fundamentals, consider running a screen focused on quality companies that trade below what their financials might justify through the 227 high quality undervalued stocks.
- If income is a priority and you prefer listed businesses that aim to return a meaningful portion of cash to shareholders, take a look at the 227 dividend fortresses to see which payers currently clear that bar.
- For a focus on balance sheet strength and resilient financial profiles, filter for companies that pair prudent leverage with dependable fundamentals using the 207 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com