


EN
C.H. Robinson Worldwide (CHRW) Reworks Debt Facilities To Fund Its RXO Acquisition
- C.H. Robinson Worldwide (NasdaqGS:CHRW) has amended its credit agreements and financing facilities to support its planned acquisition of RXO, Inc.
- The revised debt structure substantially extends existing maturities and increases revolving credit commitments to meet funding needs for the RXO deal.
- Covenant terms across the company’s facilities have been modified to align with the larger balance sheet and integration requirements tied to RXO.
- The extensive changes to CHRW’s credit covenants and facilities for the RXO acquisition should not be the only thing you weigh today. We have also flagged 1 warning sign for C.H. Robinson Worldwide.
For readers tracking how large transport and logistics platforms reshape their funding mix for major deals, the wider trend in capital intensive enablers of freight digitisation and AI driven supply chains is worth exploring through 53 AI infrastructure stocks.
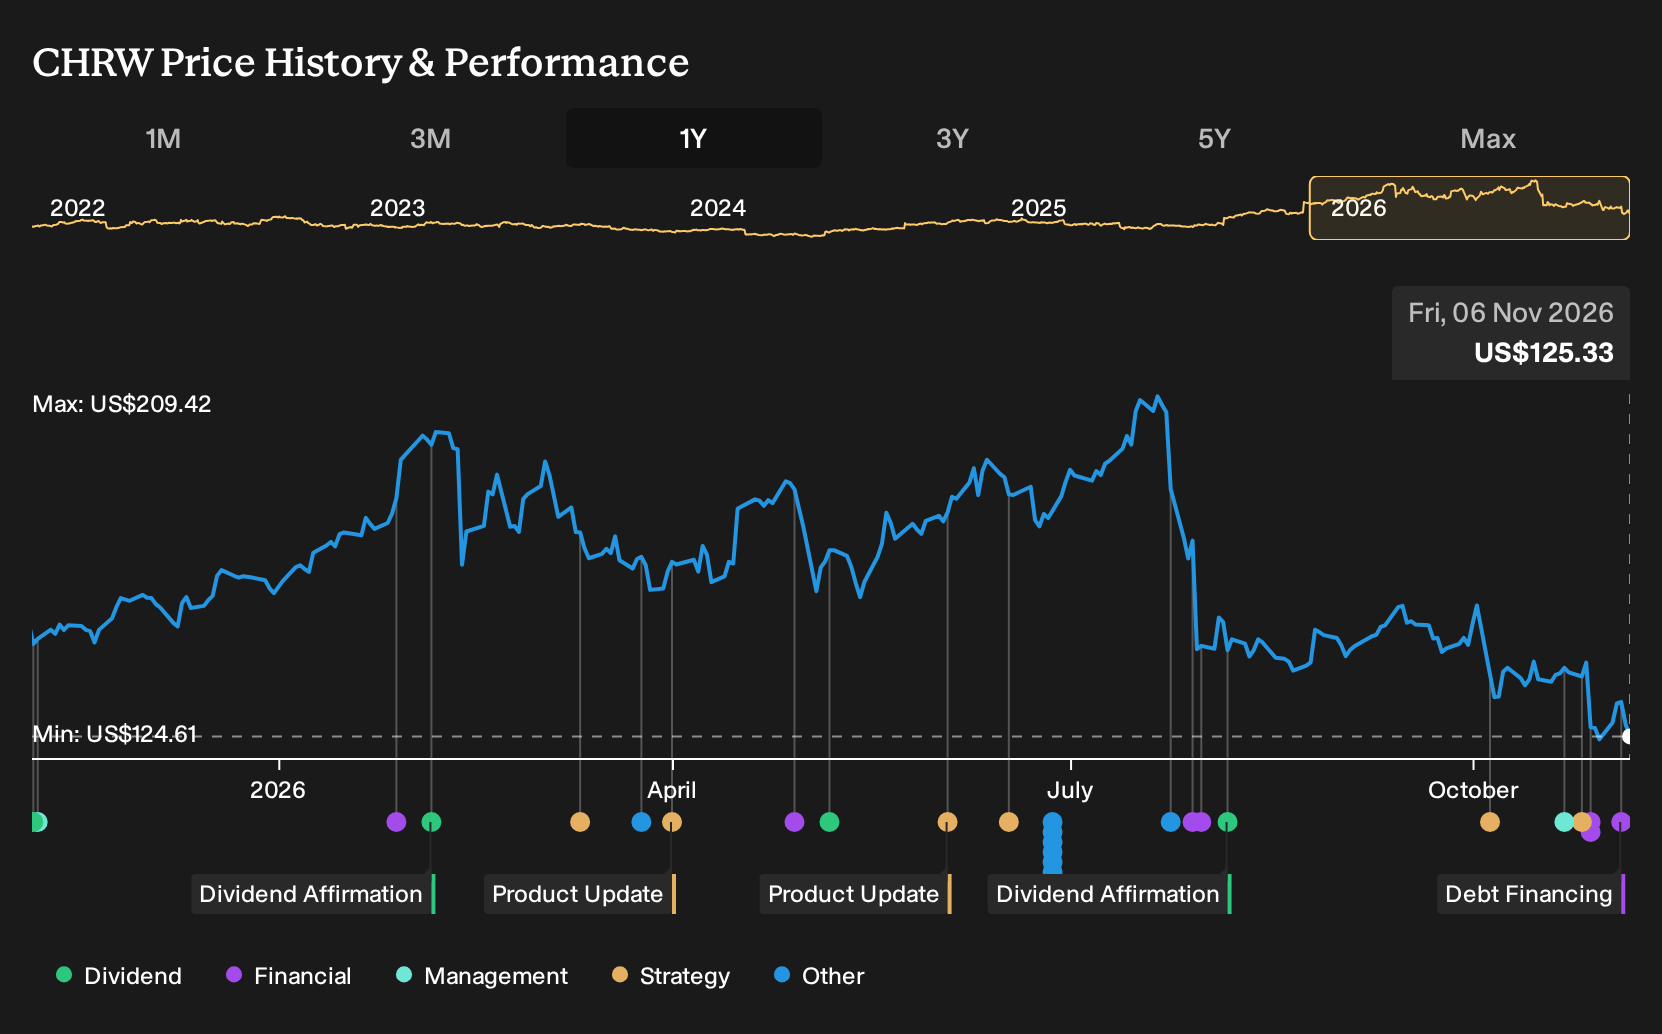
C.H. Robinson Worldwide runs freight transportation and broader logistics and supply chain services across the US and international routes. As a result, reshaping its credit profile around the RXO deal directly affects how this $14.5b platform finances capacity, technology and contract commitments for shippers.
See how C.H. Robinson Worldwide's balance sheet measures up.
RXO debt terms test whether C.H. Robinson’s AI efficiency story can carry a heavier balance sheet
C.H. Robinson Worldwide’s Narrative asks investors to back an AI driven, higher productivity freight platform, and this RXO focused refinancing effectively hard-wires that belief into a larger, more flexible debt stack.
"The main factor that has to go right is that C.H. Robinson Worldwide continues to convert brokerage consolidation and shipper preference for larger, well insured providers into durable share gains while managing legal and insurance exposures..."
See how the full story points towards a $183 fair value for C.H. Robinson Worldwide.
The amended credit agreement extends maturities to 2031, increases revolver and accordion capacity, and relaxes some intercompany and covenant constraints. That lines up with a Narrative that assumes C.H. Robinson can run a bigger, more complex network with Lean AI automation while absorbing RXO and still managing leverage inside a 3.75x to 4.25x corridor. For a business often compared with brokers like RXO itself and XPO, the bet is that scale plus productivity can support this higher debt load.
New EBITDA add backs for restructuring, integration and projected synergies, along with extra leverage holidays, give management more room to keep financing in bounds while they integrate RXO and pursue the US$300m synergy plan referenced in analyst commentary. The flip side is that Simply Wall St’s risk flags already highlight high debt, so a larger unsecured stack and higher judgment thresholds could worry investors who focus on legal exposures and tighter broker margins.
Whether this refinancing looks attractive or uncomfortable depends largely on which Narrative you believe, an AI powered scale story that can carry more leverage, or a more cautious view that sees balance sheet risk crowding out the upside.
One more question for C.H. Robinson Worldwide that cuts straight to what the business could actually be worth
Debt terms, AI plans and integration hurdles all matter, but the real anchor is what C.H. Robinson’s future cash generation suggests the whole enterprise is worth compared with today’s share price. Find out exactly what C.H. Robinson Worldwide is worth today based on its cash flows.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com